

India Smart Meter Market, 2032
- Energy, Power & Storage, Grid & Power Infrastructure
- Nov 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s smart meter sector is witnessing strong structural growth, driven by central funding under RDSS, the prepaid smart metering mandate, AT&C loss reduction targets, rapid scaling of TOTEX-based AMISP contracts, rising domestic manufacturing of meters and communication modules, and growing smart gas and smart water metering across city gas distribution and urban water utilities.
| Study Duration | 2021-2032 |
| Market Size (2025) | USD 2,140 Million |
| CAGR (2026-2032) | 12.4% |
| Leading Segment | Single-Phase Smart Electricity Meters (Residential) |
| Fastest Growing Segment | Smart Gas Meters |
| Market Size (2032) | USD 4,860 Million |
Market Overview: India Smart Meter Market
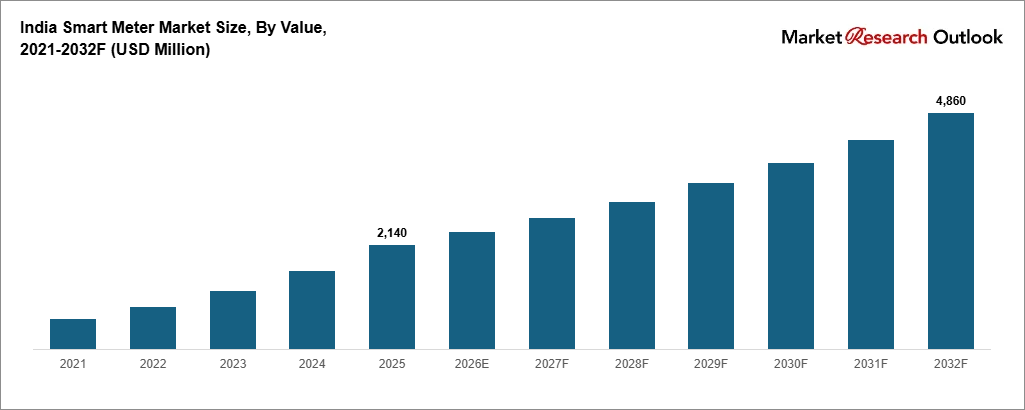
The India smart meter market size is witnessing rapid expansion, driven by central funding under the Revamped Distribution Sector Scheme, the prepaid smart metering mandate, AT&C loss reduction targets, large AMISP contracts and growing domestic manufacturing capacity. Valued at USD 2,140 million in 2025 and projected to reach USD 4,860 million by 2032, growing at a CAGR of 12.4%, India smart meter market growth is being fuelled by consumer meter replacement at state DISCOMs, distribution transformer and feeder metering for energy audits, and rising smart gas and smart water metering. Single-phase smart electricity meters lead the market, while smart gas meters form the fastest growing category. Falling AT&C losses, from 21.91% in FY21 to 15.04% in FY25, together with collection efficiency rising from 92.9% to 97% over the same period, show DISCOMs the financial case for metering at scale. As meter makers including Genus Power, HPL Electric & Power, Secure Meters and Kimbal expand output, and AMISPs including Adani Energy Solutions, IntelliSmart, Tata Power and Apraava Energy scale field installation, the sector is evolving into a utility-led, data-driven and service-based industry with strong long-term growth potential.
Key Report Takeaways: India Smart Meter Market
- The India smart meter market size is projected to grow from USD 2,140 million in 2025 to USD 4,860 million by 2032, registering a strong CAGR of 12.4%, driven by RDSS funding, the prepaid smart metering mandate and the structural shift toward AMI-based billing and energy accounting at state DISCOMs.
- Single-phase smart electricity meters dominate the market, accounting for 58% of total value in 2025, driven by household meter replacement under RDSS, prepaid billing, and the large presence of meter makers such as Genus Power, HPL Electric & Power, Secure Meters and Kimbal across state tenders.
- Smart gas meters are emerging as the fastest growing product segment, expected to grow at a CAGR of 19.8% through 2032, as city gas distribution companies expand piped natural gas connections and move toward prepaid and remotely read gas metering across metro and tier-2 cities.
- Smart meter installations under RDSS reached 5.73 crore by 30 June 2026 against 20.33 crore sanctioned, while total smart meters installed across all schemes reached 7.24 crore, leaving a large pipeline for consumer, DT and feeder metering through 2032.
- Rising order books at meter makers and AMISPs, including Genus Power at INR 24,020 crore in June 2026 and Adani Energy Solutions at 2.46 crore meters, are strengthening domestic supply and supporting the India smart meter market forecast 2032.
Key Market Drivers: India Smart Meter Market
RDSS Funding and the Prepaid Smart Metering Mandate Accelerating Nationwide Smart Meter Rollout
Growth in the India smart meter market is driven first by the Revamped Distribution Sector Scheme, launched in July 2021 with a total outlay of INR 3,03,758 crore and central gross budgetary support of INR 97,631 crore. Smart metering works worth INR 1.31 lakh crore have been sanctioned under the scheme, alongside INR 1.53 lakh crore for loss reduction infrastructure. Of the 20.33 crore smart meters sanctioned, 19.79 crore are consumer meters, 52.53 lakh are distribution transformer meters and 2.05 lakh are feeder meters. Installation reached 5.73 crore under RDSS by 30 June 2026, including 5.53 crore consumer meters, 18.50 lakh DT meters and 1.85 lakh feeder meters, with the scheme sunset date set at 31 March 2028. The prepaid smart metering mandate, consumer rebates for prepaid connections, and grant release linked to loss reduction create strong pull-through demand for meters, communication networks and data platforms.
AT&C Loss Reduction Targets and DISCOM Financial Turnaround Driving Demand for Accurate Energy Accounting
The sector benefits from DISCOMs’ need to cut losses and improve cash flow. National AT&C losses fell from 21.91% in FY21 to 15.04% in FY25, billing efficiency improved from 84.08% to 87.59%, and collection efficiency rose from 92.9% to 97% over the same period. Smart meters support this shift by removing manual reading errors, enabling remote disconnection for non-payment, and giving utilities daily consumption data for every connection. Distribution transformer and feeder meters add energy audit capability, helping DISCOMs locate commercial losses at the feeder and transformer level rather than relying on estimates. With central grants under RDSS linked to measured progress on loss reduction, state DISCOMs in Maharashtra, Uttar Pradesh, Gujarat, Rajasthan and Madhya Pradesh are treating smart metering as a priority investment, supporting steady demand across the India smart meter market.
TOTEX-Based AMISP Model, Private Capital and Domestic Manufacturing Scaling Smart Meter Deployment
The TOTEX model is a major catalyst for smart meter adoption in India, as Advanced Metering Infrastructure Service Providers fund meter supply, installation, communication and data systems, and recover costs through a monthly per-meter charge over the contract period. This removes upfront capital pressure from DISCOMs and has drawn private and institutional capital into the sector. Adani Energy Solutions crossed 1 crore smart meter installations in February 2026, holding an order book of 2.46 crore meters and installing close to 25,000 meters per day. Genus Power crossed 1 crore smart meter installations in FY26, reported an order book of INR 24,020 crore in June 2026, and runs manufacturing capacity of 1.8 crore meters per year. IntelliSmart, Tata Power, Apraava Energy and Polaris Smart Metering are scaling AMISP operations across multiple states. Combined with domestic meter output, this delivery model is structurally expanding India smart meter market growth through 2032.
Key Market Challenges: India Smart Meter Market
Slow Installation Progress Against Sanctioned Volumes Ahead of the RDSS Sunset Date
The sector faces a clear execution gap, with 5.73 crore of the 20.33 crore RDSS sanctioned smart meters installed by 30 June 2026, equal to 28% of the sanctioned volume. Progress varies widely by state. Maharashtra installed 1.30 crore meters and Uttar Pradesh 97.54 lakh, while Tamil Nadu installed 9,746 against 3.05 crore sanctioned, Punjab 14,662 against 89.81 lakh, and Kerala 1.93 lakh against 1.34 crore. With the scheme sunset set at 31 March 2028, the remaining volume requires much faster tendering, contract award, consumer indexing and installation. Delays in AMISP tender finalisation, re-tendering after price discovery, and site access issues stretch timelines, while late-starting states risk crowding installation into a short window, putting pressure on meter supply, field teams and quality checks across the sector.
Consumer Resistance to Prepaid Billing and High-Bill Complaints Delaying State-Level Rollout
Consumer acceptance remains a practical constraint. In several states, households have raised complaints about higher bills after smart meter installation, often linked to the correction of earlier under-reading, estimated billing or faulty old meters rather than to the smart meter itself. Prepaid billing also changes payment habits, as low balance alerts and automatic disconnection require consumers to recharge regularly through apps or counters. Political sensitivity around electricity tariffs has led some states to slow or pause prepaid conversion, and resident groups have opposed installation in certain districts. Utilities are responding with check meters, awareness drives, grace periods before disconnection and rebates for prepaid consumers, yet trust building takes time and remains a near-term challenge for smart meter rollout in India.
Import Dependence for Semiconductors and Communication Modules Pressuring Supplier Margins
Meter makers and AMISPs face cost and cash flow pressure. Metering ICs, microcontrollers, communication chipsets and certain passive components are still largely imported, which exposes suppliers to currency movements, shipping delays and chip supply cycles. AMISP contracts are priced as a fixed monthly charge per meter over the contract period, so any rise in component, labour or financing cost after bidding directly reduces project returns. Payment delays from financially weak DISCOMs add working capital strain, as AMISPs fund installation upfront and recover costs over several years. Payment security mechanisms and growing domestic electronics capacity are emerging as solutions, but price pressure in competitive tenders remains a barrier for smaller suppliers in the sector.
Key Market Trends: India Smart Meter Market
Rapid Shift Toward Prepaid Smart Meters, Consumer Apps and Time-of-Day Tariffs
The sector is undergoing a clear shift toward prepaid smart meters linked to consumer mobile apps, digital recharge and time-of-day tariffs. Under the Electricity (Rights of Consumers) Amendment Rules, 2023, time-of-day tariffs apply to commercial and industrial consumers with maximum demand of 10 kW and above from 1 April 2024, and to most other consumers except agricultural from 1 April 2025, taking effect right after smart meter installation. This makes the smart meter the enabling device for time-based pricing. Consumers can now track daily usage, receive low balance alerts and recharge through apps and payment platforms, while DISCOMs gain better cash flow and fewer arrears. Rooftop solar net meters, electric vehicle charging connections and demand response pilots are adding new use cases, reinforcing the India smart meter market forecast 2032 across both residential and commercial categories.
Growth of RF Mesh, 4G and NB-IoT Communication with Cloud-Based MDM Analytics
A clear shift toward reliable, multi-technology communication is reshaping smart metering in India. RF mesh networks lead urban and semi-urban deployments, accounting for 46% of the communication technology segment in 2025, while cellular 4G LTE holds 24% and NB-IoT 12%, with NB-IoT gaining share in dispersed rural areas where mesh density is low. Hybrid RF-cellular modules are being adopted to lift daily read rates in hilly and dense urban zones. On the software side, head-end systems and meter data management platforms are moving toward cloud hosting, with analytics for theft detection, load forecasting, transformer health and outage alerts. These platforms turn raw meter data into billing, collection and network planning inputs, raising the value of each installed smart meter across the India smart meter market.
Capacity Expansion by Domestic Meter Makers and Large AMISP Order Books
A wave of capacity expansion is reshaping the supply side of smart metering in India. Genus Power reported Q1FY27 revenue of INR 1,364.9 crore, up 44.8% year on year, with manufacturing capacity of 1.8 crore meters per year and a target of at least 1 crore smart meter installations in FY27. Adani Energy Solutions holds mandates for 2.46 crore meters and expects to install another 1 crore meters in the next financial year. HPL Electric & Power, Secure Meters, Kimbal and Schneider Electric have also scaled smart meter lines for state tenders. Rising localisation of meter assembly, enclosures and printed circuit boards, along with growing domestic interest in communication module manufacturing, is improving delivery timelines. Combined with large AMISP order books and DT and feeder metering for energy audits, these developments are reinforcing the India smart meter market forecast 2032 across the value chain.
Segmental Insights: India Smart Meter Market
By End-User: Residential Segment Dominates the India Smart Meter Market
The residential end-user segment dominates the market, accounting for 64% of total value in 2025, driven by household meter replacement under RDSS, prepaid billing and the sheer number of domestic connections. Single-phase prepaid smart meters are the dominant product within this segment, mostly connected through RF mesh networks in urban areas and cellular or NB-IoT in rural areas. The commercial segment contributes 17% of demand, led by shops, offices, hotels and hospitals moving to three-phase smart meters and time-of-day tariffs. The industrial segment accounts for 11%, supported by CT-operated meters for high-load connections, while agricultural and public services contribute 8%. In 2025 and 2026, AMISPs including Adani Energy Solutions, IntelliSmart and Tata Power scaled household installation across Maharashtra, Uttar Pradesh and Bihar, reinforcing residential leadership.
By Product Type: Single-Phase Smart Meters Lead While Smart Gas Meters Grow Fastest
Single-phase smart electricity meters lead the product mix, accounting for 58% of total value in 2025, driven by household replacement and prepaid conversion under RDSS. Three-phase smart electricity meters contribute 17%, mainly across commercial and larger residential connections, while CT-operated smart meters hold 6% for high-load industrial and commercial users. Distribution transformer and feeder smart meters account for 9%, supporting energy audit and loss mapping at the network level. Smart gas meters, at 6% of value, are the fastest growing category with a CAGR of 19.8% through 2032, driven by piped natural gas expansion by city gas distribution companies, while smart water meters hold 4% and are growing in smart city and urban water projects. Leading manufacturers including Genus Power, HPL Electric & Power, Secure Meters, Kimbal and Landis+Gyr have aligned product portfolios to this mix across the market.
Regional Insights: India Smart Meter Market
Regional analysis shows that West India leads with 31% of total market value in 2025, driven by Maharashtra, which installed 1.30 crore RDSS smart meters by 30 June 2026, and Gujarat with 52.01 lakh. North India contributes 29%, led by Uttar Pradesh with 97.54 lakh meters installed and Rajasthan with 47.59 lakh, followed by Himachal Pradesh, Jammu and Kashmir and Uttarakhand. East India, including the North East, accounts for 18%, supported by Assam with 55.44 lakh meters and Bihar with 23.02 lakh. Central India holds 15%, led by Chhattisgarh with 42.23 lakh and Madhya Pradesh with 41.90 lakh. South India accounts for 7%, with Andhra Pradesh at 32.80 lakh, while Tamil Nadu and Kerala hold large sanctioned volumes that remain largely uninstalled, making South India the region with the highest pending pipeline in the India smart meter market.
State-wise progress: see the India Smart Meter Rollout Tracker for sanctioned and installed meters in every state, the pace of installation in 2026 and which states are on track for the March 2028 deadline.
Recent Developments: India Smart Meter Market
- Smart meter installation gained strong momentum through 2025 and 2026. RDSS installations rose from 4.76 crore in December 2025 to 5.28 crore in February 2026 and 5.73 crore by 30 June 2026, while total smart meters installed across all schemes reached 7.24 crore. Uttar Pradesh, Assam, Bihar and Chhattisgarh recorded some of the highest installation completion against sanctioned volumes, with Assam crossing 55 lakh meters.
- Meter makers and AMISPs deepened capacity and execution. Adani Energy Solutions crossed 1 crore smart meter installations in February 2026, completing the milestone in about 24 months. Genus Power crossed 1 crore smart meter installations in FY26, reported an order book of INR 24,020 crore in June 2026 and set a target of at least 1 crore installations in FY27. These developments are strengthening domestic supply and supporting the India smart meter market forecast 2032.
- Policy and billing reforms gained traction across states. Time-of-day tariffs became applicable to most non-agricultural consumers from 1 April 2025 after smart meter installation, prepaid consumers received rebates, and AT&C losses fell to 15.04% in FY25. Energy accounting through DT and feeder meters is now positioning India as one of the largest smart metering programmes globally, strengthening long-term competitive positioning for the sector through 2032.
Key Market Players: India Smart Meter Market
- Genus Power Infrastructures Limited
- HPL Electric & Power Limited
- Secure Meters Limited
- Adani Energy Solutions Limited
- IntelliSmart Infrastructure Private Limited
- Energy Efficiency Services Limited (EESL)
- Tata Power Company Limited
- Schneider Electric India Private Limited
- Landis+Gyr Limited
- Kimbal Technologies Private Limited
- Apraava Energy Private Limited
- Polaris Smart Metering Private Limited
- Itron India Private Limited
| By Product Type | By Technology | By Component | By Utility Type | By End-User |
| Single-Phase Smart Electricity Meters Three-Phase Smart Electricity Meters CT-Operated Smart Meters (LTCT & HTCT) Distribution Transformer & Feeder Smart Meters Smart Gas Meters Smart Water Meters |
Radio Frequency (RF) Mesh Cellular (4G LTE) NB-IoT Power Line Communication (PLC) LoRaWAN Hybrid RF-Cellular Others |
Smart Meter Hardware Communication Modules & Gateways Head-End System (HES) Meter Data Management (MDM) Software Installation, Integration & O&M Services |
State-Owned DISCOMs Private DISCOMs & Licensees City Gas Distribution Companies Municipal & Urban Water Utilities Industrial Parks & SEZ Operators Housing Societies & Real Estate Developers |
Residential Commercial Industrial Agricultural & Public Services |
Report Scope
In this report, the India Smart Meter Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape and growth opportunities across the forecast period:
- By Product Type
- Single-Phase Smart Electricity Meters
- Three-Phase Smart Electricity Meters
- CT-Operated Smart Meters (LTCT & HTCT)
- Distribution Transformer & Feeder Smart Meters
- Smart Gas Meters
- Smart Water Meters
- By Technology
- Radio Frequency (RF) Mesh
- Cellular (4G LTE)
- NB-IoT
- Power Line Communication (PLC)
- LoRaWAN
- Hybrid RF-Cellular
- Others
- By Component
- Smart Meter Hardware
- Communication Modules & Gateways
- Head-End System (HES)
- Meter Data Management (MDM) Software
- Installation, Integration & O&M Services
- By Utility Type
- State-Owned DISCOMs
- Private DISCOMs & Licensees
- City Gas Distribution Companies
- Municipal & Urban Water Utilities
- Industrial Parks & SEZ Operators
- Housing Societies & Real Estate Developers
- By End-User
- Residential
- Commercial
- Industrial
- Agricultural & Public Services
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Smart Meter Market, including business overview, product portfolio, strategic initiatives, competitive positioning and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging domestic meter makers, communication module suppliers, MDM and head-end software vendors, regional AMISPs or niche smart gas and smart water meter producers.
For a free sample of the India Smart Meter Market report, customised insights or delivery timelines, submit your query here
India Smart Meter Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Product Type
- By Technology
- By Component
- By Utility Type
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Smart Meter Market
- India Smart Meter Market Insights
- Market Dynamics
- Growth Drivers
- RDSS funding and the prepaid smart metering mandate accelerating nationwide consumer, DT and feeder meter rollout.
- AT&C loss reduction targets and DISCOM financial turnaround driving demand for accurate energy accounting.
- TOTEX-based AMISP model, private capital and domestic manufacturing capacity scaling smart meter deployment.
- Restraints
- Slow installation progress against sanctioned volumes, with only 28% of RDSS smart meters installed by June 2026.
- Consumer resistance to prepaid billing and high-bill complaints delaying rollout in several states.
- Import dependence for semiconductors and communication modules, along with DISCOM payment delays, pressuring margins.
- Opportunities
- Replacement of 25 crore conventional meters opening long-tenure AMI service and O&M revenue pools.
- Time-of-day tariffs, rooftop solar net metering and demand response creating demand for meter data analytics.
- Smart gas and smart water metering expansion across city gas distribution and urban water utilities.
- Challenges
- Communication reliability gaps in rural, hilly and dense urban areas affecting daily meter read rates.
- Cybersecurity, data privacy and interoperability requirements across multi-vendor AMI systems.
- Shortage of skilled field workforce for large-scale installation, consumer indexing and meter maintenance.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Components (metering ICs, microcontrollers, current sensors, latching relays, PCBs, enclosures, batteries)
- Smart Meter Manufacturers (Genus, HPL, Secure Meters, Schneider Electric, Kimbal, Landis+Gyr)
- Communication Module & Network Providers (RF mesh, 4G LTE, NB-IoT, PLC and LoRaWAN modules)
- Head-End System & MDM Software Vendors (data acquisition, billing integration, analytics platforms)
- Testing, Certification & Standards Bodies (BIS IS 16444, CEA metering regulations, NABL laboratories)
- Advanced Metering Infrastructure Service Providers (AMISPs under TOTEX contracts)
- System Integrators & EPC Contractors (installation, consumer indexing, field operations)
- Financing & Platform Investors (infrastructure funds, banks, NBFCs, multilateral lenders)
- Utilities & Programme Agencies (state DISCOMs, private DISCOMs, EESL, REC, PFC, CGD and water utilities)
- End-Users (households, commercial establishments, industries, agricultural and public service connections)
- India Smart Meter Market: Regulatory Framework
- India Smart Meter Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (Million Units)
- Market Share & Forecast
- By Product Type
- Single-Phase Smart Electricity Meters
- Three-Phase Smart Electricity Meters
- CT-Operated Smart Meters (LTCT & HTCT)
- Distribution Transformer & Feeder Smart Meters
- Smart Gas Meters
- Smart Water Meters
- By Technology
- Radio Frequency (RF) Mesh
- Cellular (4G LTE)
- NB-IoT
- Power Line Communication (PLC)
- LoRaWAN
- Hybrid RF-Cellular
- Others
- By Component
- Smart Meter Hardware
- Communication Modules & Gateways
- Head-End System (HES)
- Meter Data Management (MDM) Software
- Installation, Integration & O&M Services
- By Utility Type
- State-Owned DISCOMs
- Private DISCOMs & Licensees
- City Gas Distribution Companies
- Municipal & Urban Water Utilities
- Industrial Parks & SEZ Operators
- Housing Societies & Real Estate Developers
- By End-User
- Residential
- Commercial
- Industrial
- Agricultural & Public Services
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Smart Meter Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Genus Power Infrastructures Limited
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- HPL Electric & Power Limited
- Secure Meters Limited
- Adani Energy Solutions Limited
- IntelliSmart Infrastructure Private Limited
- Energy Efficiency Services Limited (EESL)
- Tata Power Company Limited
- Schneider Electric India Private Limited
- Landis+Gyr Limited
- Kimbal Technologies Private Limited
- Apraava Energy Private Limited
- Polaris Smart Metering Private Limited
- Itron India Private Limited
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India smart meter market and what is its growth forecast?
Ans: The India smart meter market is valued at USD 2,140 million in 2025 and is projected to reach USD 4,860 million by 2032, growing at a CAGR of 12.4%, supported by RDSS funding, prepaid metering and AMISP rollout.
2. Which segments are driving demand in smart metering in India?
Ans: Single-phase smart electricity meters lead with 58% of 2025 value and residential users hold 64%, while smart gas meters are the fastest growing product segment at a CAGR of 19.8% through 2032.
3. What are the key drivers of growth in smart metering in India?
Ans: Key drivers include RDSS funding and the prepaid metering mandate, AT&C loss reduction targets at state DISCOMs, and the TOTEX-based AMISP model supported by private capital and rising domestic meter manufacturing capacity.
4. Which regions are driving growth in smart metering in India?
Ans: West India leads with 31% of 2025 value, driven by Maharashtra and Gujarat, followed by North India at 29%, led by Uttar Pradesh and Rajasthan. South India holds the largest pending installation pipeline.
5. What are the latest trends in smart metering in India?
Ans: Latest trends include prepaid smart meters with consumer apps, time-of-day tariffs, RF mesh, 4G and NB-IoT communication, cloud-based meter data analytics, and capacity expansion by domestic meter makers and AMISPs.