

India Distribution Transformer Market Size & Forecast 2032
- Energy, Power & Storage, Grid & Power Infrastructure
- Oct 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s distribution transformer market is witnessing strong structural growth, driven by the INR 3.03 lakh crore Revamped Distribution Sector Scheme, sanctioned projects worth INR 2.83 lakh crore, an installed fleet of roughly 1.74 crore units reaching end of life, tightened loss limits under the revised IS 1180, smart metering across 52.53 lakh transformers, rooftop solar and vehicle charging load, and rising interest from manufacturers investing in amorphous core and higher star rated designs.
Report Description
| Study Duration | 2021-2032 |
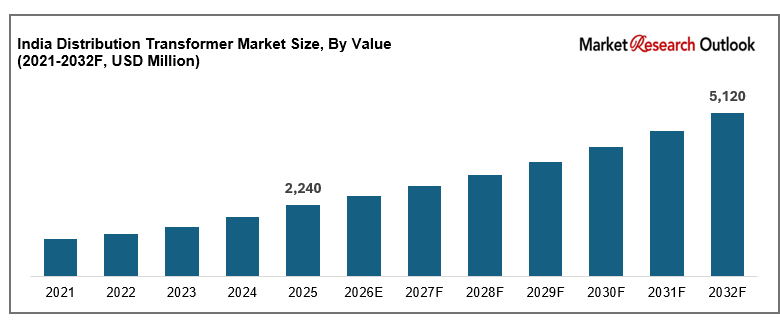
| Market Size (2025) | USD 2,240 Million |
| CAGR (2026-2032) | 12.5% |
| Leading Segment | Oil-Immersed Units (26 kVA to 100 kVA) |
| Fastest Growing Segment | Amorphous Core & BEE 5-Star Units |
| Market Size (2032) | USD 5,120 Million |
India Distribution Transformer Market Overview
The India distribution transformer market size is witnessing rapid expansion, driven by the Revamped Distribution Sector Scheme, a large ageing fleet reaching end of life, tightened loss limits under IS 1180, transformer-level metering, and new load types arriving on the low tension network. Valued at USD 2,240 million in 2025 and projected to reach USD 5,120 million by 2032, growing at a CAGR of 12.5%, the India distribution transformer market growth is being fuelled by procurement across Uttar Pradesh, Bihar, Rajasthan, Madhya Pradesh, Maharashtra and Tamil Nadu. Oil-immersed units lead the product mix, while amorphous core and BEE 5-star designs are the fastest growing categories. Delivery against sanctioned volume, not demand, is the binding constraint. As Voltamp Transformers, Transformers and Rectifiers, Bharat Bijlee, CG Power and Bharat Heavy Electricals expand output, the Indian grid modernization market is evolving into a scheme-funded, efficiency-regulated, and increasingly measured sector with strong long-term growth potential.
Related research: India Transmission Infrastructure Market, India Power Transformer Market and India Electricity Demand Market.
Key Report Takeaways: India Distribution Transformer Market
- The India distribution transformer market size is projected to grow from USD 2,240 million in 2025 to USD 5,120 million by 2032, registering a strong CAGR of 12.5%, driven by scheme-funded procurement, accelerated replacement, and the shift toward higher efficiency classes across the Indian network.
- Oil-immersed units dominate the India distribution transformer market, accounting for 52% of value in 2025, driven by cost, field repairability and the sheer weight of rural and semi-urban feeder demand, with pole-mounted designs taking a further 19% of the product mix.
- Amorphous core and BEE 5-star rated designs are emerging as the fastest growing segments in the India distribution transformer market, expected to grow at 24.6% annually as star labelling, tightened loss norms and loss-linked scheme disbursement reshape utility specifications.
- The delivery gap remains wide, with roughly 5 million transformers sanctioned under the distribution scheme against about 0.44 million installed by 2024, structurally expanding the India distribution transformer market across new supply, replacement, and monitoring categories.
- Rising investment by manufacturers such as Voltamp Transformers, Transformers and Rectifiers, Bharat Bijlee, CG Power and Shilchar Technologies in winding capacity, core sourcing and testing is strengthening domestic supply and supporting the India distribution transformer market forecast 2032.
Key Drivers of the India Distribution Transformer Market
RDSS Outlay of INR 3.03 Lakh Crore Driving Procurement, Feeder Works and Network Modernization
Growth in the India distribution transformer market is being driven by the largest distribution upgrade programme the country has run. The Revamped Distribution Sector Scheme carries a total outlay of INR 3,03,758 crore across FY2022 to FY2026, with central support of INR 97,631 crore, and targets aggregate technical and commercial losses of 15% against 16.42% in FY2022. Projects worth INR 2.83 lakh crore have been sanctioned, of which INR 1.53 lakh crore covers loss reduction infrastructure including conductor replacement, substation and transformer augmentation, new substations and feeder segregation, and INR 1.31 lakh crore covers smart metering. Losses had fallen to 15.04% by FY2025. Because disbursement is tied to measured loss reduction rather than to spend alone, utilities have a direct incentive to replace overloaded and inefficient units, which sustains order flow across the Indian transformer market.
High Failure Rates, Ageing Fleet and Chronic Overloading Forcing Accelerated Replacement
The India distribution transformer market is benefiting from a replacement cycle that runs well ahead of design life. India operates an installed base of roughly 1.74 crore distribution transformers, many of them on rural and agricultural feeders where loading is unbalanced, protection is weak and supply is unmetered at the transformer. Units fail through overloading, harmonic stress from pumps and inverters, oil degradation and lightning, and a failed transformer is usually replaced in haste rather than upgraded to a better specification. Replacement and failure restoration already accounts for 21% of application demand. Because the scheme ties funding to loss performance, utilities are beginning to replace ahead of failure rather than after it, using loading data to size the replacement correctly. That behavioural change is worth more to manufacturers than the failure volume itself across the India distribution transformer market.
Rooftop Solar, EV Charging and Load Growth Requiring New and Higher-Rated Units on the Network
New load types remain a major catalyst for the India distribution transformer market. Rooftop solar pushes power back up the feeder, which changes voltage profiles and requires units specified for bidirectional flow rather than one-way supply, and rooftop solar with distributed generation already accounts for 8% of application demand. Vehicle charging adds concentrated draw at specific points, with the national charging programme targeting 72,000 public chargers, each of which needs a distribution-level transformer behind it. Air conditioning, agricultural pump sets and small industry continue to lift underlying consumption, so feeders sized decades ago now run beyond comfortable loading. Solar inverter duty and special purpose designs together take 8% of the product mix and command better realisation than standard units, giving manufacturers a route out of pure price competition in the Indian grid modernization market.
India Distribution Transformer Market Challenges
Order Backlog and Delivery Shortfall Against Sanctioned Volume Constraining Actual Installation
The India distribution transformer market continues to face a gap between sanction and installation that has become the defining feature of the shortage. Roughly 5 million transformers were sanctioned under the distribution scheme, yet only about 0.44 million had been installed by 2024, a delivery rate that leaves a backlog large enough to sustain orders through at least 2027. Smart metering shows the same pattern, with 20.33 crore meters sanctioned covering 19.79 crore consumers, 2.11 lakh feeders and 52.53 lakh distribution transformers, against 7.24 crore installed nationally as of 30 June 2026, of which 5.73 crore sat under the scheme. Tendering delays, contracting disputes, execution capacity at state level and consumer engagement are the cited causes. Until execution matches sanction, the shortage will persist across the Indian transformer market.
CRGO and Amorphous Core Import Dependence Raising Input Cost for Smaller Manufacturers
The India distribution transformer market faces structural complexity in sourcing core material. Grain oriented electrical steel is largely imported, and amorphous alloy ribbon more so, leaving delivered cost exposed to freight, duty, certification cycles and exchange rate movement. Tightened efficiency norms make this worse rather than better, because lower loss limits demand higher grade material per unit built. Smaller manufacturers, who supply a large share of rural utility demand, lack the purchasing power to hold buffer inventory or to contract mills on annual volume, so they buy at spot prices and bid at fixed tender rates. Copper and aluminium winding conductor adds a second commodity exposure. Backward integration, long-term material contracts and design optimisation are the recognised responses, but each requires working capital that much of the Indian supply base does not hold.
Tightened IS 1180 Loss Limits and Price-Led Tendering Squeezing Manufacturer Margins
The India distribution transformer market faces practical constraints where regulation meets procurement practice. The Bureau of Indian Standards revised IS 1180 Part 1 in 2024, tightening permissible total losses for three-phase distribution transformers, with enforcement from January 2025, and the Bureau of Energy Efficiency has layered star rating categories on top. Meeting those limits requires better core material, redesigned laminations and more conductor, all of which raise cost. Utility tenders, however, are still frequently decided on lowest quoted price with limited weight on lifecycle losses, so the manufacturer that invests in compliance competes against one that quotes to the minimum. Payment delays from financially stressed utilities compound the squeeze. Aligning tender evaluation with total cost of ownership is the recognised fix across the Indian grid modernization market.
India Distribution Transformer Market Trends
Transformer Metering Turning an Unmonitored Fleet Into a Measured Asset Base in India
The India distribution transformer market is being reshaped by visibility that did not previously exist. Smart system metering sanctioned under the distribution scheme covers 52.53 lakh distribution transformers alongside 2.11 lakh feeders and 19.79 crore consumer connections, which allows energy accounting at the transformer rather than at the substation. That changes three things at once: utilities can locate theft and technical loss to a specific unit, size replacements against measured loading instead of nameplate assumptions, and detect impending failure from temperature and load trends. Manufacturers gain a service opportunity in sensors, diagnostics and maintenance contracts layered on top of hardware sales. As of 30 June 2026, 7.24 crore smart meters covering consumer, transformer and feeder points had been installed, reinforcing the India distribution transformer market forecast 2032.
Efficiency Regulation Pulling the Mix Toward Amorphous Cores and Higher Star Ratings
A visible shift in specification is reshaping the India distribution transformer market. Amorphous core units deliver no-load losses far below conventional grain oriented steel designs of the same rating, a gap that matters most on rural feeders where transformers sit energised for long periods at light load. They hold 11% of the product mix today and are growing quickly as star labelling spreads. By efficiency class, BEE 3-star units carry 34% of value, units meeting the IS 1180 Level 2 threshold 26%, BEE 4-star 21% and BEE 5-star 13%, with legacy non-rated stock down to 6%. State utilities in several states are specifying amorphous cores for urban and rural replacement where standby efficiency outweighs peak capacity. The shift raises purchase price but shortens payback under loss reduction targets, reinforcing the India distribution transformer market forecast 2032.
New Load Types Reshaping Specification, Ratings and Where Units Are Placed
A wave of demand-side change is reshaping product design across the India distribution transformer market. Rooftop solar reverses power flow on feeders originally designed for one-way supply, which pushes utilities toward units rated for bidirectional operation and tighter voltage regulation. Vehicle charging concentrates load at highway and depot locations, with the national programme targeting 72,000 public chargers, each requiring dedicated distribution capacity. Urban congestion is pulling demand toward compact package substation units, which hold 6% of the mix, because they fit where a conventional yard cannot. By rating, 26 kVA to 100 kVA units take 31% of value and 101 kVA to 500 kVA a further 27%, but the growth is fastest in the higher brackets as connected load rises. Combined with scheme-funded feeder segregation, these developments are reinforcing the Indian grid modernization market through 2032.
India Distribution Transformer Market Share by Segment
By End-User: State Distribution Utilities & Discoms Segment Dominates the Market
The state distribution utilities segment dominates the India distribution transformer market, accounting for an estimated 61% of value, driven by scheme-funded procurement, the obligation to serve rural and agricultural feeders, and replacement of a fleet of roughly 1.74 crore units. Oil-immersed designs in the 26 kVA to 100 kVA bracket are the dominant configuration within this segment. Industrial, commercial and institutional consumers contribute another 18% of demand, buying directly for captive substations and connected load augmentation. Private distribution licensees and franchisees account for 12%, concentrated in urban circuits where loss reduction economics are sharpest. Renewable developers and vehicle charging operators make up 9%, the fastest growing buyer class. In 2025, procurement across Uttar Pradesh, Bihar, Rajasthan and Madhya Pradesh reinforced segment dominance in the India distribution transformer market.
By Product Type: Oil-Immersed Units Lead While Amorphous Core and Inverter Duty Grow Fastest
Oil-immersed units lead the India distribution transformer market product mix, accounting for approximately 52% of value, driven by lower first cost, field repairability and dominance on rural and semi-urban feeders. Pole-mounted designs contribute another 19%, amorphous core units 11%, special purpose and solar inverter duty transformers 8%, compact and package substation units 6%, and dry type and cast resin designs the remaining 4%. Amorphous core and BEE 5-star rated units are the fastest growing categories within the India distribution transformer market, expanding at 24.6% annually. Rural feeder and agricultural supply takes 29% of application demand, urban distribution 24% and replacement 21%. Leading manufacturers including Voltamp Transformers, Transformers and Rectifiers, Bharat Bijlee, CG Power and Shilchar Technologies have aligned capacity to this mix across the Indian network.
India Distribution Transformer Market by Region
Regional analysis of the India distribution transformer market shows that North India and West India collectively account for approximately 54% of value, driven by Uttar Pradesh, Rajasthan, Haryana and Punjab in the north, where high aggregate technical and commercial losses concentrate scheme funding, and by Maharashtra and Gujarat in the west, which combine urban augmentation with a dense manufacturing base. South India contributes around 23% of value, led by Tamil Nadu, Karnataka, Telangana and Andhra Pradesh, supported by industrial connections and rooftop solar. East India accounts for 14%, supported by Bihar, West Bengal, Odisha and Jharkhand, where rural electrification and feeder segregation dominate spending, while Central India accounts for 9%, led by Madhya Pradesh and Chhattisgarh. In 2025, tendering across Uttar Pradesh and Bihar reinforced these clusters across the India distribution transformer market.
Recent Developments in the India Distribution Transformer Market
- The India distribution transformer market recorded strong momentum in scheme execution during 2025 and 2026. Projects worth INR 2.83 lakh crore were sanctioned under the Revamped Distribution Sector Scheme against a total outlay of INR 3,03,758 crore, with INR 1.53 lakh crore allocated to loss reduction infrastructure and INR 1.31 lakh crore to smart metering. Aggregate technical and commercial losses fell to 15.04% by FY2025 from 16.42% in FY2022. Loss reduction works cover conductor replacement, substation and transformer augmentation, new substations, feeder segregation and deployment of supervisory control and distribution management systems.
- Metering progress reshaped visibility across the India distribution transformer market. Sanctioned smart metering covers 20.33 crore meters spanning 19.79 crore consumers, 2.11 lakh feeders and 52.53 lakh distribution transformers. As of 30 June 2026, 7.24 crore smart meters covering consumer, transformer and feeder points had been installed nationally, of which 5.73 crore fell under the scheme and the balance under other programmes including the National Smart Grid Mission. The gap between sanction and installation has shifted the policy conversation from deployment toward data quality and measurable loss outcomes.
- Standards and supply positions continued to evolve in the India distribution transformer market. The Bureau of Indian Standards revised IS 1180 Part 1 in 2024, tightening permissible total losses for three-phase units with enforcement from January 2025, prompting redesign of core laminations and conductor geometry. Manufacturers supplying utilities in Madhya Pradesh and Uttar Pradesh accelerated prototype testing to meet the window, while Voltamp Transformers, Transformers and Rectifiers, Bharat Bijlee, Shilchar Technologies and Atlanta Electricals expanded capacity, strengthening long-term positioning in the India distribution transformer market forecast 2032.
Key Companies in the India Distribution Transformer Market
- Voltamp Transformers Limited
- Transformers and Rectifiers (India) Limited
- Bharat Bijlee Limited
- CG Power and Industrial Solutions Limited
- Bharat Heavy Electricals Limited (BHEL)
- Kirloskar Electric Company Limited
- Indo Tech Transformers Limited
- Shilchar Technologies Limited
- Danish Power Limited
- Atlanta Electricals Limited
- Servokon Systems Limited
- Schneider Electric India Private Limited
- Hitachi Energy India Limited
| By Product Type | By Power Rating | By Efficiency Class | By Application | By End-User |
| Oil-Immersed Pole-Mounted Amorphous Core Inverter Duty Package Substation Dry Type | Up to 25 kVA 26-100 kVA 101-500 kVA 501-1,000 kVA 1,001-2,500 kVA Above 2,500 kVA Others | BEE 5-Star BEE 4-Star BEE 3-Star IS 1180 Level 2 Legacy & Non-Rated | Rural Feeder Urban Network Replacement Industrial & Commercial Rooftop Solar EV Charging | State Discoms Industrial & Commercial Private Licensees Renewable & EV Operators |
Report Scope
In this report, the India Distribution Transformer Shortage & Grid Modernization Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Product Type
- Oil-Immersed Distribution Transformers
- Pole-Mounted Distribution Transformers
- Amorphous Core Distribution Transformers
- Special Purpose & Solar Inverter Duty Transformers
- Compact & Package Substation Units
- Dry Type & Cast Resin Distribution Transformers
- By Power Rating
- Up to 25 kVA
- 26 kVA to 100 kVA
- 101 kVA to 500 kVA
- 501 kVA to 1,000 kVA
- 1,001 kVA to 2,500 kVA
- Above 2,500 kVA
- Others
- By Efficiency Class
- BEE 5-Star
- BEE 4-Star
- BEE 3-Star
- IS 1180 Level 2 Compliant
- Legacy & Non-Rated Units
- By Application
- Rural Feeder & Agricultural Supply
- Urban Distribution Network
- Replacement & Failure Restoration
- Industrial & Commercial Connections
- Rooftop Solar & Distributed Generation
- EV Charging Infrastructure
- By End-User
- State Distribution Utilities & Discoms
- Industrial, Commercial & Institutional Consumers
- Private Distribution Licensees & Franchisees
- Renewable Developers & EV Charging Operators
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Distribution Transformer Shortage & Grid Modernization Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging transformer manufacturers, specialty core and component suppliers, regional MSME assemblers, or niche monitoring and retrofit service providers.
For a free sample of the India Distribution Transformer Shortage & Grid Modernization Market report, customised insights or delivery timelines, submit your query here
India Distribution Transformer Shortage & Grid Modernization Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Product Type
- By Power Rating
- By Efficiency Class
- By Application
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Distribution Transformer Market
- India Distribution Transformer Market Insights
- Market Dynamics
- Growth Drivers
- RDSS outlay of INR 3.03 lakh crore driving India distribution transformer market procurement and upgrades.
- High failure rates, ageing fleet and chronic overloading forcing accelerated replacement across India.
- Rooftop solar, EV charging and load growth requiring new and higher-rated distribution transformer units.
- Restraints
- Order backlog and delivery shortfall, with only a small fraction of sanctioned transformers installed.
- CRGO and amorphous core import dependence raising input cost for smaller Indian manufacturers.
- Discom payment delays and fragmented tendering squeezing MSME manufacturer working capital in India.
- Opportunities
- Amorphous core and BEE 5-star transformer units cutting no-load losses by a wide margin across India.
- DT metering across 52.53 lakh transformers opening a digital retrofit and analytics market in India.
- Solar inverter duty and EV charging transformers creating premium niches beyond standard utility supply.
- Challenges
- Measuring and reducing failure rates without reliable transformer-level loading and energy accounting data.
- Meeting tightened IS 1180 loss limits while holding price in fiercely competitive utility tenders.
- Matching supply to bunched scheme tendering that arrives in waves rather than as steady annual demand.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- CRGO & Amorphous Core Material Suppliers (imported electrical steel, amorphous alloy ribbon)
- Copper & Aluminium Winding Conductor Manufacturers (strip, foil and round conductor)
- Insulation, Pressboard & Transformer Oil Suppliers (kraft paper, mineral and ester fluids)
- Bushing, Tap Switch & Tank Fabrication Units (radiators, conservators, fittings)
- Distribution Transformer Manufacturers & MSME Assemblers (Voltamp, Bharat Bijlee, Shilchar)
- Testing, Certification & Star Labelling Agencies (CPRI, ERDA, BIS and BEE compliance testing)
- Smart Meter, DT Monitoring & Communication Providers (DT metering, head-end and analytics)
- Distribution Automation & SCADA-DMS Integrators (feeder automation, outage management systems)
- Distribution Utilities, Franchisees & Funding Agencies (state discoms, PFC, REC, nodal bodies)
- End-Users (rural and urban consumers, industry, rooftop solar owners, EV charging operators)
- India Distribution Transformer Market: Regulatory Framework
- India Distribution Transformer Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (Thousand Units)
- Market Share & Forecast
- By Product Type
- Oil-Immersed Distribution Transformers
- Pole-Mounted Distribution Transformers
- Amorphous Core Distribution Transformers
- Special Purpose & Solar Inverter Duty Transformers
- Compact & Package Substation Units
- Dry Type & Cast Resin Distribution Transformers
- By Power Rating
- Up to 25 kVA
- 26 kVA to 100 kVA
- 101 kVA to 500 kVA
- 501 kVA to 1,000 kVA
- 1,001 kVA to 2,500 kVA
- Above 2,500 kVA
- Others
- By Efficiency Class
- BEE 5-Star
- BEE 4-Star
- BEE 3-Star
- IS 1180 Level 2 Compliant
- Legacy & Non-Rated Units
- By Application
- Rural Feeder & Agricultural Supply
- Urban Distribution Network
- Replacement & Failure Restoration
- Industrial & Commercial Connections
- Rooftop Solar & Distributed Generation
- EV Charging Infrastructure
- By End-User
- State Distribution Utilities & Discoms
- Industrial, Commercial & Institutional Consumers
- Private Distribution Licensees & Franchisees
- Renewable Developers & EV Charging Operators
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Distribution Transformer Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Voltamp Transformers Limited
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Transformers and Rectifiers (India) Limited
- Bharat Bijlee Limited
- CG Power and Industrial Solutions Limited
- Bharat Heavy Electricals Limited (BHEL)
- Kirloskar Electric Company Limited
- Indo Tech Transformers Limited
- Shilchar Technologies Limited
- Danish Power Limited
- Atlanta Electricals Limited
- Servokon Systems Limited
- Schneider Electric India Private Limited
- Hitachi Energy India Limited
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India distribution transformer market and what is its growth forecast?
Ans: The India distribution transformer market is valued at USD 2,240 million in 2025 and is projected to reach USD 5,120 million by 2032, growing at a CAGR of 12.5% on delivered hardware and modernization spending.
2. Which segments are driving demand in the India distribution transformer market?
Ans: Oil-immersed units lead with 52% of value, while amorphous core and BEE 5-star rated designs are the fastest growing segments, supported by tightened loss norms and loss-linked scheme disbursement across states.
3. What are the key drivers of growth in the India distribution transformer market?
Ans: Key drivers include the INR 3.03 lakh crore distribution scheme, a fleet of roughly 1.74 crore ageing units, high failure rates on overloaded feeders, rooftop solar growth, and vehicle charging network build-out.
4. Which regions are driving growth in the India distribution transformer market?
Ans: North India and West India lead with around 54% of value, driven by Uttar Pradesh, Rajasthan, Maharashtra and Gujarat. South India follows at 23%, led by Tamil Nadu, Karnataka and Telangana.
5. What are the latest trends in the India distribution transformer market?
Ans: Latest trends include transformer-level metering across 52.53 lakh units, the shift toward amorphous cores and higher star ratings, and specification changes driven by rooftop solar and vehicle charging load on rural feeders.