

India Key Starting Materials and Drug Intermediates Market, 2032
- Chemicals & Advanced Materials, Pharmaceuticals & Life Sciences, Specialty Chemicals
- Nov 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s key starting materials and drug intermediates market is witnessing strong structural growth, driven by the PLI scheme for bulk drugs, new bulk drug parks, China+1 sourcing by global pharma buyers, rising API and generic formulation exports, fast growth in CDMO and custom synthesis contracts, and rising interest from domestic API majors investing in backward integration, fermentation capacity, and green chemistry platforms.
| Study Duration | 2021-2032 |
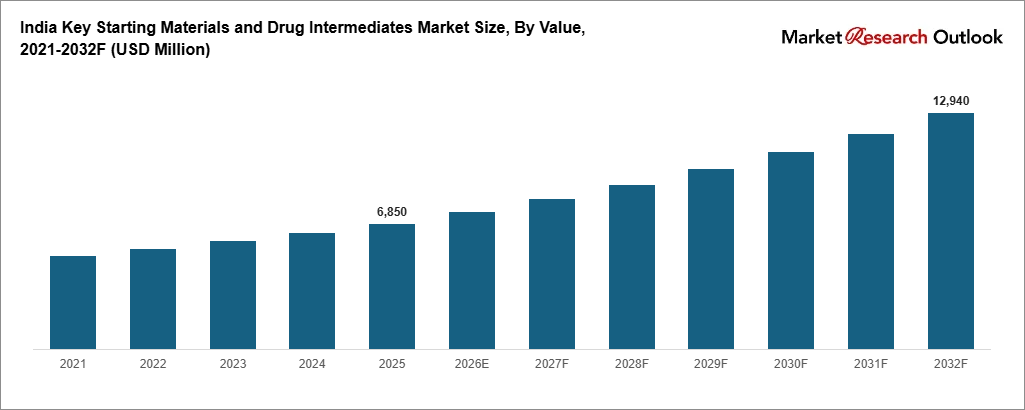
| Market Size (2025) | USD 6,850 Million |
| CAGR (2026-2032) | 9.5% |
| Leading Segment | Key Starting Materials (Anti-Infectives) |
| Fastest Growing Segment | Chiral & Fermentation-Based Intermediates |
| Market Size (2032) | USD 12,940 Million |
Market Overview: India Key Starting Materials and Drug Intermediates Market
The India key starting materials and drug intermediates market size is expanding quickly, driven by the PLI scheme for bulk drugs, three bulk drug parks, rising API and formulation exports, China+1 sourcing by global pharma companies, growing CDMO demand, and large capacity additions by domestic API majors. Valued at USD 6,850 million in 2025 and projected to reach USD 12,940 million by 2032, growing at a CAGR of 9.5%, the India KSM and drug intermediates market growth is being fuelled by strong demand from API manufacturers, generic drug makers, and contract developers serving the US, EU, and emerging markets. Key starting materials lead consumption, while chiral and fermentation-based drug intermediates are the fastest growing category. Tighter regulatory audits, supply security concerns after the pandemic, and buyer demand for traceable supply chains are reshaping sourcing decisions. As domestic majors including Divi’s Laboratories, Laurus Labs, Aarti Pharmalabs, Hikal, and Neuland Laboratories expand integrated capacity, and API makers such as Aurobindo Pharma, Granules India, IOL Chemicals, and Aarti Drugs commission PLI-linked plants, the India key starting materials and drug intermediates market is evolving into a self-reliant, innovation-driven, and export-ready ecosystem with strong long-term growth potential.
Key Report Takeaways: India Key Starting Materials and Drug Intermediates Market
- The India key starting materials and drug intermediates market size is projected to grow from USD 6,850 million in 2025 to USD 12,940 million by 2032, registering a strong CAGR of 9.5%, driven by PLI-backed greenfield capacity, China+1 sourcing, and the shift toward domestic supply of critical KSMs.
- Key starting materials dominate the India KSM and drug intermediates market, accounting for about 46% of total value in 2025, driven by high-volume demand from anti-infective, cardiovascular, and pain management APIs, deep presence of players such as Divi’s, Aarti Pharmalabs, and Vinati Organics, and rising captive use by API majors.
- Chiral and fermentation-based drug intermediates are the fastest growing segments in the India key starting materials and drug intermediates market, expected to grow at 13% to 16% annually as antibiotic import substitution, complex generics, and specialty APIs reshape sourcing strategies.
- Rapid scaling of PLI capacity, with 48 greenfield projects approved and 38 projects covering 28 products commissioned by December 2025, is adding close to 56,800 metric tonnes of annual capacity across the India key starting materials and drug intermediates market.
- Rising investments by domestic players such as Divi’s Laboratories, Laurus Labs, Hikal, Neuland Laboratories, and Sai Life Sciences in custom synthesis, continuous flow chemistry, and green manufacturing are strengthening local supply and supporting the India key starting materials and drug intermediates market forecast 2032.
Key Market Drivers: India Key Starting Materials and Drug Intermediates Market
PLI Scheme Incentives and Bulk Drug Parks Expanding Domestic KSM and Drug Intermediate Capacity Across India
Growth in the India key starting materials and drug intermediates market is being driven by the INR 6,940 crore PLI scheme for bulk drugs and the INR 3,000 crore scheme for bulk drug parks. The PLI scheme covers 41 eligible products across four target segments, including fermentation-based KSMs and key chemical synthesis based drug intermediates. Actual investment under the scheme reached about INR 4,814 crore against a commitment of INR 4,330 crore, and 38 projects were commissioned by December 2025. Each of the three bulk drug parks at Jambusar in Gujarat, Una in Himachal Pradesh, and Nakkapalli in Andhra Pradesh can receive up to INR 1,000 crore of central support for shared utilities, effluent treatment, and solvent recovery. These parks are expected to cut production costs for KSM makers by 15% to 20% once operational. India’s per-unit cost gap with China for many drug intermediates still sits at 10% to 25%, which shows how much room remains for scale and infrastructure gains across the market.
Import Substitution and China+1 Sourcing Strategies Fuelling Demand for Locally Produced Key Starting Materials
The India key starting materials and drug intermediates market is benefiting from a clear move away from single-country supply. According to NITI Aayog, India imports around USD 7.4 billion of APIs and related inputs each year, with China holding a 65% to 86% share across major categories. Nitrogen heterocyclic compounds alone account for about USD 2.3 billion of imports and antibiotics for about USD 1.9 billion. Global pharma buyers in the US, EU, and Japan now ask suppliers to show at least one non-China source for critical key starting materials, which has pushed Indian API makers to qualify domestic vendors. Average qualification cycles for a new KSM vendor run 9 to 15 months, but once approved, supply contracts often last five years or more. Tighter USFDA and EDQM audits on traceability have further strengthened demand for compliant domestic supply across the market.
Rising API, Generic Formulation, and CDMO Exports Strengthening Drug Intermediate Consumption
Strong growth in pharma exports is a major catalyst for the India key starting materials and drug intermediates market, with India’s pharmaceutical exports crossing USD 30 billion in FY2025. Every tonne of API produced needs between 1.5 and 4 tonnes of key starting materials and drug intermediates, depending on the number of synthesis steps. India’s CDMO and CRAMS revenue pool crossed an estimated USD 3.6 billion in 2025, with players such as Sai Life Sciences, Neuland Laboratories, Laurus Labs, Divi’s Laboratories, and Hikal winning multi-year contracts from global innovators. Patent expiries worth more than USD 200 billion in global drug sales through 2030 will open fresh generic API demand, and each new API needs its own validated chain of drug intermediates. Combined with steady domestic formulation growth, these trends are expanding India key starting materials and drug intermediates market demand across all major end-user categories through 2032.
Key Market Challenges: India Key Starting Materials and Drug Intermediates Market
High Import Dependence on China for Critical KSMs and Fermentation-Based Intermediates
The India key starting materials and drug intermediates market continues to face deep import dependence, especially for fermentation-based inputs. China supplies about 86% of India’s antibiotic imports and more than 76% of nitrogen heterocyclic compound imports. India has near-total dependence on China for roughly 25 to 35 pharma inputs, including antibiotic building blocks, vitamin intermediates, and fine chemicals. While PLI plants for Penicillin G, 6-APA, and clavulanic acid have started production, large-scale fermentation requires long build times, high energy use, and skilled microbiology teams. Smaller API makers still buy imported intermediates because they are cheaper and available on short notice, which slows the pace of import substitution across the industry.
Stringent Environmental Compliance, Effluent Treatment Costs, and Slow Clearances Delaying New Capacity
The India key starting materials and drug intermediates market faces structural complexity from strict environmental rules, zero liquid discharge norms, and long approval timelines. Chemical synthesis of drug intermediates often generates 20 to 100 kilograms of waste for every kilogram of product, which makes effluent treatment a major cost. Effluent and solvent recovery systems add 6% to 10% to production costs for many merchant producers. Environmental clearances for new KSM units can take 12 to 18 months, and pollution control board actions in clusters such as Vapi, Ankleshwar, and Patancheru have led to periodic closures. Differences in state rules on land, water, and hazardous waste create extra complexity for players such as Aarti Pharmalabs, Hikal, Vinati Organics, and Jubilant Ingrevia operating across states. Bulk drug parks with shared treatment plants will help, but infrastructure gaps remain a near-term challenge for the industry.
Volatility in Petrochemical Feedstock Prices and Chinese Price Undercutting Squeezing Domestic Margins
The India key starting materials and drug intermediates market faces practical constraints around feedstock price swings, energy costs, and aggressive pricing from Chinese suppliers. Prices of benzene, toluene, methanol, and acetic acid moved by 10% to 18% between 2022 and 2025, while solvent and utility costs also rose. Chinese producers with integrated feedstock and large-scale plants often price common drug intermediates 15% to 25% below Indian offers, especially during periods of excess supply. Average gross margins for merchant KSM makers in India range between 18% and 26%, and sudden price drops can cut the return on new projects by 4% to 8%. Anti-dumping duties and minimum import price proposals offer some relief, but uneven enforcement remains a barrier across the industry.
Key Market Trends: India Key Starting Materials and Drug Intermediates Market
Shift Toward Green Chemistry, Continuous Flow Manufacturing, and Biocatalysis in India
The India key starting materials and drug intermediates market is going through a clear technology shift toward green chemistry, continuous flow processing, and enzyme-based routes, with these methods expected to account for over 20% of new intermediate capacity added by 2028. Continuous flow chemistry can cut solvent use by 30% to 50% and reduce batch cycle times by up to 40%, while biocatalysis improves chiral purity and lowers hazardous waste. Leading domestic players including Divi’s Laboratories, Laurus Labs, Dr. Reddy’s, Neuland Laboratories, and Hikal have expanded flow chemistry and enzyme platforms through 2024 and 2025. Solvent recovery rates of 85% to 95% are becoming a standard ask from global customers focused on carbon and ESG targets. This process transition is reinforcing the India key starting materials and drug intermediates market forecast 2032 across both merchant and captive production.
Rise of CDMO and Custom Synthesis Partnerships in the India Key Starting Materials and Drug Intermediates Market
A clear shift toward CDMO, custom synthesis, and long-term supply partnerships is reshaping the India key starting materials and drug intermediates market, particularly for advanced and chiral intermediates. Global innovators increasingly hand over early and late-stage intermediate work to Indian partners, with contract values typically 20% to 35% below comparable Western suppliers. Players such as Sai Life Sciences, Neuland Laboratories, Laurus Labs, and Divi’s Laboratories now run dedicated custom synthesis blocks for single customers. Contract research and pilot-scale work is also moving to India, which lets suppliers lock in commercial volumes as molecules progress through clinical trials. By 2025, custom synthesis and CDMO work accounts for an estimated 22% of drug intermediate revenue in India, up from about 14% in 2020, with innovator demand for regulatory-grade intermediates rising each year.
Backward Integration and Capacity Expansion by Domestic API Majors
A wave of backward integration and capacity expansion is reshaping the India KSM and drug intermediates market supply base. Combined India-focused capital expenditure announcements in KSMs, drug intermediates, and related API capacity exceeded USD 2.5 billion across 2023 to 2025. Aurobindo Pharma, through Lyfius Pharma, commissioned a large fermentation plant for Penicillin G at Kakinada. Granules India and IOL Chemicals deepened integration in paracetamol and ibuprofen intermediates, while Aarti Drugs, Vinati Organics, and Jubilant Ingrevia expanded key chemical intermediate lines in Gujarat and Maharashtra. Divi’s Laboratories scaled its Kakinada greenfield site and Laurus Labs added synthesis capacity in Andhra Pradesh. PLI incentives, bulk drug park utilities, and steady API demand have structurally favoured organized domestic supply, reinforcing the India key starting materials and drug intermediates market forecast 2032 across the entire value chain.
Segmental Insights: India Key Starting Materials and Drug Intermediates Market
By End-User: API Manufacturers Segment Dominates the India Key Starting Materials and Drug Intermediates Market
The API manufacturers end-user segment dominates the India key starting materials and drug intermediates market, accounting for an estimated 52% to 56% of total value, driven by high-volume generic API output, rising exports, and PLI-linked backward integration. Anti-infective, cardiovascular, and pain management APIs are the main demand pools within this segment, with chemical synthesis routes covering over 70% of purchases. Formulation companies contribute another 19% to 22% of demand, mainly through integrated players that buy drug intermediates for in-house API steps. CDMOs and CROs account for 17% to 20%, led by custom synthesis for global innovators, while research and academic institutes hold 3% to 5%. In 2025, leading players including Aurobindo Pharma, Granules India, Laurus Labs, Divi’s Laboratories, and Dr. Reddy’s scaled captive and merchant intermediate supply, reinforcing segment leadership in the market.
By Type: Key Starting Materials Lead While Chiral and Fermentation-Based Intermediates Grow Fastest
Key starting materials lead the India key starting materials and drug intermediates market, accounting for approximately 46% of total value, driven by large-volume use, deep supplier networks, and improving cost economics. Advanced drug intermediates contribute another 21% to 24%, mainly for multi-step APIs in cardiovascular, anti-diabetic, and CNS therapies. Chiral and fermentation-based intermediates are the fastest growing categories, expanding at 13% to 16% annually, driven by antibiotic import substitution, complex generics, and the PLI focus on Penicillin G, 6-APA, and clavulanic acid. Heterocyclic intermediates and others together account for 12% to 15% of the market, with heterocyclic demand set to rise through 2032 in oncology and CNS drugs. Leading domestic manufacturers including Divi’s Laboratories, Aarti Pharmalabs, Hikal, Vinati Organics, and Jubilant Ingrevia have aligned portfolios to this product mix, driving higher-value growth across the market.
Regional Insights: India Key Starting Materials and Drug Intermediates Market
Regional analysis of the India key starting materials and drug intermediates market shows that West India and South India together account for approximately 72% to 76% of total value, driven by Gujarat (Ankleshwar, Vapi, Dahej, and Bharuch chemical belts), Maharashtra (Tarapur and MIDC clusters), Telangana (Hyderabad pharma corridor), and Andhra Pradesh (Visakhapatnam and Kakinada), supported by mature chemical infrastructure and skilled process chemistry talent. North India contributes around 14% to 17% of demand, led by Himachal Pradesh (Baddi), Punjab, and Uttar Pradesh, supported by formulation hubs and the upcoming Una bulk drug park. Central and East India together account for 8% to 11% of demand, supported by Madhya Pradesh, West Bengal, and Odisha, where new chemical parks are coming up. In 2025, capacity additions by Aarti Pharmalabs and Vinati Organics in Gujarat, Divi’s and Laurus Labs in Andhra Pradesh, Neuland and Dr. Reddy’s in Telangana, and Aurobindo’s Lyfius Pharma in Kakinada reinforced regional supply hubs across the country.
Pharma data: see the India Pharma Plant Projects Tracker for new API, KSM and intermediates plants, and the India Pharma Exports Tracker for monthly drug exports, including bulk drugs. The India Drug Market Entry Tracker shows patent expiry, Indian makers and price control for 22 medicines.
Recent Developments: India Key Starting Materials and Drug Intermediates Market
- The India key starting materials and drug intermediates market saw strong momentum in project launches and capacity progress during 2024 and 2025. Under the PLI scheme for bulk drugs, 38 projects covering 28 notified products had been commissioned by December 2025, creating close to 56,800 metric tonnes of annual capacity and nearly 4,900 jobs. The Department of Pharmaceuticals opened fresh application rounds in 2025 for unsubscribed products, including fermentation-based KSMs such as neomycin, gentamycin, and tetracycline. Domestic production of drug intermediates in India is projected to grow by an average 11% annually through FY27.
- Domestic API majors have deepened India-focused backward integration. In 2024 and 2025, Aurobindo Pharma ramped up its Lyfius Pharma Penicillin G plant at Kakinada, Divi’s Laboratories scaled its Kakinada site, Laurus Labs added synthesis blocks in Andhra Pradesh, Granules India and IOL Chemicals strengthened paracetamol and ibuprofen intermediate chains, and Aarti Pharmalabs expanded intermediate lines in Gujarat. These developments are strengthening domestic supply and supporting the India key starting materials and drug intermediates market forecast 2032.
- CDMO and custom synthesis momentum has gained strong traction in the India KSM and drug intermediates market. In 2025, leading players including Sai Life Sciences, Neuland Laboratories, Hikal, Laurus Labs, and Divi’s Laboratories expanded contract capacity for global innovators. Long-term supply deals between Indian intermediate makers and US and European pharma companies are positioning India as one of the fastest scaling drug intermediate hubs globally, strengthening long-term competitive positioning in the India key starting materials and drug intermediates market forecast 2032.
Key Market Players: India Key Starting Materials and Drug Intermediates Market
- Divi’s Laboratories Limited
- Laurus Labs Limited
- Aarti Pharmalabs Limited
- Hikal Limited
- Neuland Laboratories Limited
- Aurobindo Pharma Limited (Lyfius Pharma Pvt. Ltd.)
- Granules India Limited
- Jubilant Ingrevia Limited
- Vinati Organics Limited
- IOL Chemicals and Pharmaceuticals Limited
- Sai Life Sciences Limited
- Aarti Drugs Limited
- Dr. Reddy’s Laboratories Limited
| By Type | By Therapeutic Application | By Synthesis Process | By Sourcing Model | By End-User |
| Key Starting Materials (KSMs) Advanced Drug Intermediates Chiral Intermediates Heterocyclic Intermediates Fermentation-Based Intermediates Others |
Anti-Infectives Cardiovascular Anti-Diabetic Oncology Central Nervous System Pain & Analgesics Others |
Chemical Synthesis (Batch, Multi-Step) Fermentation Biocatalysis & Enzymatic Continuous Flow Chemistry Semi-Synthesis & Extraction |
Captive Production Merchant Manufacturing CDMO & Contract Manufacturing Custom Synthesis & CRAMS PLI-Linked Greenfield Units Imports & Trading |
API Manufacturers Formulation Companies CDMOs & CROs Research & Academic Institutes |
Report Scope
In this report, the India Key Starting Materials and Drug Intermediates Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Type
- Key Starting Materials (KSMs)
- Advanced Drug Intermediates
- Chiral Intermediates
- Heterocyclic Intermediates
- Fermentation-Based Intermediates
- Others
- By Therapeutic Application
- Anti-Infectives
- Cardiovascular
- Anti-Diabetic
- Oncology
- Central Nervous System
- Pain & Analgesics
- Others
- By Synthesis Process
- Chemical Synthesis (Batch, Multi-Step)
- Fermentation
- Biocatalysis & Enzymatic
- Continuous Flow Chemistry
- Semi-Synthesis & Extraction
- By Sourcing Model
- Captive Production
- Merchant Manufacturing
- CDMO & Contract Manufacturing
- Custom Synthesis & CRAMS
- PLI-Linked Greenfield Units
- Imports & Trading
- By End-User
- API Manufacturers
- Formulation Companies
- CDMOs & CROs
- Research & Academic Institutes
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Key Starting Materials and Drug Intermediates Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging domestic KSM producers, specialty fermentation and chiral intermediate makers, regional merchant manufacturers, or niche CDMO and custom synthesis firms.
For a free sample of the India Key Starting Materials and Drug Intermediates Market report, customised insights or delivery timelines, submit your query here
India Key Starting Materials and Drug Intermediates Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Type
- By Therapeutic Application
- By Synthesis Process
- By Sourcing Model
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Key Starting Materials and Drug Intermediates Market
- India Key Starting Materials and Drug Intermediates Market Insights
- Market Dynamics
- Growth Drivers
- PLI scheme incentives and bulk drug parks expanding domestic KSM and drug intermediate capacity across India.
- Import substitution and China+1 sourcing strategies fuelling demand for locally produced key starting materials.
- Rising API, generic formulation, and CDMO exports strengthening drug intermediate consumption.
- Restraints
- High import dependence on China for critical KSMs and fermentation-based intermediates.
- Stringent environmental compliance, effluent treatment costs, and slow clearances delaying new capacity.
- Volatility in petrochemical feedstock prices and Chinese price undercutting squeezing domestic margins.
- Opportunities
- Fermentation-based KSMs such as Penicillin G, 6-APA, and 7-ACA opening large import substitution pools.
- Chiral, high-potency, and complex intermediates supporting next-generation growth in specialty APIs.
- Global innovator outsourcing and China+1 contracts creating large custom synthesis opportunities.
- Challenges
- Intense price competition from large-scale Chinese producers with integrated feedstock supply.
- Limited availability of skilled process chemists and fermentation engineers across smaller clusters.
- Maintaining impurity control, regulatory compliance, and batch consistency at commercial scale.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Raw Materials (benzene, toluene, methanol, acetic acid, ammonia, solvents, fermentation media)
- KSM & Intermediate Manufacturers (Divi’s, Laurus Labs, Aarti Pharmalabs, Hikal, Vinati Organics)
- Specialty Reagent & Catalyst Suppliers (chiral auxiliaries, enzymes, catalysts, high-purity solvents)
- Fermentation & Biocatalysis Producers (Penicillin G, 6-APA, 7-ACA, clavulanic acid)
- Quality Control, R&D & Testing Laboratories (CDSCO, USFDA, EDQM, ICH Q7 GMP standards)
- Distributors, Traders & Importers (B2B chemical distribution networks)
- CDMO & Custom Synthesis Partners (Sai Life Sciences, Neuland, Laurus Labs, Divi’s, Hikal)
- API Manufacturers & Bulk Drug Makers (Aurobindo, Granules, IOL Chemicals, Aarti Drugs, Dr. Reddy’s)
- Formulation & Export Channels (domestic generics, US, EU, and emerging market exports)
- End-Users (API makers, formulation companies, CDMOs, CROs, research institutes)
- India Key Starting Materials and Drug Intermediates Market: Regulatory Framework
- India Key Starting Materials and Drug Intermediates Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (Thousand Metric Tonnes)
- Market Share & Forecast
- By Type
- Key Starting Materials (KSMs)
- Advanced Drug Intermediates
- Chiral Intermediates
- Heterocyclic Intermediates
- Fermentation-Based Intermediates
- Others
- By Therapeutic Application
- Anti-Infectives
- Cardiovascular
- Anti-Diabetic
- Oncology
- Central Nervous System
- Pain & Analgesics
- Others
- By Synthesis Process
- Chemical Synthesis (Batch, Multi-Step)
- Fermentation
- Biocatalysis & Enzymatic
- Continuous Flow Chemistry
- Semi-Synthesis & Extraction
- By Sourcing Model
- Captive Production
- Merchant Manufacturing
- CDMO & Contract Manufacturing
- Custom Synthesis & CRAMS
- PLI-Linked Greenfield Units
- Imports & Trading
- By End-User
- API Manufacturers
- Formulation Companies
- CDMOs & CROs
- Research & Academic Institutes
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Key Starting Materials and Drug Intermediates Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Divi’s Laboratories Limited
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Laurus Labs Limited
- Aarti Pharmalabs Limited
- Hikal Limited
- Neuland Laboratories Limited
- Aurobindo Pharma Limited (Lyfius Pharma Pvt. Ltd.)
- Granules India Limited
- Jubilant Ingrevia Limited
- Vinati Organics Limited
- IOL Chemicals and Pharmaceuticals Limited
- Sai Life Sciences Limited
- Aarti Drugs Limited
- Dr. Reddy’s Laboratories Limited
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India key starting materials and drug intermediates market and what is its growth forecast?
Ans: The India key starting materials and drug intermediates market is valued at USD 6,850 million in 2025 and is projected to reach USD 12,940 million by 2032, growing at a CAGR of 9.5%.
2. Which segments are driving demand in the India key starting materials and drug intermediates market?
Ans: Key starting materials lead with about 46% value share, while chiral and fermentation-based drug intermediates are the fastest growing segments, expanding at 13% to 16% annually.
3. What are the key drivers of growth in the India key starting materials and drug intermediates market?
Ans: Key drivers include the PLI scheme for bulk drugs, bulk drug parks, China+1 sourcing, rising API and formulation exports, and fast growth in CDMO and custom synthesis contracts.
4. Which regions are driving growth in the India key starting materials and drug intermediates market?
Ans: West India and South India lead with 72% to 76% of total value, driven by Gujarat, Maharashtra, Telangana, and Andhra Pradesh pharma and chemical clusters.
5. What are the latest trends in the India key starting materials and drug intermediates market?
Ans: Key trends include green chemistry, continuous flow manufacturing, biocatalysis, CDMO partnerships with global innovators, and backward integration by domestic API majors into critical KSMs.