

India AI Data Center Infrastructure Readiness Market, 2032
- Energy, Power & Storage, Grid & Power Infrastructure
- Oct 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s AI data center infrastructure readiness market is witnessing strong structural growth, driven by installed capacity crossing 1,500 MW in 2025, the IndiaAI Mission and its 38,000 onboarded GPUs, rising rack power densities from GPU clusters, data localisation rules, the Budget 2026-27 tax holiday for foreign cloud providers, and hyperscaler commitments from Google, Microsoft and Amazon that are lifting demand for high-density power, liquid cooling, water management and on-site energy systems.
| Study Duration | 2021-2032 |
| Market Size (2025) | USD 4,260 Million |
| CAGR (2026-2032) | 19.6% |
| Leading Segment | Power Distribution & Backup Infrastructure |
| Fastest Growing Segment | Direct-to-Chip & Immersion Liquid Cooling |
| Market Size (2032) | USD 14,912 Million |
Source:
Market Overview: India AI Data Center Infrastructure Readiness Market
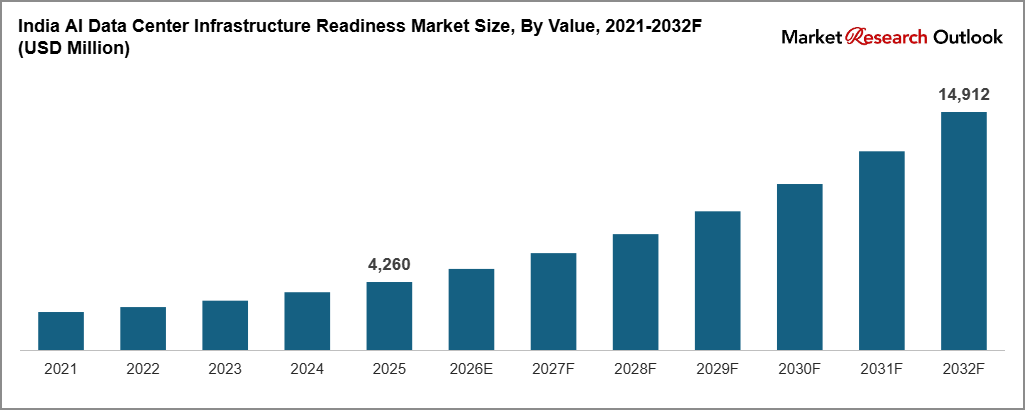
The India AI data center infrastructure readiness market size is witnessing rapid expansion, driven by sovereign AI compute programs, hyperscaler capital commitments, rising rack power densities, data localisation rules and new state data center policies. Valued at USD 4,260 million in 2025 and projected to reach USD 14,912 million by 2032, growing at a CAGR of 19.6%, India’s AI data center infrastructure readiness market growth is being fuelled by GPU cloud providers, hyperscalers, banks, telecom operators and government agencies that need halls able to support 40 kW and above per rack. Power distribution and backup infrastructure leads spending, while direct-to-chip and immersion liquid cooling is emerging as the fastest growing category. India’s installed data center capacity crossed 1,500 MW in 2025, up from 375 MW in 2020, yet most of it was designed for air-cooled racks below 10 kW. As equipment majors including Schneider Electric, Vertiv, ABB, Siemens and Hitachi Energy expand local production, and developers including Yotta, CtrlS, AdaniConneX, NTT and STT GDC India build GPU-ready campuses, the market is evolving into a capacity-led, technology-driven and policy-backed infrastructure category with strong long-term growth potential.
Key Report Takeaways: India AI Data Center Infrastructure Readiness Market
- India’s AI data center infrastructure readiness market size is projected to grow from USD 4,260 million in 2025 to USD 14,912 million by 2032, registering a strong CAGR of 19.6%, driven by sovereign AI compute build-out, hyperscaler investment and the structural shift from air-cooled halls toward liquid-cooled, high-density GPU capacity.
- Power distribution and backup infrastructure dominates spending, accounting for 34.2% of market value in 2025, driven by demand for medium-voltage switchgear, transformers, busways, lithium-ion UPS and battery systems that can carry GPU loads with N+1 and 2N redundancy.
- Direct-to-chip and immersion liquid cooling is the fastest growing category, expected to expand at a CAGR of 31.4% through 2032 as GPU racks above 60 kW move from pilot halls to full production clusters in Mumbai, Chennai, Hyderabad and Visakhapatnam.
- Installed data center capacity in India crossed 1,500 MW in 2025, a fourfold rise from 375 MW in 2020, with Mumbai and Navi Mumbai hosting 790 MW, Chennai 305 MW, Bengaluru 182 MW, Hyderabad 152 MW and Delhi NCR 76 MW.
- Hyperscaler commitments including Google’s USD 15 billion AI hub in Visakhapatnam, Microsoft’s USD 17.5 billion India plan and Amazon’s USD 35 billion investment program, together with the Budget 2026-27 tax holiday to 2047, are strengthening the investment pipeline behind the market forecast 2032.
Key Market Drivers: India AI Data Center Infrastructure Readiness Market
Sovereign AI Compute Build-Out Under the IndiaAI Mission and Hyperscaler Capital Commitments Driving AI-Ready Capacity
Growth in the market is being driven by a national push to host AI compute inside the country. The IndiaAI Mission, approved with an outlay of INR 10,372 crore, had onboarded more than 38,000 GPUs on its common compute portal by March 2026, offering subsidised access to startups, researchers and academic institutions. Each block of 1,000 high-end GPUs needs 1.8 MW of IT power along with matching cooling and backup capacity, which pushes developers to build or retrofit halls for dense loads. Private capital is moving in the same direction. Google has committed USD 15 billion to an AI hub in Visakhapatnam developed with AdaniConneX and Bharti Airtel, Microsoft has announced USD 17.5 billion for cloud and AI infrastructure, and Amazon plans to invest USD 35 billion in India by 2030. India hosts close to 20% of the world’s data yet a small share of global storage capacity, which leaves wide headroom for AI-ready infrastructure across India’s AI data center infrastructure readiness market.
Rising Rack Power Densities From GPU Clusters Forcing Upgrades in Power, Cooling and Electrical Infrastructure
The market is benefiting from a sharp jump in rack power density. Conventional Indian colocation halls were designed for an average of 7 kW per rack, while a single liquid-cooled rack of current generation GPU servers draws about 120 kW. This gap forces upgrades across the full electrical chain, from 66 kV substations and dry-type transformers to busways, intelligent power distribution units and lithium-ion UPS systems with faster recharge cycles. Cooling needs change in step, with air systems giving way to coolant distribution units, cold plates and rear-door heat exchangers. Power infrastructure now accounts for 34.2% of market value and cooling for 24.6%, together forming close to three fifths of total spending. Racks rated at 40 kW and above are expected to account for 46.8% of new AI capacity additions by 2032, compared with 11.5% in 2025, creating strong demand for high-specification equipment across India’s AI data center infrastructure readiness market.
Data Localisation Rules, Budget 2026-27 Tax Holiday and State Data Center Policies Strengthening Investment Readiness
Policy support is a major catalyst for the market. The Reserve Bank of India requires payment system data to be stored only in India, and the Digital Personal Data Protection framework adds further reasons for enterprises to keep sensitive workloads onshore. The Union Budget 2026-27 introduced a tax holiday up to 2047 for notified foreign cloud service providers that serve global customers from MeitY-notified Indian data centers, with a 15% safe harbour margin where the data center is a related entity. States are competing for capacity through dedicated data center policies offering land at concessional rates, stamp duty waivers, dual power feeds and open access to green energy, with Maharashtra and Telangana classifying data centers as essential services. Uttar Pradesh, Tamil Nadu, Andhra Pradesh and Karnataka are building dedicated data center parks. These measures are lowering the cost of capital and shortening approval timelines, structurally expanding India’s AI data center infrastructure readiness market through 2032.
Key Market Challenges: India AI Data Center Infrastructure Readiness Market
Grid Interconnection Delays and Round-the-Clock Renewable Power Availability Constraining AI Campus Timelines
The market continues to face challenges around power availability, as a 100 MW AI campus needs dedicated high-voltage interconnection, redundant feeders and a long-term supply contract before construction can begin. Substation and transmission approvals in Mumbai, Chennai and Hyderabad often take 24 months, longer than the 15 months needed to build the data hall itself. Hyperscalers also want round-the-clock renewable supply to meet global net zero targets, yet solar and wind output is intermittent and storage-backed green power remains costly. Inter-state open access charges and banking rules vary by state, which complicates sourcing for multi-state portfolios. Until transmission build-out and green energy open access reforms catch up, power readiness will remain the main gating factor for project timelines across India’s AI data center infrastructure readiness market.
Water Stress and High Ambient Temperatures Limiting Cooling Efficiency Across Key Data Center Clusters
The market faces structural complexity from water scarcity and heat. India holds 18% of the world’s population but only 4% of its freshwater, and several data center hubs including Chennai, Bengaluru and Hyderabad have faced severe water shortages in recent years. A 100 MW facility using evaporative cooling can consume about 800,000 litres of water a day, and Mumbai recorded a 10% citywide water cut as lake levels fell. Ambient temperatures above 40°C in summer in North and Central India cut free-cooling hours and push chillers to work harder, raising power usage effectiveness. Developers are moving to closed-loop and air-cooled chiller designs, treated sewage water and rainwater harvesting, but these add capital cost and need careful site planning. Water and heat therefore remain a near-term constraint on cooling design choices across India’s AI data center infrastructure readiness market.
High Import Dependence for Critical Electrical and Liquid Cooling Equipment Raising Capital Costs and Lead Times
The market faces practical constraints from import dependence for critical equipment. Power semiconductors, high-capacity lithium-ion cells, cold plates, coolant distribution units, dielectric immersion fluids and large chillers are still sourced mainly from China, the United States, Europe, Taiwan and South Korea. Lead times for large power transformers and medium-voltage switchgear stretched to 52 weeks during 2024 and 2025, while currency movement adds cost risk to dollar-priced equipment. Smaller Indian developers face higher financing costs than global hyperscalers, which limits their ability to pre-order long-lead items. Local manufacturing by Schneider Electric, Vertiv, ABB, Siemens, Hitachi Energy and Blue Star is expanding, but full localisation of liquid cooling and high-voltage gear will take several years across India’s AI data center infrastructure readiness market.
Key Market Trends: India AI Data Center Infrastructure Readiness Market
Rapid Shift From Air Cooling to Direct-to-Chip and Immersion Liquid Cooling for GPU Halls
The market is undergoing a clear technology shift toward liquid cooling, with direct-to-chip and immersion systems expected to account for 38.6% of cooling architecture value by 2032, up from 9.8% in 2025. Direct-to-chip cold plates remove up to 80% of server heat at the chip, allowing racks to run above 100 kW, while single-phase immersion tanks can support even higher densities with lower fan power. Developers including Yotta, CtrlS, NTT and Sify have launched liquid-cooling-ready halls or pilot deployments for GPU tenants through 2025 and 2026. Rear-door heat exchangers are also gaining traction as a retrofit path in older Mumbai and Chennai buildings, allowing operators to raise density without rebuilding the full air system. This technology transition is reinforcing India’s AI data center infrastructure readiness market forecast 2032 across both new build and retrofit projects.
Growth of Gigawatt-Scale AI Campuses and Captive Renewable Power Procurement Across Indian AI Campuses
A clear shift toward gigawatt-scale campuses is reshaping the market. Google’s Visakhapatnam AI hub, AdaniConneX’s multi-site pipeline, Reliance’s Jamnagar AI infrastructure plans and Yotta’s expansion in Navi Mumbai and Greater Noida point to campuses sized in hundreds of megawatts rather than tens. These sites are being paired with captive solar, wind and battery storage through group captive and green energy open access routes, along with on-site substations and microgrid controllers. On-site energy and microgrid infrastructure accounts for 14.8% of market value in 2025 and is expected to grow at 23.7% annually through 2032. Developers are also signing long-term renewable power purchase agreements to meet hyperscaler sustainability requirements, while some campuses are evaluating fuel cells and gas engines for bridging power during grid delays. This shift is lifting demand for integrated power, storage and control systems across India’s AI data center infrastructure readiness market.
Localisation of UPS, Switchgear, Transformer and Cooling Equipment Manufacturing in India
A wave of local manufacturing investment is reshaping the market supply base. Schneider Electric, Vertiv, ABB, Siemens, Hitachi Energy, Eaton and Delta Electronics have expanded Indian production of UPS systems, switchgear, transformers, busways, power distribution units and precision cooling units, while Blue Star, Voltas and Thermax are adding chiller and data center cooling lines. Larsen & Toubro and Sterling and Wilson are scaling design and build teams for turnkey AI halls. Make in India incentives, public procurement preference for local content and state industrial policies have encouraged this shift. Local sourcing shortens delivery times, reduces currency risk and supports lower cost per megawatt for Indian developers. Combined with policy-led demand from the IndiaAI Mission and hyperscaler pipelines, these developments are reinforcing India’s AI data center infrastructure readiness market forecast 2032 across the entire value chain.
Segmental Insights: India AI Data Center Infrastructure Readiness Market
By End-User: Hyperscalers & Cloud Providers Dominate India’s AI Data Center Infrastructure Readiness Market
The hyperscalers and cloud providers segment dominates the market, accounting for 46.3% of market value in 2025, driven by self-built campuses and large wholesale colocation leases signed by Google, Microsoft, Amazon Web Services and Oracle, along with Indian GPU cloud providers serving IndiaAI workloads. These customers specify liquid-cooling-ready halls, 2N power paths and renewable supply, which raises spend per megawatt. The BFSI segment contributes 18.7% of demand, supported by RBI data localisation, AI-led fraud detection and real-time payments growth. Government and public sector users account for 14.2%, led by IndiaAI compute capacity, state data centers and sovereign cloud projects. Telecom, IT and enterprise users make up the remaining 20.8%, with telecom operators building edge sites for AI inference close to users. In 2025 and 2026, new GPU cluster contracts with hyperscalers and IndiaAI empanelled providers reinforced segment leadership in India’s AI data center infrastructure readiness market.
By Infrastructure Component: Power Distribution & Backup Leads While Liquid Cooling Grows Fastest
Power distribution and backup infrastructure leads the market component mix, accounting for 34.2% of total value, driven by the high cost of medium-voltage switchgear, transformers, UPS systems, battery storage and diesel or gas gensets needed for redundant GPU power. Cooling and thermal management contributes another 24.6%, followed by on-site energy and microgrid systems at 14.8% and network and interconnect fabric at 12.1%. Water treatment and management accounts for 6.9% of value, while DCIM software, monitoring and physical security together form 7.4%. Within cooling, direct-to-chip and immersion liquid cooling is the fastest growing category, expanding at a CAGR of 31.4% through 2032 as racks above 60 kW become standard for AI training. Leading suppliers including Schneider Electric, Vertiv, ABB, Siemens and Blue Star have aligned product portfolios to this mix, driving higher value per megawatt across India’s AI data center infrastructure readiness market.
Regional Insights: India AI Data Center Infrastructure Readiness Market
Regional analysis of the market shows that West India leads with 49.4% of market value in 2025, driven by Mumbai and Navi Mumbai, which together host 790 MW of operational capacity, along with Pune and the cable landing stations that serve global traffic. South India follows with 37.2%, supported by Chennai at 305 MW, Bengaluru at 182 MW and Hyderabad at 152 MW, and it is the fastest growing region at a CAGR of 22.4% as Visakhapatnam develops into a new AI hub. North India contributes 9.6%, led by Noida and Greater Noida in Uttar Pradesh, where data center parks and state incentives are drawing hyperscale projects. East India accounts for 2.6% and Central India 1.2%, with Kolkata and Bhubaneswar emerging as edge and disaster recovery locations. In 2025 and 2026, new campus announcements in Navi Mumbai, Chennai, Hyderabad, Visakhapatnam and Greater Noida reinforced regional capacity hubs across India’s AI data center infrastructure readiness market.
Recent Developments: India AI Data Center Infrastructure Readiness Market
- The market witnessed strong momentum in investment and capacity progress during 2025 and 2026. The Ministry of Electronics and Information Technology reported in March 2026 that India’s data center capacity crossed 1,500 MW in 2025, a fourfold increase from 375 MW in 2020. By the same month, more than 38,000 GPUs had been onboarded on the IndiaAI compute portal, and 190 projects had been approved under the IndiaAI Mission.
- Hyperscalers deepened India-focused commitments. In October 2025, Google announced a USD 15 billion AI hub in Visakhapatnam with AdaniConneX and Bharti Airtel, its largest AI investment outside the United States. In December 2025, Microsoft announced USD 17.5 billion for cloud and AI infrastructure in India, and Amazon outlined a USD 35 billion investment plan through 2030. These developments are strengthening AI-ready demand and supporting India’s AI data center infrastructure readiness market forecast 2032.
- Policy momentum has gained strong traction in the market. In February 2026, the Union Budget 2026-27 introduced a tax holiday up to 2047 for notified foreign cloud service providers using MeitY-notified Indian data centers, with a 15% safe harbour for related-party facilities. Combined with state data center policies and RBI data localisation, this positions India as one of the fastest scaling AI infrastructure markets globally, strengthening long-term competitiveness in India’s AI data center infrastructure readiness market forecast 2032.
Key Market Players: India AI Data Center Infrastructure Readiness Market
- Schneider Electric India Pvt. Ltd.
- Vertiv Energy Pvt. Ltd.
- ABB India Limited
- Siemens Limited
- Hitachi Energy India Limited
- Eaton Power Quality Pvt. Ltd.
- Delta Electronics India Pvt. Ltd.
- Larsen & Toubro Limited
- Sterling and Wilson Pvt. Ltd.
- Blue Star Limited
- Thermax Limited
- Cummins India Limited
- Rittal India Pvt. Ltd.
| By Component | By Rack Density | By Cooling | By DC Type | By End-User |
| Power & Backup Cooling On-Site Energy Network Water Others | Below 10 kW 10-20 kW 20-40 kW 40-60 kW 60-100 kW 100-150 kW Above 150 kW | Air Cooling Rear-Door HX Direct-to-Chip Single-Phase Immersion Two-Phase Immersion | Hyperscale Colocation Enterprise Edge Sovereign AI | Hyperscalers BFSI Government Telecom, IT & Enterprises |
Report Scope
In this report, the India AI Data Center Infrastructure Readiness Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive environment, and growth opportunities across the forecast period:
- By Infrastructure Component
- Power Distribution & Backup Infrastructure
- Cooling & Thermal Management
- On-Site Energy & Microgrid Systems
- Network & Interconnect Fabric
- Water Treatment & Management
- Others (DCIM Software, Monitoring & Physical Security)
- By Rack Power Density
- Below 10 kW
- 10 kW to 20 kW
- 20 kW to 40 kW
- 40 kW to 60 kW
- 60 kW to 100 kW
- 100 kW to 150 kW
- Above 150 kW
- By Cooling Architecture
- Air Cooling (CRAC, CRAH & Fan Walls)
- Rear-Door Heat Exchangers
- Direct-to-Chip Liquid Cooling
- Single-Phase Immersion Cooling
- Two-Phase Immersion Cooling
- By Data Center Type
- Hyperscale Self-Build
- Wholesale Colocation
- Retail Colocation
- Enterprise & Captive Data Centers
- Edge Data Centers
- Sovereign & Government AI Compute
- By End-User
- Hyperscalers & Cloud Providers
- BFSI
- Government & Public Sector
- Telecom, IT & Enterprises
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in India’s AI Data Center Infrastructure Readiness Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging Indian data center developers, GPU cloud providers, liquid cooling specialists, regional EPC contractors, or niche power equipment makers.
For a free sample of the India AI Data Center Infrastructure Readiness Market report, customised insights or delivery timelines, submit your query here
India AI Data Center Infrastructure Readiness Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Infrastructure Component
- By Rack Power Density
- By Cooling Architecture
- By Data Center Type
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on AI Data Center Infrastructure in India
- AI Data Center Infrastructure Readiness Insights: India
- Market Dynamics
- Growth Drivers
- Sovereign AI compute build-out under the IndiaAI Mission and hyperscaler capital commitments driving AI-ready capacity.
- Rising rack power densities from GPU clusters forcing upgrades in power, cooling and electrical infrastructure.
- Data localisation rules, Budget 2026-27 tax holiday and state data center policies strengthening investment readiness.
- Restraints
- Grid interconnection delays and limited round-the-clock renewable power constraining AI campus timelines.
- Water stress and high ambient temperatures limiting cooling efficiency across key data center clusters.
- High import dependence for critical electrical and liquid cooling equipment raising capital costs and lead times.
- Opportunities
- Retrofitting legacy colocation halls with rear-door and direct-to-chip cooling to host GPU workloads.
- Sovereign AI, government cloud and edge inference sites opening new demand in tier-2 cities.
- Domestic manufacturing of cooling units, CDUs, UPS and switchgear creating supply opportunities under Make in India.
- Challenges
- Shortage of skilled engineers for liquid cooling, high-voltage design and AI hall commissioning.
- Land acquisition, environmental clearance and permitting delays for large AI campuses.
- Fast GPU generation cycles shortening the design life of power and cooling infrastructure.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Components & Materials (copper, steel, power semiconductors, battery cells, refrigerants, dielectric fluids)
- Electrical Equipment Manufacturers (Schneider Electric, ABB, Siemens, Hitachi Energy, Eaton, Delta Electronics)
- Cooling & Thermal Management Suppliers (Vertiv, Blue Star, Thermax, Rittal, liquid cooling OEMs)
- On-Site Energy & Backup Power Providers (Cummins, gensets, battery storage, fuel cells, captive solar)
- Design Standards, Certification & Testing (Uptime Institute tiers, TIA-942, BIS, CEA grid codes)
- EPC Contractors & MEP Integrators (Larsen & Toubro, Sterling and Wilson, specialist data center builders)
- Data Center Developers & Colocation Operators (Yotta, CtrlS, NTT, STT GDC India, AdaniConneX, Nxtra)
- Hyperscale Cloud & GPU-as-a-Service Providers (Google, Microsoft, AWS, IndiaAI empanelled providers)
- Power Utilities & Renewable Energy Developers (state DISCOMs, transmission companies, green energy open access)
- End-Users (AI developers, BFSI, government agencies, telecom operators, IT services, enterprises)
- India AI Data Center Infrastructure Readiness Market: Regulatory Framework
- India AI Data Center Infrastructure Readiness Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Capacity (MW)
- Market Share & Forecast
- By Infrastructure Component
- Power Distribution & Backup Infrastructure
- Cooling & Thermal Management
- On-Site Energy & Microgrid Systems
- Network & Interconnect Fabric
- Water Treatment & Management
- Others (DCIM Software, Monitoring & Physical Security)
- By Rack Power Density
- Below 10 kW
- 10 kW to 20 kW
- 20 kW to 40 kW
- 40 kW to 60 kW
- 60 kW to 100 kW
- 100 kW to 150 kW
- Above 150 kW
- By Cooling Architecture
- Air Cooling (CRAC, CRAH & Fan Walls)
- Rear-Door Heat Exchangers
- Direct-to-Chip Liquid Cooling
- Single-Phase Immersion Cooling
- Two-Phase Immersion Cooling
- By Data Center Type
- Hyperscale Self-Build
- Wholesale Colocation
- Retail Colocation
- Enterprise & Captive Data Centers
- Edge Data Centers
- Sovereign & Government AI Compute
- By End-User
- Hyperscalers & Cloud Providers
- BFSI
- Government & Public Sector
- Telecom, IT & Enterprises
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India AI Data Center Infrastructure Readiness Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Schneider Electric India Pvt. Ltd.
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Vertiv Energy Pvt. Ltd.
- ABB India Limited
- Siemens Limited
- Hitachi Energy India Limited
- Eaton Power Quality Pvt. Ltd.
- Delta Electronics India Pvt. Ltd.
- Larsen & Toubro Limited
- Sterling and Wilson Pvt. Ltd.
- Blue Star Limited
- Thermax Limited
- Cummins India Limited
- Rittal India Pvt. Ltd.
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India AI data center infrastructure readiness market and what is its growth forecast?
Ans: India's AI data center infrastructure readiness market is valued at USD 4,260 million in 2025 and is projected to reach USD 14,912 million by 2032, growing at a CAGR of 19.6%, supported by IndiaAI compute demand and hyperscaler investment.
2. Which segments are driving demand in India's AI data center infrastructure readiness market?
Ans: Power distribution and backup infrastructure leads with a 34.2% value share in 2025, while direct-to-chip and immersion liquid cooling is the fastest growing segment at a 31.4% CAGR as GPU rack densities rise.
3. What are the key drivers of growth in the India AI data center infrastructure readiness market?
Ans: Key drivers include the IndiaAI Mission and its 38,000 onboarded GPUs, hyperscaler commitments from Google, Microsoft and Amazon, rising rack power densities, data localisation rules and the Budget 2026-27 tax holiday.
4. Which regions are driving growth in the India AI data center infrastructure readiness market?
Ans: West India leads with a 49.4% share, driven by Mumbai and Navi Mumbai. South India holds 37.2% and is the fastest growing region, supported by Chennai, Hyderabad, Bengaluru and Visakhapatnam.
5. What are the latest trends in the India AI data center infrastructure readiness market?
Ans: The latest trends include the shift to direct-to-chip and immersion liquid cooling, gigawatt-scale AI campuses with captive renewable power, and growing local manufacturing of UPS, switchgear, transformers and cooling equipment.