

India EV Battery Pack Market, 2032
- Automotive & EV, Battery Storage & Materials, Energy, Power & Storage
- Nov 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s EV battery pack market is witnessing strong structural growth, driven by rapid EV adoption across two-wheelers, three-wheelers, and passenger cars, PM E-DRIVE and ACC PLI incentives, falling lithium-ion cell prices, the shift toward LFP battery packs, expansion of battery swapping networks, and rising investment from domestic and global players in India-specific cell gigafactories, battery pack assembly lines, and battery management technology.
| Study Duration | 2021-2032 |
| Market Size (2025) | USD 2,480 Million |
| CAGR (2026-2032) | 28.0% |
| Leading Segment | LFP Battery Packs (Electric Two-Wheelers) |
| Fastest Growing Segment | Electric Passenger Car & Bus Battery Packs |
| Market Size (2032) | USD 13,960 Million |
Market Overview: India EV Battery Pack Market
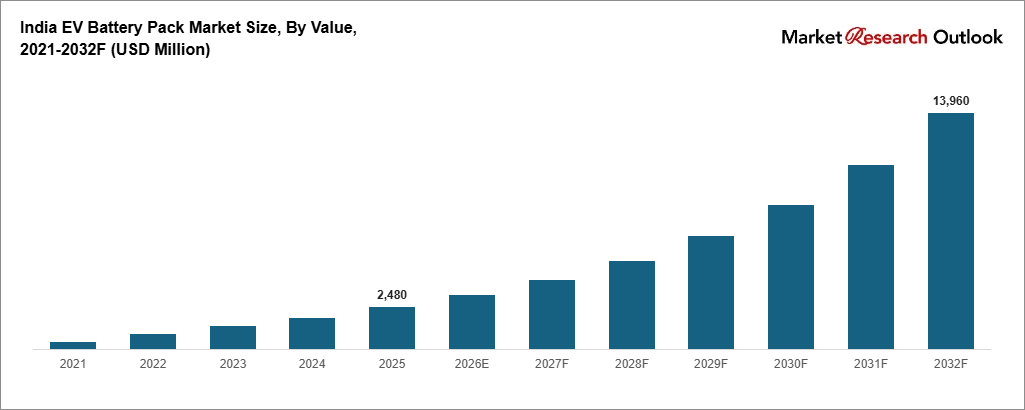
The India EV battery pack market size is expanding at a rapid pace, driven by rising EV sales, strong policy support under PM E-DRIVE and ACC PLI, falling lithium-ion cell prices, a growing base of battery swapping stations, and large capacity additions by domestic cell and battery pack makers. Valued at USD 2,480 million in 2025 and projected to reach USD 13,960 million by 2032, growing at a CAGR of 28.0%, India EV battery pack market growth is fuelled by strong demand from electric two-wheeler and three-wheeler OEMs, fleet electrification by e-commerce and ride-hailing firms, and a fast rise in electric car launches. LFP battery packs lead the EV battery pack market, while electric passenger car and bus battery packs form the fastest growing category. Higher safety standards, longer warranties, and demand for faster charging are reshaping the supply landscape. As domestic majors including Tata AutoComp, Exide Energy, Amara Raja, Ola Electric, and Agratas expand cell and battery pack capacity, and OEMs such as Tata Motors, Mahindra, Ather, and TVS Motor deepen in-house battery pack engineering, the India EV battery pack market is evolving into a localized, technology-driven, and highly competitive ecosystem with strong long-term growth potential.
Key Report Takeaways: India EV Battery Pack Market
- The India EV battery pack market size is projected to grow from USD 2,480 million in 2025 to USD 13,960 million by 2032, registering a strong CAGR of 28.0%, driven by rising EV sales, PLI-led cell localization, and the steady shift toward LFP battery packs across all vehicle segments.
- LFP battery packs dominate the India EV battery pack market, accounting for about 58% of total value in 2025, driven by better thermal safety, longer cycle life, lower cost per kWh, and wide use by three-wheeler, car, and bus OEMs such as Mahindra Last Mile Mobility, Tata Motors, and Olectra.
- Electric passenger car and bus battery packs are the fastest growing segments in the India EV battery pack market, expected to grow at 38% to 42% annually as new car launches, fleet electrification, and state bus tenders under PM E-DRIVE lift average battery pack sizes above 30 kWh.
- Rapid growth in EV registrations, with 2.3 million EVs sold in 2025 and annual battery demand of 17.7 GWh, is structurally expanding the India EV battery pack market across personal mobility, commercial fleet, and public transport categories.
- Rising investments by domestic majors such as Agratas, Exide Energy, Amara Raja, Ola Electric, and Reliance New Energy in cell gigafactories, battery pack assembly lines, and BMS technology are strengthening local supply and supporting the India EV battery pack market forecast 2032.
Key Market Drivers: India EV Battery Pack Market
Rapid EV Adoption Across Two-Wheelers, Three-Wheelers, and Passenger Cars Driving Battery Pack Demand Across India
Growth in the India EV battery pack market is driven by the fast rise in EV sales across two-wheelers, three-wheelers, and passenger cars. As per Vahan data, India sold 2.3 million EVs in 2025, equal to 8% of all new vehicle registrations. Electric two-wheelers led with 1.28 million units, or 57% of EV sales, while electric three-wheelers added 0.8 million units and electric four-wheelers reached about 175,000 units. Electric L5 three-wheelers have crossed 30% penetration in their segment, making them the most electrified vehicle class in India. Every EV needs a battery pack, and sizes range from 2 to 4 kWh in scooters, 7 to 11 kWh in L5 three-wheelers, 25 to 80 kWh in cars, and 250 to 400 kWh in e-buses. Annual EV battery demand in India reached 17.7 GWh in 2025, and our estimates show it can reach about 165 GWh by 2032. Lower running costs, rising fuel prices, and a growing range of models under INR 15 lakh are creating strong pull-through demand across the India EV battery pack market.
Government Incentives Under PM E-DRIVE, ACC PLI, and State EV Policies Fuelling Domestic Battery Pack Manufacturing
The India EV battery pack market gains from strong and steady policy support. The PM E-DRIVE scheme, launched in October 2024 with an outlay of INR 10,900 crore, supports electric two-wheelers, three-wheelers, trucks, ambulances, and over 14,000 e-buses. The ACC PLI scheme, with an outlay of INR 18,100 crore, targets 50 GWh of advanced cell capacity, and the PLI scheme for automobiles and auto components rewards local value addition in battery packs. Phased Manufacturing Programme rules push OEMs to source cells, BMS, and enclosures locally to claim subsidies. More than 25 states, including Uttar Pradesh, Maharashtra, Tamil Nadu, Karnataka, Gujarat, and Telangana, now run EV policies with road tax waivers, capital subsidies, and land support for battery plants. Together, these measures lower the cost of local battery pack assembly and give domestic EV battery pack makers a clear edge over imported battery packs in the India EV battery pack market.
Falling Lithium-Ion Cell Prices and LFP Chemistry Advancements Strengthening EV Battery Pack Affordability
Falling cell prices are a major catalyst for the India EV battery pack market. Lithium carbonate prices have dropped by more than 75% from their 2022 peak, and LFP cell prices fell below USD 60 per kWh in 2025. Average LFP battery pack prices in India now range between USD 135 and USD 150 per kWh, and our estimates show they can fall to USD 80 to USD 90 per kWh by 2032. Since cells make up 70% to 75% of total battery pack cost, lower cell prices pass directly into cheaper EVs. LFP chemistry also gives 3,000 to 6,000 charge cycles, better heat tolerance, and lower fire risk than older NMC battery packs, which suits India’s hot climate. Cell-to-pack and blade designs have lifted LFP battery pack energy density by 10% to 15%, closing the range gap with NMC. These gains bring the total cost of ownership of electric scooters, three-wheelers, and small cars close to petrol and diesel models, structurally expanding India EV battery pack market growth across all major end-user categories through 2032.
Key Market Challenges: India EV Battery Pack Market
Heavy Dependence on Imported Lithium-Ion Cells and Critical Minerals Limiting Domestic Value Addition
The India EV battery pack market still depends heavily on imported lithium-ion cells, with over 75% of cells sourced from China and smaller volumes from South Korea and Japan. Under the ACC PLI scheme, only 1.4 GWh of the targeted 50 GWh cell capacity was commissioned by October 2025, entirely by Ola Electric, while other projects are running behind schedule. India also has almost no commercial production of refined lithium, cobalt, nickel, or battery-grade graphite, so cathode and anode materials are largely imported. Because cells form 70% to 75% of battery pack cost, local value addition by most battery pack assemblers remains limited to modules, BMS, wiring, and enclosures. Supply risks, longer lead times, and currency swings continue to weigh on cost control across the India EV battery pack market.
Thermal Safety Concerns and Stringent AIS-156 Compliance Raising Battery Pack Design and Testing Costs
The India EV battery pack market faces added complexity from battery safety rules and thermal risks. After a series of electric scooter fire incidents in 2022, the government brought in AIS-156 and AIS-038 amendments, with Phase 2 norms in force from December 2023. These rules require cell-level fuse protection, thermal propagation tests, IP67 ingress protection, BMS data logging, and cell traceability. Testing and certification at ARAI or ICAT can add INR 30 lakh to INR 1 crore per pack platform and stretch launch timelines by three to six months. Ambient temperatures above 45°C in many states speed up cell ageing and raise the need for active cooling. Smaller battery pack makers in particular find it hard to fund these upgrades, which slows new product launches in the India EV battery pack market.
Volatility in Lithium, Nickel, and Cobalt Prices Impacting Overall EV Battery Pack Margins
The India EV battery pack market faces practical limits from raw material price swings and thin margins across the value chain. Lithium carbonate prices rose more than fivefold in 2021 and 2022 before falling sharply in 2023 and 2024, while nickel and cobalt prices remain sensitive to supply moves in Indonesia and the Democratic Republic of Congo. Pack makers that sign fixed-price contracts with OEMs often absorb these swings, and average gross margins for independent battery pack assemblers in India range between 12% and 18%. Price wars in the electric two-wheeler segment push OEMs to demand yearly cost cuts of 5% to 8% from suppliers. Long-term cell supply deals, LFP and sodium-ion chemistries, and local cathode projects are emerging as hedges, but limited scale and price pressure remain barriers across the India EV battery pack market.
Key Market Trends: India EV Battery Pack Market
Rapid Shift Toward LFP, LMFP, and Sodium-Ion Battery Pack Chemistries in India
The India EV battery pack market is seeing a clear technology shift toward LFP, LMFP, and sodium-ion chemistries, with LFP already holding about 58% of battery pack value in 2025 and expected to cross 65% by 2030. Tata Motors, Mahindra, MG Motor, and most three-wheeler OEMs now use LFP cells, while two-wheeler makers are steadily moving from NMC to LFP for better safety and cost. LMFP cells raise energy density by 15% to 20% over standard LFP while keeping its thermal stability, and are expected in Indian cars from 2027. Sodium-ion cells, which need no lithium, cobalt, or nickel, are being tested by Reliance New Energy, KPIT, and several start-ups for e-rickshaws and entry scooters. Ola Electric has started fitting its in-house 4680 Bharat Cell in its scooters, marking a new phase for locally made cells. This chemistry transition is reinforcing the India EV battery pack market forecast 2032 across both personal and commercial segments.
Growth of Battery Swapping, Battery-as-a-Service, and Fleet Electrification in the India EV Battery Pack Market
A clear shift toward battery swapping and battery-as-a-service (BaaS) models is reshaping the India EV battery pack market, especially in the commercial two-wheeler and three-wheeler segment. Under these models, delivery riders and e-rickshaw drivers lease swappable battery packs and replace a discharged battery pack in under two minutes, cutting the upfront vehicle cost by 30% to 40%. Leading swapping operators such as SUN Mobility, Battery Smart, and Yuma Energy have built networks across major cities, while e-commerce and quick-commerce firms including Amazon, Flipkart, Zomato, Swiggy, and Zepto are moving their last-mile fleets to EVs. Each swapping station needs 1.3 to 1.6 battery packs per vehicle served, which lifts total battery pack demand beyond new vehicle sales. By 2025, swapping and BaaS models accounted for about 6% of EV battery pack demand in India, and this share is expected to rise steadily through 2032.
Capacity Expansion by Domestic Gigafactories and Battery Pack Assembly Investments
A wave of domestic capacity expansion is reshaping the India EV battery pack market supply landscape. Announced cell and battery pack investments in India exceed USD 8 billion, with over 100 GWh of cell capacity in the pipeline. Agratas, the Tata Group battery arm, is building a 20 GWh first phase at Sanand in Gujarat, Exide Energy is ramping a 12 GWh cell plant in Bengaluru, Amara Raja is developing a 16 GWh cell and 5 GWh battery pack facility in Telangana, Reliance New Energy is setting up capacity at Jamnagar, and Ola Electric runs its Krishnagiri gigafactory in Tamil Nadu. Pack assemblers such as Tata AutoComp, Battrixx, Trontek, Inverted Energy, and Octillion are adding automated module and battery pack lines near OEM hubs. Combined with ACC PLI support, PM E-DRIVE demand, and local BMS development, these moves are reinforcing the India EV battery pack market forecast 2032 across the entire value chain.
Segmental Insights: India EV Battery Pack Market
By End-User: Personal Mobility Segment Dominates the India EV Battery Pack Market
The personal mobility end-user segment dominates the India EV battery pack market, accounting for about 52% of total value in 2025, driven by strong sales of electric scooters, motorcycles, and passenger cars to private buyers. Battery packs below 5 kWh used in two-wheelers form the core of this segment, with cylindrical and prismatic cells making up over 85% of personal mobility battery pack volume. The commercial fleets and logistics segment adds another 33% of demand, led by L5 cargo three-wheelers, e-rickshaws, and delivery two-wheelers, where total cost of ownership drives buying. Public transport contributes about 9%, led by e-bus orders from state transport undertakings, while battery swapping operators account for the remaining 6%. In 2025, leading OEMs including Ola Electric, TVS Motor, Ather, Bajaj Auto, and Tata Motors expanded models for private buyers, reinforcing segment dominance in the India EV battery pack market.
By Vehicle Type: Two-Wheelers Lead While Passenger Cars and Buses Grow Fastest
Electric two-wheelers lead the India EV battery pack market by vehicle type, accounting for about 42% of total battery pack value in 2025, driven by high sales volumes, a wide price range of models, and strong OEM competition. Electric three-wheelers, including L5 autos and L3 e-rickshaws, add another 24%, mainly in tier-2 and tier-3 cities and last-mile logistics. Electric passenger car battery packs hold about 22% of value and, together with e-bus battery packs at about 7%, form the fastest growing categories, expanding at 38% to 42% annually as average battery pack sizes rise and more models launch. Electric light commercial vehicles and other vehicles account for the remaining 5%. Leading players including Tata AutoComp, Exide Energy, Amara Raja, Octillion, and Agratas have aligned their product lines to this vehicle mix, driving higher value per battery pack across the India EV battery pack market.
Regional Insights: India EV Battery Pack Market
Regional analysis of the India EV battery pack market shows that South India and West India together account for about 54% to 58% of total demand, driven by Tamil Nadu (Hosur and Krishnagiri EV cluster), Karnataka (Bengaluru), Telangana, Maharashtra (Pune and Chakan auto belt), and Gujarat (Sanand), supported by strong OEM presence and supportive state EV policies. North India contributes around 26% to 29% of demand, led by Uttar Pradesh, which was India’s largest EV market in 2025 with about 18% of total EV sales, along with Delhi NCR, Haryana, and Rajasthan, where e-rickshaw and two-wheeler adoption is high. Central and East India together account for 15% to 18% of demand, supported by Madhya Pradesh, Bihar, West Bengal, Assam, and Odisha. In 2025, cell and battery pack investments by Agratas in Gujarat, Exide Energy in Karnataka, Amara Raja in Telangana, and Ola Electric in Tamil Nadu reinforced regional supply hubs across the India EV battery pack market.
Battery manufacturing data: see the India ACC Battery PLI Tracker for cell capacity awarded and commissioned under the PLI scheme, and the India EV Projects Tracker for battery and EV plant investments.
Recent Developments: India EV Battery Pack Market
- The India EV battery pack market recorded strong momentum in sales and capacity during 2024 and 2025. Annual EV battery demand in India reached 17.7 GWh in 2025, up about 34% from 13.2 GWh in 2024, according to industry tracking. EV sales crossed 2.3 million units in 2025, with monthly sales topping 200,000 units for the first time in October 2025. Our estimates show cumulative EV battery pack deployment in India can reach 55 to 60 GWh by FY27, growing at an average of over 30% a year.
- Domestic battery majors have deepened India-focused capacity expansion. In 2025, Ola Electric began using its in-house 4680 Bharat Cell in its scooters, Exide Energy started trial production at its Bengaluru cell plant, Amara Raja progressed its Telangana Giga Corridor, Agratas advanced construction at Sanand, and Reliance New Energy pushed ahead with its Jamnagar battery giga complex. Several battery pack assemblers also added AIS-156 compliant lines. These steps are strengthening domestic supply and supporting the India EV battery pack market forecast 2032.
- OEM and fleet momentum has gained strong traction in the India EV battery pack market. In 2025, leading OEMs including Tata Motors, Mahindra, MG Motor, Ather, TVS Motor, and Bajaj Auto launched new EV models with larger LFP battery packs, while e-bus tenders under PM E-DRIVE and battery swapping deals with delivery fleets lifted commercial demand. Strategic tie-ups between cell makers, battery pack assemblers, and OEMs are positioning India as one of the fastest scaling EV battery pack markets globally, strengthening long-term competitive positioning in the India EV battery pack market forecast 2032.
Key Market Players: India EV Battery Pack Market
- Tata AutoComp Systems Limited
- Exide Energy Solutions Limited
- Amara Raja Energy & Mobility Limited
- Ola Electric Mobility Limited
- Agratas Energy Storage Solutions Pvt. Ltd.
- Reliance New Energy Limited
- Ather Energy Limited
- Battrixx (Kabra Extrusiontechnik Ltd.)
- Trontek Electronics Pvt. Ltd.
- Exicom Tele-Systems Limited
- Octillion Power Systems India Pvt. Ltd.
- Inverted Energy Pvt. Ltd.
- Lohum Cleantech Pvt. Ltd.
| By Battery Chemistry | By Vehicle Type | By Form Factor | By Battery Capacity | By End-User |
| Lithium Iron Phosphate (LFP) Nickel Manganese Cobalt (NMC) Lithium Manganese Iron Phosphate (LMFP) Lead-Acid Sodium-Ion Others |
Electric Two-Wheelers Electric Three-Wheelers (L5) E-Rickshaws (L3) Electric Passenger Cars Electric Light Commercial Vehicles Electric Buses Others |
Cylindrical (2170, 4680) Prismatic Pouch Blade Others |
Below 5 kWh 5-15 kWh 15-30 kWh 30-50 kWh 50-100 kWh Above 100 kWh |
Personal Mobility Commercial Fleets & Logistics Public Transport Battery Swapping Operators |
Report Scope
In this report, the India EV Battery Pack Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Battery Chemistry
- Lithium Iron Phosphate (LFP)
- Nickel Manganese Cobalt (NMC)
- Lithium Manganese Iron Phosphate (LMFP)
- Lead-Acid
- Sodium-Ion
- Others
- By Vehicle Type
- Electric Two-Wheelers
- Electric Three-Wheelers (L5)
- E-Rickshaws (L3)
- Electric Passenger Cars
- Electric Light Commercial Vehicles
- Electric Buses
- Others
- By Form Factor
- Cylindrical (2170, 4680)
- Prismatic
- Pouch
- Blade
- Others
- By Battery Capacity
- Below 5 kWh
- 5-15 kWh
- 15-30 kWh
- 30-50 kWh
- 50-100 kWh
- Above 100 kWh
- By End-User
- Personal Mobility
- Commercial Fleets & Logistics
- Public Transport
- Battery Swapping Operators
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India EV Battery Pack Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging domestic battery pack assemblers, specialty BMS and thermal management suppliers, battery swapping operators, or niche state-level EV battery brands.
For a free sample of the India EV Battery Pack Market report, customised insights or delivery timelines, submit your query here
India EV Battery Pack Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Battery Chemistry
- By Vehicle Type
- By Form Factor
- By Battery Capacity
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India EV Battery Pack Market
- India EV Battery Pack Market Insights
- Market Dynamics
- Growth Drivers
- Rapid EV adoption across two-wheelers, three-wheelers, and passenger cars driving battery pack demand across India.
- Government incentives under PM E-DRIVE, ACC PLI, and state EV policies fuelling domestic battery pack manufacturing.
- Falling lithium-ion cell prices and LFP chemistry advancements strengthening EV battery pack affordability.
- Restraints
- Heavy dependence on imported lithium-ion cells and critical minerals limiting domestic value addition in battery packs.
- Thermal safety concerns and stringent AIS-156 compliance raising battery pack design, testing, and certification costs.
- Volatility in lithium, nickel, and cobalt prices impacting overall EV battery pack margins.
- Opportunities
- Localized cell manufacturing through ACC PLI gigafactories opening new value pools for domestic battery pack makers.
- Battery swapping and battery-as-a-service models supporting next-generation growth in commercial EV fleets.
- Battery recycling, second-life storage, and EPR mandates under BWMR 2022 creating circular battery pack opportunities.
- Challenges
- Intense price competition from imported battery modules and low-cost unorganized battery pack assemblers.
- Limited testing infrastructure, charging coverage, and skilled workforce across smaller Indian cities.
- Maintaining battery pack performance, cycle life, and thermal stability in India’s high-temperature climate.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Raw Materials (lithium, nickel, cobalt, manganese, graphite, electrolytes, separators)
- Cathode & Anode Material Producers (Himadri Speciality, Epsilon Advanced Materials, Altmin, Tata Chemicals)
- Lithium-Ion Cell Manufacturers (Ola Electric, Agratas, Exide Energy, Amara Raja, Reliance New Energy)
- BMS & Thermal Management Suppliers (battery management systems, cooling plates, sensors, busbars)
- Testing, Certification & Quality Laboratories (ARAI, ICAT, BIS, AIS-156, AIS-038 standards)
- Battery Pack Assemblers & Integrators (Tata AutoComp, Battrixx, Trontek, Inverted Energy, Octillion)
- EV OEMs (Tata Motors, Mahindra, Ola Electric, Ather, TVS Motor, Bajaj Auto, Hero MotoCorp)
- Brand Owners & Battery-as-a-Service Providers (SUN Mobility, Battery Smart, Yuma Energy)
- Recycling & Second-Life Operators (Lohum, Attero, Rubamin, Exigo Recycling)
- End-Users (private owners, delivery fleets, ride-hailing operators, state transport undertakings)
- India EV Battery Pack Market: Regulatory Framework
- India EV Battery Pack Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (GWh)
- Market Share & Forecast
- By Battery Chemistry
- Lithium Iron Phosphate (LFP)
- Nickel Manganese Cobalt (NMC)
- Lithium Manganese Iron Phosphate (LMFP)
- Lead-Acid
- Sodium-Ion
- Others
- By Vehicle Type
- Electric Two-Wheelers
- Electric Three-Wheelers (L5)
- E-Rickshaws (L3)
- Electric Passenger Cars
- Electric Light Commercial Vehicles
- Electric Buses
- Others
- By Form Factor
- Cylindrical (2170, 4680)
- Prismatic
- Pouch
- Blade
- Others
- By Battery Capacity
- Below 5 kWh
- 5-15 kWh
- 15-30 kWh
- 30-50 kWh
- 50-100 kWh
- Above 100 kWh
- By End-User
- Personal Mobility
- Commercial Fleets & Logistics
- Public Transport
- Battery Swapping Operators
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India EV Battery Pack Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Tata AutoComp Systems Limited
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Exide Energy Solutions Limited
- Amara Raja Energy & Mobility Limited
- Ola Electric Mobility Limited
- Agratas Energy Storage Solutions Pvt. Ltd.
- Reliance New Energy Limited
- Ather Energy Limited
- Battrixx (Kabra Extrusiontechnik Ltd.)
- Trontek Electronics Pvt. Ltd.
- Exicom Tele-Systems Limited
- Octillion Power Systems India Pvt. Ltd.
- Inverted Energy Pvt. Ltd.
- Lohum Cleantech Pvt. Ltd.
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India EV battery pack market and what is its growth forecast?
Ans: The India EV battery pack market is valued at USD 2,480 million in 2025 and is projected to reach USD 13,960 million by 2032, growing at a CAGR of 28.0%.
2. Which segments are driving demand in the India EV battery pack market?
Ans: LFP battery packs lead with about 58% share in 2025, while electric passenger car and bus battery packs are the fastest-growing segments, expanding at 38% to 42% annually.
3. What are the key drivers of growth in the India EV battery pack market?
Ans: Key drivers include rapid EV adoption, PM E-DRIVE and ACC PLI incentives, state EV policies, falling lithium-ion cell prices, and steady advances in LFP battery pack technology.
4. Which regions are driving growth in the India EV battery pack market?
Ans: South India and West India lead with around 54% to 58% of demand, driven by Tamil Nadu, Karnataka, Maharashtra, and Gujarat. North India, led by Uttar Pradesh and Delhi NCR, follows closely.
5. What are the latest trends in the India EV battery pack market?
Ans: Key trends include the shift to LFP, LMFP, and sodium-ion chemistries, growth of battery swapping, cell-to-pack designs, and rising gigafactory capacity from Agratas, Exide Energy, Amara Raja, and Ola Electric.