

India Grid Scale Battery Storage Market Size & Forecast 2032
- Battery Storage & Materials, Energy, Power & Storage
- Oct 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s grid-scale battery storage market is witnessing strong structural growth, driven by viability gap funding of INR 5,400 crore for 30 GWh, accelerating central agency and state discom procurement, the shift toward four-hour systems, falling delivered system cost, regulatory correction of tariff benchmarks, deepening lender participation, and rising interest from domestic and global developers investing in India-specific project pipelines, cell manufacturing capacity, and energy management platforms.
| Study Duration | 2021-2032 |
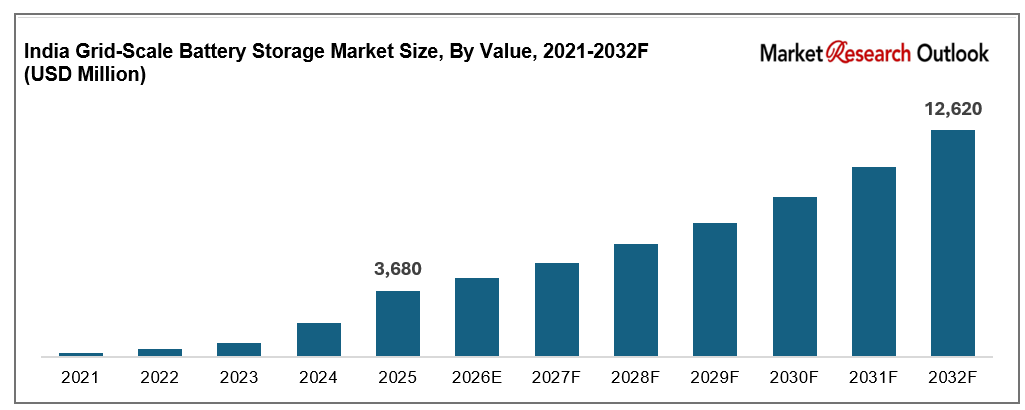
| Market Size (2025) | USD 3,680 Million |
| CAGR (2026-2032) | 19.2% |
| Leading Segment | Capacity Charge Contracts (Two-Hour LFP Systems) |
| Fastest Growing Segment | Ancillary Services & Four-Hour Storage |
| Market Size (2032) | USD 12,620 Million |
Market value in this report is measured on a contracted capacity value basis, covering capacity charges, firming, arbitrage and ancillary revenue under contracts awarded each year. It is therefore higher than estimates based only on battery equipment sales.
India Grid Scale Battery Storage Market Overview
The India grid-scale battery storage market size is witnessing rapid expansion, driven by viability gap funding, accelerating renewable capacity additions, widening evening peak deficits, competitive reverse auctions, and the first wave of domestic cell manufacturing. Valued at USD 3,680 million in 2025 and projected to reach USD 12,620 million by 2032, growing at a CAGR of 19.2%, the India grid-scale battery storage market growth is being fuelled by contracted capacity awarded through central agency and state discom tenders across Gujarat, Rajasthan, Andhra Pradesh, Tamil Nadu, Maharashtra and Uttar Pradesh. Capacity charge contracts lead the revenue mix, while ancillary services and four-hour systems are emerging as the fastest growing categories. A shift toward longer duration, tighter regulatory benchmarking of tariffs, and stronger payment security are reshaping the bankability of new assets. As developers including Tata Power Renewable Energy, JSW Energy, NTPC Green Energy, Adani Green Energy and ReNew scale delivery, and as banks and infrastructure funds widen exposure to storage, the India battery storage market is evolving into a contracted, capital-intensive, and revenue-stacked asset class with strong long-term growth potential.
Related research: India Renewable Energy Curtailment Market, India Battery Energy Storage System Market and India BESS Manufacturing Market.
Key Report Takeaways: India Grid Scale Battery Storage Market
- The India grid-scale battery storage market size is projected to grow from USD 3,680 million in 2025 to USD 12,620 million by 2032, registering a strong CAGR of 19.2%, driven by viability gap funding, accelerating discom procurement, and the structural shift toward contracted, long-duration battery storage across the Indian grid.
- Capacity charge contracts dominate the India grid-scale battery storage market, accounting for 71% of contracted revenue in 2025, driven by fixed monthly payments that are independent of dispatch, the aggregator structure used by SECI and NVVN, and the clear preference among lenders for availability linked income over merchant exposure.
- Ancillary services and four-hour storage are emerging as the fastest growing segments in the India grid-scale battery storage market, expected to grow at 34.5% annually as frequency support, overnight balancing, and resource adequacy requirements reshape procurement across central and state buyers.
- Tendering has scaled sharply, with 281 GWh of energy storage tendered by the first half of 2026, of which 105 GWh is under execution and 110 GWh remains in the tendering stage, structurally expanding the India grid-scale battery storage market across utility, transmission, and independent power producer categories.
- Rising investment by developers such as Tata Power Renewable Energy, JSW Energy, NTPC Green Energy, Adani Green Energy and Greenko in project pipelines, domestic cell capacity, and energy management platforms is strengthening local supply and supporting the India grid-scale battery storage market forecast 2032.
Key Drivers of the India Grid Scale Battery Storage Market
Viability Gap Funding and Central Policy Support Making Grid-Scale Battery Storage Bankable Across India
Growth in the India grid-scale battery storage market is being driven by viability gap funding, which closes the gap between project cost and the tariff distribution utilities are willing to pay. The first scheme, notified in September 2023, supported 4,000 MWh with assistance of up to 40% of capital cost at INR 27 lakh per MWh. The second tranche, cleared by the Cabinet on 14 May 2026, committed INR 5,400 crore from the Power System Development Fund for 30 GWh of new capacity, with support set at 16% and a domestic value addition requirement of 20%. Cumulative viability gap funding now stands near INR 9,100 crore across 43.2 GWh. Support is released in five instalments linked to commissioning and dispatch availability, with developers furnishing bank guarantees against disbursed amounts. The National Electricity Plan sets a requirement of 47.24 GW and 236.22 GWh of battery storage by 2031-32. Taken together with the advanced chemistry cell programme, this policy stack is converting announced pipelines into financed assets across the India battery storage market.
Renewable Additions, Evening Peak Deficits and Round-the-Clock Procurement Fuelling Contracted Storage Demand
The India grid-scale battery storage market is benefiting from the speed of renewable capacity additions and the evening peak that solar generation alone cannot serve. India crossed the milestone of 50% non-fossil installed capacity in 2025, five years ahead of its stated commitment, pushing surplus midday output higher and sharpening the need to shift energy past sunset. The India Energy Storage Alliance places national requirement at 888 GWh of storage by 2035-36. Procurement has responded in kind: 69 storage tenders totalling 102 GWh were floated during 2025, a rise of 35% over 2024, while firm and dispatchable renewable energy tenders now bundle battery storage with solar and wind to deliver contracted round-the-clock supply. Uttar Pradesh has shifted its programme toward four-hour systems for overnight support, Andhra Pradesh has outlined a 3,000 MWh plan to cut expensive peak purchases, and Gujarat runs a phased pipeline through GUVNL. This depth of procurement is converting policy intent into contracted revenue across the India battery storage market.
Falling Delivered Costs, Competitive Reverse Auctions and Domestic Cell Manufacturing Strengthening Project Returns
Cost reduction remains a major catalyst for the India grid-scale battery storage market, with turnkey grid-scale systems now delivered near INR 1.65 crore per MWh. Discovered tariffs have fallen from INR 10.83 lakh per MW per month in India’s first storage tender in 2022 to INR 1.48 lakh per MW per month in the APTRANSCO auction of December 2025, a decline of 86% in under three years. Lithium iron phosphate chemistry is expected to carry the bulk of the 30 GWh build-out, with sodium-ion and flow batteries confined to pilot scale. The advanced chemistry cell programme and the 20% domestic value addition rule are pulling cell, module and power conversion capacity onshore, reducing exposure to import duty and currency movement. Reverse auctions run by GUVNL, NVVN, NTPC and state utilities have widened the bidder pool well beyond the original developer set, with Shreyas Sortex, Oriana Power, Pace Digitek and Bondada Engineering winning capacity alongside established names. Lower delivered cost, deeper competition, and localisation together support returns across the India battery storage market through 2032.
India Grid Scale Battery Storage Market Challenges
Aggressive Tariff Bidding and Thin Margins Weakening Project Viability and Lender Confidence
The India grid-scale battery storage market continues to face pressure from bids priced below the level at which assets can comfortably service debt. Against an industry benchmark of INR 2.3 lakh per MW per month for the two-hour, two-cycle configuration, the lowest discovered tariff of 2025 reached INR 1.48 lakh per MW per month, and close to 75% of allocated two-hour capacity sits in the at-risk category on viability grounds. The four-hour segment is better placed, with more than two-thirds of allocated capacity aligned to benchmark pricing. Of the 10.8 GW auctioned across 18 tenders during 2025, about 10.4 GW was allocated, an allotment rate near 97%, with two-hour systems taking 86% of the volume. Lenders have responded by tightening debt sizing, raising sponsor equity requirements, and asking for longer delivery track records. The Gujarat Electricity Regulatory Commission approved tariffs of INR 1,89,000 per MW per month for 1.665 GW under Phase VII, an upward correction that signals where sustainable pricing sits across the India battery storage market.
Discom Payment Delays, Weak Payment Security and Offtaker Credit Risk Constraining Bankability
The India grid-scale battery storage market faces structural complexity from the credit quality of its buyers. Most capacity is contracted with state distribution utilities, either directly or through aggregator agencies that sign the storage agreement and pass capacity through to the discom. Payment delays, accumulated regulatory assets and tariff under-recovery at several utilities lengthen receivable cycles and force developers to fund working capital at higher cost. The Central Electricity Regulatory Commission cancelled a 500 MW and 1,000 MWh standalone tender in January 2025 after prolonged delays in signing project agreements, and an estimated 48 GW of renewable and hybrid capacity remains held up in similar bottlenecks. Letters of credit, payment security funds and tripartite arrangements reduce but do not remove the exposure. Until buyer credit quality improves consistently, the cost of debt will stay elevated across the India battery storage market.
Import Dependence for Cells, Currency Volatility and Rising Battery Prices Pressuring Capital Costs
The India grid-scale battery storage market faces practical constraints around cell sourcing, input prices and margin compression across the value chain. Most lithium iron phosphate cells are still imported, leaving delivered cost exposed to freight, duty and exchange rate movement. Cell prices rose through 2026 on higher metal costs and changes to export policy in supplier markets, reversing two years of decline and squeezing developers who had bid on a falling-cost assumption. Fixed capacity charges quoted in Indian rupees over 12-year and 15-year tenors leave limited room to pass input inflation through to buyers. Domestic manufacturing under the advanced chemistry cell programme, the 20% domestic value addition requirement, and longer warranted cycle life are emerging as mitigations, though capacity ramp will take time. Until local supply scales, input volatility will remain a live risk to returns across the India battery storage market.
India Grid Scale Battery Storage Market Trends
Shift From Two-Hour Peak Shaving to Four-Hour and Longer-Duration Storage Contracts in India
The India grid-scale battery storage market is undergoing a clear shift toward longer duration, with four-hour systems expected to take 38% of newly contracted capacity by 2029 against 24% in 2025. Two-hour, two-cycle contracts on a 12-year tenor represented 57% of capacity allocated during 2025 and were designed mainly for evening peak shaving. Four-hour systems cleared at INR 2.85 lakh per MW per month at the low end and INR 4.57 lakh per MW per month at the high end, reflecting higher capital intensity per megawatt. Uttar Pradesh has moved its programme decisively toward four-hour procurement for overnight support, while West Bengal awarded 200 MW and 800 MWh to NTPC Green Energy at INR 4.35 lakh per MW per month. Kerala contracted 250 MW and 500 MWh over 15 years with an annual requirement of 420 cycles, with Shreyas Sortex quoting INR 1.81 lakh per MW per month. Longer duration raises capital cost but improves revenue certainty and reduces cycling stress, a combination lenders prefer. This transition is reinforcing the India battery storage market forecast 2032 across both central and state procurement.
Tariff Correction, Regulatory Benchmarking and the Return of Bankable Pricing in Battery Storage
A visible correction in discovered tariffs is reshaping the India grid-scale battery storage market. After the floor of INR 1.48 lakh per MW per month set in December 2025, pricing has moved back toward levels that genuinely support debt service. The Gujarat Electricity Regulatory Commission approved INR 1,85,390 per MW per month at the lower bound and INR 1,89,000 per MW per month at the upper bound for 1.665 GW under Phase VII. The GUVNL Phase IX auction for 450 MW and 900 MWh closed at INR 2,31,989 per MW per month, won by NLC India Renewables and Sun Drops Energia. Telangana auctions run through TGGENCO have settled near INR 2.4 lakh per MW per month, while Telangana’s Clean and Green Energy Policy 2025 adds nominal land lease and state tax reimbursement. Regulators increasingly test quoted tariffs against input cost benchmarks before approving adoption, which lengthens award-to-signature timelines but improves the credit quality of contracted cash flow across the India battery storage market.
Domestic Cell Manufacturing, Localisation Requirements and Integrated Developer-EPC Models
A wave of localisation and vertical integration is reshaping supply across the India grid-scale battery storage market. The second viability gap funding tranche carries a 20% domestic value addition requirement, pulling cell, module, power conversion and container assembly work onshore. Exide Energy Solutions and Amara Raja Energy & Mobility are commissioning lithium iron phosphate cell capacity, while Waaree, Sterling and Wilson, Larsen & Toubro and Pace Digitek have built integrated engineering, procurement and construction capability for storage. Developers are internalising system integration, energy management software and long-term maintenance rather than buying each as a separate package, which shortens delivery timelines and improves warranty enforcement. Combined with the advanced chemistry cell programme and rising order visibility from a 105 GWh execution pipeline, these developments are reinforcing the India battery storage market forecast 2032 across the entire value chain.
India Grid Scale Battery Storage Market Share by Segment
By End-User: Distribution Utilities Segment Dominates the India Grid-Scale Battery Storage Market
The distribution utilities end-user segment dominates the India grid-scale battery storage market, accounting for an estimated 58% of contracted value, driven by state procurement programmes, viability gap funding eligibility, and the obligation to serve evening peak demand at controlled cost. Capacity charge contracts on 12-year tenors are the dominant structure within this segment, with two-hour systems capturing 62% of contracted duration. Independent power producers and developers contribute another 24% of demand, holding assets through project vehicles and selling contracted capacity to utilities and aggregator agencies. Transmission and grid operators account for 11%, led by frequency support, congestion relief and system strength requirements. Commercial and industrial consumers make up 7%, concentrated in open access and captive structures. In 2025, GUVNL, APTRANSCO, UPPCL, WBSEDCL and TANGEDCO scaled utility-led procurement, reinforcing segment dominance in the India battery storage market.
By Revenue Stream: Capacity Charge Contracts Lead While Ancillary Services and Firming Grow Fastest
Capacity charge contracts lead the India grid-scale battery storage market revenue mix, accounting for approximately 71% of contracted value, driven by fixed monthly payments that are independent of dispatch and therefore the easiest stream to finance. Renewable firming under firm and dispatchable tenders contributes another 12%, bundling storage with solar and wind to deliver contracted round-the-clock supply. Ancillary services and energy arbitrage are the fastest growing streams within the India grid-scale battery storage market, expanding at 34.5% annually, driven by tertiary reserve requirements, deviation settlement pricing, and wider time-of-day spreads in the day-ahead market. Peak shaving and demand charge management account for 3%, concentrated in commercial and industrial installations. Leading developers including Tata Power Renewable Energy, JSW Energy, NTPC Green Energy, Greenko and ReNew are structuring assets to earn from more than one stream, lifting coverage ratios across the India battery storage market.
India Grid Scale Battery Storage Market by Region
Regional analysis of the India grid-scale battery storage market shows that West India and South India collectively account for approximately 65% of contracted value, driven by Gujarat (the phased GUVNL standalone programme), Maharashtra, Andhra Pradesh (the APTRANSCO 1,000 MW tender), Telangana, Tamil Nadu and Karnataka, supported by high renewable penetration and active state procurement. North India contributes around 21% of demand, led by Rajasthan, Uttar Pradesh, Haryana and Punjab, where curtailment management and four-hour overnight support are shaping tender design. East India accounts for 8%, supported by the West Bengal 2 GWh auction and distribution reform in Odisha, while Central India accounts for 6%, led by Madhya Pradesh and Chhattisgarh, where early viability gap funding projects are under construction. In 2025, awards and construction activity by NTPC Green Energy in West Bengal, NLC India Renewables in Gujarat, and several developers in Andhra Pradesh reinforced regional delivery hubs across the India battery storage market.
Recent Developments in the India Grid Scale Battery Storage Market
- The India grid-scale battery storage market recorded strong momentum in awards and commissioning during 2025 and 2026. Operational capacity reached 8.5 GWh by the middle of 2026 after 7.9 GWh was added in the first half alone, an eleven-fold increase over twelve months. Cumulative commissioned capacity stood near 758 MWh at the end of 2025, against 102 GWh tendered during that year across 69 tenders. Cumulative tendered volume reached 281 GWh by mid-2026, with 105 GWh under execution, 110 GWh still in tendering and 53 GWh cancelled. Operational capacity is expected to reach 14 GWh by December 2026, keeping the build-out on the trajectory set by the National Electricity Plan.
- Policy support deepened materially across the India grid-scale battery storage market. The Union Cabinet approved INR 5,400 crore from the Power System Development Fund on 14 May 2026 to support 30 GWh of new battery storage, following the September 2023 scheme that covered 4,000 MWh. Viability gap funding was revised to INR 18 lakh per MWh from July 2025, down from INR 27 lakh per MWh, reflecting lower delivered system cost. Cumulative commitment now stands near INR 9,100 crore across 43.2 GWh, with a 20% domestic value addition requirement attached to the second tranche. These measures are strengthening domestic supply and supporting the India battery storage market forecast 2032.
- Auction activity has broadened the developer base in the India grid-scale battery storage market. GUVNL concluded its Phase IX auction for 450 MW and 900 MWh at INR 2,31,989 per MW per month, awarded to NLC India Renewables and Sun Drops Energia. NTPC Green Energy secured 200 MW and 800 MWh in West Bengal at INR 4.35 lakh per MW per month. Kerala contracted 250 MW and 500 MWh over 15 years, with Power Grid Corporation and Oriana Power among the successful bidders. The Gujarat regulator’s approval of INR 1,89,000 per MW per month for 1.665 GW marked the first clear upward correction in discovered pricing, strengthening long-term competitive positioning in the India battery storage market forecast 2032.
Key Companies in the India Grid Scale Battery Storage Market
- Tata Power Renewable Energy Limited
- JSW Energy Limited (JSW Neo Energy Limited)
- NTPC Green Energy Limited
- Adani Green Energy Limited
- ReNew Energy Global Plc
- Greenko Energies Private Limited
- NLC India Renewables Limited
- Power Grid Corporation of India Limited
- Larsen & Toubro Limited (L&T Energy GreenTech)
- Sterling and Wilson Renewable Energy Limited
- Waaree Energies Limited (Waaree ESS)
- Exide Energy Solutions Limited
- Oriana Power Limited
| By Technology Type | By Revenue Stream | By Storage Duration | By Contracting | By End-User |
| LFP NMC Sodium-Ion Flow Advanced Lead-Acid Others | Capacity Charge Firming Arbitrage Ancillary Peak Shaving Deviation Others | One-Hour Two-Hour Four-Hour Six-Hour & Above Hybrid Co-Located | Central Agency State Discom Utility Owned Co-Located Merchant Captive | Distribution Utilities Transmission Operators IPPs & Developers C&I Consumers |
Report Scope
In this report, the India Grid-Scale Battery Storage Revenue & Bankability Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Technology Type
- Lithium Iron Phosphate (LFP)
- Nickel Manganese Cobalt (NMC)
- Sodium-Ion Batteries
- Flow Batteries
- Advanced Lead-Acid
- Others
- By Revenue Stream
- Capacity Charge Contracts
- Renewable Firming (FDRE)
- Energy Arbitrage
- Ancillary Services
- Peak Shaving & Demand Charge Management
- Deviation Settlement & Imbalance
- Others
- By Storage Duration
- One-Hour Systems
- Two-Hour Systems
- Four-Hour Systems
- Six-Hour & Above
- Hybrid Co-Located Systems
- By Contracting Model
- Central Agency Tenders (SECI, NVVN, NTPC)
- State Discom Tenders
- Utility Owned & Operated
- Generator Co-Located (Solar Plus Storage)
- Merchant & Bilateral Trading
- Captive & Open Access
- By End-User
- Distribution Utilities
- Transmission & Grid Operators
- Independent Power Producers & Developers
- Commercial & Industrial Consumers
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Grid-Scale Battery Storage Revenue & Bankability Market, including business overview, project portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging storage developers, specialty system integrators, regional engineering contractors, or niche state-level independent power producers.
For a free sample of the India Grid-Scale Battery Storage Revenue & Bankability Market report, customised insights or delivery timelines, submit your query here
India Grid-Scale Battery Storage Revenue & Bankability Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Technology Type
- By Revenue Stream
- By Storage Duration
- By Contracting Model
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Grid-Scale Battery Storage Market
- India Grid-Scale Battery Storage Market Insights
- Market Dynamics
- Growth Drivers
- Viability gap funding and central policy support making grid-scale battery storage bankable across India.
- Renewable additions, evening peak deficits and round-the-clock procurement fuelling contracted battery storage demand.
- Falling delivered costs, competitive reverse auctions and domestic cell manufacturing strengthening project returns.
- Restraints
- Aggressive tariff bidding and thin margins weakening project viability and lender confidence in battery storage assets.
- Discom payment delays, weak payment security and offtaker credit risk constraining battery storage bankability.
- Import dependence for cells, currency volatility and rising battery prices pressuring installed capital costs.
- Opportunities
- Ancillary services, frequency support and resource adequacy opening revenue beyond fixed capacity charges.
- Four-hour and longer-duration storage contracts supporting overnight balancing and higher-value agreements.
- Domestic cell manufacturing and 20% value addition norms deepening the battery storage supply base in India.
- Challenges
- Grid connectivity, land acquisition and transmission clearance delays slowing battery storage commissioning.
- Agreement signing delays and tender cancellations disrupting the award-to-commissioning pipeline in India.
- Limited operating history, degradation risk and warranty enforcement complicating long-term lender diligence.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Raw Materials (lithium, iron phosphate, graphite, copper, aluminium, electrolyte)
- Cell & Module Manufacturers (Exide Energy Solutions, Amara Raja, imported cell suppliers)
- Power Conversion & Balance of Plant Suppliers (inverters, transformers, cooling, fire safety)
- System Integrators & Container Assembly (DC blocks, energy management software, controls)
- EPC Contractors & Grid Interconnection Specialists (substation, evacuation, protection)
- Project Developers & Independent Power Producers (Tata Power, JSW Energy, NTPC Green, ReNew)
- Lenders, Funds & Credit Enhancement Providers (banks, NBFCs, InvITs, guarantee facilities)
- Procurement Agencies & Distribution Utilities (SECI, NVVN, NTPC, GUVNL, state discoms)
- Operations, Maintenance & Asset Management Providers (dispatch optimisation, warranty)
- End-Users (grid operators, distribution utilities, commercial and industrial consumers)
- India Grid-Scale Battery Storage Market: Regulatory Framework
- India Grid-Scale Battery Storage Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (GWh)
- Market Share & Forecast
- By Technology Type
- Lithium Iron Phosphate (LFP)
- Nickel Manganese Cobalt (NMC)
- Sodium-Ion Batteries
- Flow Batteries
- Advanced Lead-Acid
- Others
- By Revenue Stream
- Capacity Charge Contracts
- Renewable Firming (FDRE)
- Energy Arbitrage
- Ancillary Services
- Peak Shaving & Demand Charge Management
- Deviation Settlement & Imbalance
- Others
- By Storage Duration
- One-Hour Systems
- Two-Hour Systems
- Four-Hour Systems
- Six-Hour & Above
- Hybrid Co-Located Systems
- By Contracting Model
- Central Agency Tenders (SECI, NVVN, NTPC)
- State Discom Tenders
- Utility Owned & Operated
- Generator Co-Located (Solar Plus Storage)
- Merchant & Bilateral Trading
- Captive & Open Access
- By End-User
- Distribution Utilities
- Transmission & Grid Operators
- Independent Power Producers & Developers
- Commercial & Industrial Consumers
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Grid-Scale Battery Storage Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Tata Power Renewable Energy Limited
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- JSW Energy Limited (JSW Neo Energy Limited)
- NTPC Green Energy Limited
- Adani Green Energy Limited
- ReNew Energy Global Plc
- Greenko Energies Private Limited
- NLC India Renewables Limited
- Power Grid Corporation of India Limited
- Larsen & Toubro Limited (L&T Energy GreenTech)
- Sterling and Wilson Renewable Energy Limited
- Waaree Energies Limited (Waaree ESS)
- Exide Energy Solutions Limited
- Oriana Power Limited
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India grid-scale battery storage market and what is its growth forecast?
Ans: The India grid-scale battery storage market is valued at USD 3,680 million in 2025 and is projected to reach USD 12,620 million by 2032, growing at a CAGR of 19.2% on a contracted capacity value basis.
2. Which segments are driving demand in the India grid-scale battery storage market?
Ans: Capacity charge contracts lead with 71% of contracted revenue, while ancillary services and four-hour systems are the fastest growing segments, supported by frequency support needs, overnight balancing, and wider price spreads.
3. What are the key drivers of growth in the India grid-scale battery storage market?
Ans: Key drivers include viability gap funding of INR 5,400 crore for 30 GWh, rising evening peak deficits, falling delivered system cost, competitive reverse auctions, and domestic cell manufacturing under the advanced chemistry cell programme.
4. Which regions are driving growth in the India grid-scale battery storage market?
Ans: West India and South India lead with around 65% of contracted value, driven by Gujarat, Maharashtra, Andhra Pradesh, Telangana, and Tamil Nadu. North India follows at 21%, led by Rajasthan and Uttar Pradesh.
5. What are the latest trends in the India grid-scale battery storage market?
Ans: Latest trends include the shift to four-hour storage contracts, upward tariff correction toward INR 1,89,000 per MW per month, domestic cell localisation, and revenue stacking across capacity, arbitrage, and ancillary services.