India Silicones Market: Construction Glazing, Electronics and Electric Vehicle Manufacturing and Domestic Formulation Capacity Power Structural Growth, Forecasts 2032
- Chemicals & Advanced Materials
- Sep 2026
- Pages 140
- Report Format: pdf
- Report Price: $1800 USD
India’s silicones market is witnessing strong structural growth, driven by record public infrastructure spending, expanding commercial facade, glazing, and housing construction, accelerating electric vehicle, electronics, and solar manufacturing under PLI, rising personal care, medical device, and textile finishing demand, growing requirements for thermal management, high voltage insulation, and weatherproofing, and rising interest from domestic and global silicone majors investing in India-specific formulation capacity, compounding lines, technical centres, and low cyclic, bio-based, and medical grade platforms.
Report Description
| Study Duration | 2021-2032 |
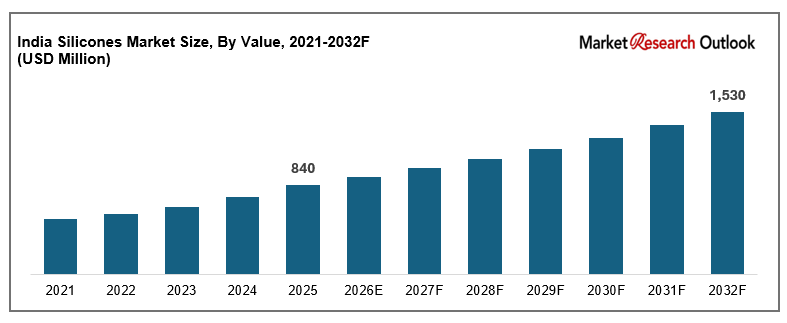
| Market Size (2025) | USD 840 Million |
| CAGR (2026-2032) | 8.9% |
| Leading Segment | Silicone Elastomers (Sealants & Moulded Parts) |
| Fastest Growing Segment | Liquid Silicone Rubber & Thermal Management Gels |
| Market Size (2032) | USD 1,530 Million |
Source: Market Research Outlook
Market Overview: India Silicones Market
The India silicones market size is witnessing rapid expansion, driven by record construction and facade glazing activity, growing electronics, appliance, and solar manufacturing, rising electric vehicle thermal management and high voltage insulation demand, expanding personal care, healthcare, and textile applications, increasing demand for durable, weatherproof, and thermally stable materials, and major formulation capacity additions by domestic and global players. Valued at USD 840 million in 2025 and projected to reach USD 1,530 million by 2032, growing at a CAGR of 8.9%, the India silicones market growth is being fuelled by strong demand from construction contractors, electronics manufacturers, and automotive suppliers, alongside BIS quality control orders on sealants and PLI incentives that are shifting demand toward domestically formulated products. Silicone elastomers lead consumption across sealants, gaskets, tubing, and moulded parts, while liquid silicone rubber and thermal management gels are emerging as the fastest growing categories. Shifting formulator preferences toward low cyclic chemistries, growing electric vehicle and electronics needs, and rising demand for medical and food grade materials are reshaping the supply landscape. As domestic formulators including Wacker Metroark Chemicals, Supreme Silicones, Anabond, Elantas Beck, and Pidilite expand compounding and sealant capacity, and global players including Dow, Momentive, Elkem, Shin-Etsu, Evonik, and KCC scale distribution and technical service networks, the India silicones market is evolving into a specification-led, innovation-driven, and increasingly self-reliant specialty materials ecosystem with strong long-term growth potential.
Key Report Takeaways: India Silicones Market
- The India silicones market size is projected to grow from USD 840 million in 2025 to USD 1,530 million by 2032, registering a strong CAGR of 8.9%, driven by accelerated construction and glazing activity, rising electronics, electric vehicle, and solar demand, and the structural shift toward domestically formulated silicone products across industrial India.
- Silicone elastomers dominate the India silicones market, accounting for 39% of total value in 2025, driven by their versatility across structural glazing sealants, weatherproofing, electrical insulators, automotive gaskets, medical tubing, and consumer moulded parts, the formulation presence of Wacker Metroark Chemicals, Dow, Momentive, and Elkem, and rising demand across construction, electronics, and automotive channels.
- Liquid silicone rubber and thermal management gels are emerging as the fastest growing segments in the India silicones market, expected to grow at 12.1% annually as electric vehicle makers, electronics assemblers, and medical device producers reshape sourcing strategies toward two shot moulded parts, gap fillers, and potting compounds across Tamil Nadu, Maharashtra, and Gujarat clusters.
- Rapid scaling of end-use activity, with the national capital expenditure outlay at INR 11.21 lakh crore in FY26, mobile phone output reaching INR 5.25 lakh crore, and solar module capacity crossing 100 GW in FY25, is structurally expanding the India silicones market across construction, electronics, and energy categories.
- Rising investments by domestic and global majors such as Wacker Metroark Chemicals, Dow, Momentive, Elkem, Shin-Etsu, Supreme Silicones, and Anabond in formulation capacity, compounding lines, technical centres, and low cyclic, medical, and thermal management grades, together with BIS quality control orders on sealants and PLI incentives for electronics, batteries, and solar, are strengthening local supply and supporting the India silicones market forecast 2032.
Key Market Drivers: India Silicones Market
Rapid Growth in Construction, Facade Glazing, and Infrastructure Activity Driving Silicone Sealant and Coating Consumption Across India
Growth in the India silicones market is being driven by record public infrastructure spending, rapid commercial and residential construction, and rising consumption of structural glazing sealants, weatherproofing sealants, silicone coatings, and water repellent emulsions across tier-1, tier-2, and tier-3 cities. India’s Union Budget raised capital expenditure to INR 11.21 lakh crore for FY26, sustaining metro rail, airport, and commercial corridor construction, while office space absorption across the top seven cities exceeded 70 million square feet in 2025 and green building certified floor area under IGBC crossed 12 billion square feet. Building and construction absorbs 27% of silicone consumption in India, led by Dow, Wacker Metroark Chemicals, Momentive, Pidilite, Sika, and McCoy Soudal supplying facade contractors, glass processors such as Saint-Gobain and Asahi India Glass, and waterproofing applicators. Structural glazing and weatherproofing silicone sealants are priced between INR 450 and INR 1,100 per kilogram, while silicone based water repellents and roof coatings command INR 350 to INR 700 per kilogram. Per capita silicone consumption in India remains below 0.16 kilograms per year compared with more than 1.5 kilograms in developed markets, indicating significant long-term headroom. Rising data centre, airport, and high rise construction and the shift from acrylic and polyurethane sealants to silicone in facade applications are creating strong structural pull-through demand across the India silicones market.
Source: Market Research Outlook
Electric Vehicle, Electronics, and Solar Manufacturing Expansion Creating Structural Demand for Silicone Elastomers, Gels, and Encapsulants
The India silicones market is benefiting from sustained growth in electric vehicle, electronics, and solar manufacturing, with electrical and electronics accounting for 19% of demand in 2025, automotive and transportation another 16%, and energy 9%. Mobile phone production reached INR 5.25 lakh crore in FY25 under the electronics PLI scheme, electric vehicle sales exceeded 2 million units, and solar module manufacturing capacity crossed 100 GW, with each electric passenger car consuming 4 to 6 kilograms of silicones across battery thermal gap fillers, potting gels, high voltage cable insulation, gaskets, and hoses, and each solar module consuming 0.4 to 0.6 kilograms of silicone sealant, potting, and junction box encapsulant. Thermally conductive gap fillers, self-levelling potting gels, and flame retardant liquid silicone rubber are being qualified by Tata Motors, Mahindra, Ola Electric, Ather, Dixon, Havells, Polycab, Waaree, and Adani Solar for battery packs, chargers, inverters, LED lighting, and connectors. Battery cell projects under the advanced chemistry cell PLI scheme with an outlay of INR 18,100 crore are adding demand for silicone based cell-to-pack adhesives and fire barriers. Thermal management and electronics grade silicones command realisations of INR 1,200 to INR 3,500 per kilogram, compared with INR 380 to INR 520 per kilogram for general purpose high consistency rubber, supporting mix improvement across the Indian silicones sector. Data centre cooling, 5G infrastructure, and grid investment of INR 9.15 lakh crore planned through 2032 are adding further demand for silicone insulators, coatings, and encapsulants.
Domestic Formulation Capacity Additions, Compounding Investments, and Import Substitution Strengthening Local Supply of Silicones
Domestic formulation capacity additions, compounding investments, and import substitution are a major catalyst for the India silicones market, with imports still supplying 100% of siloxane monomers and intermediates and 42% of finished silicone products consumed in India in 2024. Wacker Metroark Chemicals operates an integrated silicone specialties plant at Amtala in West Bengal producing emulsions, fluids, elastomers, and sealants, and has expanded capacity and technical laboratories across 2023 to 2025. Supreme Silicones produces high consistency and liquid silicone rubber compounds at Pune, Anabond formulates RTV sealants and adhesives at Chennai, Elantas Beck supplies silicone based electrical insulation resins from Pune, Pidilite markets silicone sealants across 680 thousand outlets, and CHT India formulates textile and industrial silicone specialties. Global majors including Dow, Momentive, Elkem, Shin-Etsu, Evonik, and KCC operate warehousing, blending, and technical centres in Maharashtra, Gujarat, Tamil Nadu, and Delhi NCR that supplied 46% of specialty grades in 2025. BIS quality control orders on silicone sealants and adhesives and the PLI schemes for electronics, advanced chemistry cells, solar modules, and medical devices are tightening import compliance and structurally expanding India silicones market growth across all major end-user categories through 2032.
Key Market Challenges: India Silicones Market
Complete Dependence on Imported Siloxane Monomers and Intermediates Exposing Formulators to Price and Supply Volatility
The India silicones market continues to face challenges around upstream dependence, with India having no domestic methylchlorosilane or siloxane monomer production, so D4, D5, DMC, silanol fluids, and vinyl and hydride intermediates are entirely sourced from China, Korea, Thailand, Japan, Germany, and the United States. India imports its full siloxane requirement of 165 thousand tonnes, with Chinese producers including Hoshine, Dongyue, Zhejiang Xinan, and Tangshan Sanyou supplying more than 55% of volume. DMC prices moved between USD 1,900 and USD 4,800 per tonne during 2021 and 2025, silicon metal ranged between USD 1,800 and USD 4,500 per tonne, and finished HCR moved between USD 3.2 and USD 6.5 per kilogram, compressing formulator gross margins by 400 to 900 basis points in volatile quarters. Chinese export restrictions on silicon metal and energy driven production cuts in 2021 and 2022 stretched lead times to 10 to 14 weeks, and platinum catalyst and fumed silica supply is also import dependent. Rupee depreciation, anti-dumping actions on intermediates, and ocean freight volatility add further cost uncertainty for downstream formulators. India’s continued dependence on imported siloxane intermediates limits pricing flexibility across the Indian silicones sector.
Price Competition from Low Cost Imports and Thin Conversion Margins Limiting Profitability of Smaller Silicone Formulators
The India silicones market faces structural complexity from variations in import pricing, product quality, and channel margins across different regions. Chinese and Korean producers continue to offer finished silicone sealants, HCR, and moulded parts at prices 10% to 20% below domestic realisations, and unorganized sealant fillers supply extended, low solids silicone tubes through hardware stores at prices 20% to 30% below branded equivalents. Average EBITDA margins for standalone Indian silicone formulators and moulders range between 8% and 13%, and working capital cycles stretch to 90 to 120 days because imported intermediates must be paid upfront while construction, electronics, and automotive customers demand extended credit. Differential availability of application testing, USP and FDA certification, and technical service across states creates operational complexity for players such as Wacker Metroark Chemicals, Dow, Momentive, Elkem, Supreme Silicones, and Anabond operating pan-India. While BIS quality control orders on sealants are improving pricing discipline for imported and unorganized products, import competition remains a near-term challenge for the domestic silicones industry.
Regulatory Scrutiny on Cyclic Siloxanes, VOC Emissions, and Medical Grade Certification Restricting Conventional Silicone Formulations
The India silicones market faces practical constraints around cyclic siloxane regulation, VOC emission limits, medical certification, and reformulation costs across the value chain. The European Union restricted D4, D5, and D6 in wash-off cosmetics above 0.1% from 2020 and extended restrictions to leave-on products and other uses from 2027, and Indian exporters of personal care ingredients, textile softeners, and antifoams must qualify low cyclic grades that add 8% to 15% to raw material cost. Central Pollution Control Board norms and green building codes are pushing VOC content in construction sealants and coatings below 250 grams per litre, while solvent based silicone water repellents and release coatings still carry 400 to 600 grams per litre. BIS quality control orders on silicone sealants and adhesives, the Medical Devices Rules, and USP Class VI and ISO 10993 requirements for healthcare grades are tightening compliance for both importers and small formulators. Reformulating to low cyclic, waterborne, or medical grade systems adds 12% to 20% to raw material cost and requires requalification with brands and OEMs. Smaller formulators face additional compliance complexity under REACH registration and FDA food contact rules for export grades. Low cyclic fluids, waterborne emulsions, and bio-based and recycled silicone systems are emerging as solutions to differentiate, but higher pricing and limited application know-how remain barriers to widespread adoption across the domestic silicones industry.
Key Market Trends: India Silicones Market
Rapid Adoption of Low Cyclic, Bio-Based, and Recycled Silicone Systems in India
The India silicones market is undergoing a clear technology shift toward low cyclic, bio-based, and recycled silicone systems, with these advanced variants expected to capture 17% of new formulations by 2028. Low cyclic fluids and emulsions with D4, D5, and D6 content below 0.1% are replacing conventional grades in personal care, textile, and antifoam applications, while bio-based silicone hybrids using renewable carbon side chains cut cradle-to-gate carbon footprint by 15% to 30%. Recycled silicone from post-industrial moulding scrap and depolymerised siloxane recovered from waste rubber is entering sealant, coating, and moulded part applications at 15% to 25% below prime pricing. Leading domestic and global players including Wacker Metroark Chemicals, Dow, Momentive, Elkem, Shin-Etsu, Evonik, and CHT have introduced low cyclic, waterborne, and circular ranges for the Indian market through 2024 and 2025. Chemical recycling of silicone elastomer scrap back to siloxane monomers is also gaining traction, particularly in Maharashtra and Tamil Nadu where automotive and electronics moulders are preparing for extended producer responsibility obligations. This product transition is reinforcing the India silicones market forecast 2032 across both consumer and industrial categories.
Growth of Electric Vehicle Thermal Management, High Voltage, and Battery Applications in the India Silicones Market
A clear shift toward electric vehicle thermal management, high voltage insulation, and battery applications is reshaping the India silicones market, particularly in the automotive and energy segments. India’s electric vehicle sales exceeded 2 million units in FY25 across two wheelers, three wheelers, passenger cars, and buses, and each electric passenger car consumes 4 to 6 kilograms of silicones through thermally conductive gap fillers, potting gels, cell-to-pack adhesives, fire barrier coatings, high voltage cable insulation, and gaskets, compared with 1.5 to 2.5 kilograms in a comparable internal combustion vehicle. Lithium ion cell manufacturing capacity is expected to exceed 50 gigawatt hours by 2028 under the advanced chemistry cell PLI scheme, with each gigawatt hour consuming 20 to 30 tonnes of silicone thermal interface materials, encapsulants, and adhesives. Flame retardant liquid silicone rubber, ceramifiable silicone fire barriers, and thermally conductive gels with conductivity of 2 to 6 watts per metre kelvin are being qualified by Tata Motors, Mahindra, Ola Electric, Ather, TVS, and Bajaj alongside tier suppliers such as Motherson, Uno Minda, and TE Connectivity India, while cell and pack makers including Exide Energy, Amara Raja, and Ola Cell Technologies are adding silicone demand for cell holders and module sealing. Electric vehicle and battery applications accounted for 6% of silicone demand in 2025 and are expected to reach 13% by 2032, with OEMs increasingly preferring locally formulated grades to shorten qualification cycles.
Capacity Expansion, Compounding Localisation, and Import Substitution by Domestic and Global Silicone Majors
A wave of capacity expansion, compounding localisation, and import substitution is reshaping the India silicones market supply landscape. Combined India-focused capital expenditure announcements in silicone formulation, compounding, sealant packing, and technical centres exceeded USD 300 million across 2023 to 2025. Wacker Metroark Chemicals expanded emulsion, fluid, and elastomer capacity and laboratories at Amtala, Supreme Silicones added HCR and LSR compounding lines at Pune, Anabond scaled RTV sealant and adhesive capacity at Chennai, Elantas Beck expanded insulation resin output at Pune, Pidilite extended silicone sealant reach through its dealer network, and Dow, Momentive, Elkem, Shin-Etsu, Evonik, and KCC have strengthened blending, warehousing, and application laboratories in Maharashtra, Gujarat, Tamil Nadu, and Delhi NCR. BIS quality control orders on sealants and adhesives, PLI allocations for electronics, advanced chemistry cells, solar modules, and medical devices, and green building specifications have structurally favoured organized domestic supply. Combined with electric vehicle, electronics, and construction capacity additions driving specialty grade demand and export orders to the Middle East, Africa, and Southeast Asia, these developments are reinforcing the India silicones market forecast 2032 across the entire value chain.
Segmental Insights: India Silicones Market
By End-User: Building & Construction Segment Dominates the India Silicones Market
The building and construction end-user segment dominates the India silicones market, accounting for 27% of total value in 2025, driven by record infrastructure spending, growing facade and glazing consumption, and improving weatherproofing economics. Structural glazing and weatherproofing sealants, silicone roof coatings, water repellent emulsions, and sanitary sealants are the dominant products within this segment, with facade, glazing, and expansion joint sealants capturing 48% of construction related silicone purchases. The electrical and electronics segment contributes another 19% of demand, driven by potting gels, encapsulants, LED lighting, insulators, cable accessories, and keypads across Tamil Nadu, Uttar Pradesh, Karnataka, and Gujarat clusters. The automotive and transportation segment accounts for 16%, led by gaskets, hoses, thermal gap fillers, and high voltage insulation, while personal care and consumer goods contributes 14% through hair care, skin care, and antiperspirant fluids and elastomers, energy adds 9% through solar sealants, wind blade coatings, and battery materials, healthcare and medical adds 8% through tubing, catheters, and implant grade elastomers, and industrial and others adds 7% through antifoams, release agents, and textile finishes. In 2025, leading silicone players including Wacker Metroark Chemicals, Dow, Momentive, Elkem, Pidilite, and Anabond scaled up construction and infrastructure focused sealant and coating supply, reinforcing segment dominance in the Indian silicones sector.
By Product Type: Silicone Elastomers Lead While Liquid Silicone Rubber and Thermal Management Gels Grow Fastest
Silicone elastomers lead the India silicones market product landscape, accounting for 39% of total value, driven by their balanced durability, weather resistance, and electrical performance across sealants, gaskets, tubing, insulators, keypads, and moulded parts. Silicone fluids and oils contribute another 28%, primarily across personal care, textile softeners, antifoams, lubricants, and release agents, while silicone resins account for 11% through high temperature coatings, electrical insulation, and cosmetic film formers. Liquid silicone rubber and thermal management gels are the fastest growing categories within the Indian silicones sector, expanding at 12.1% annually, driven by two shot moulding of medical, consumer, and automotive parts, battery gap fillers and potting for electric vehicles, and encapsulation demand from electronics and solar assembly. Silicone emulsions and dispersions account for 9% of the market through textile, construction, and personal care applications, gels and encapsulants contribute 7%, and silanes, siloxane intermediates, and other specialties add 6%, with the medical, semiconductor, and battery grade segment expected to grow rapidly through 2032. Leading manufacturers including Wacker Metroark Chemicals, Dow, Momentive, Elkem, Shin-Etsu, Evonik, KCC, and Supreme Silicones have aligned product portfolios to this mix, driving specialty silicone adoption across the India silicones market.
Regional Insights: India Silicones Market
Regional analysis of the India silicones market shows that West India and South India collectively account for 62% of total silicone value, driven by Maharashtra (Mumbai and Pune construction, automotive, electronics, and compounding belt, home to Supreme Silicones and Elantas Beck plants and Dow and Momentive centres), Gujarat (Sanand and Ahmedabad automotive, appliance, and solar cluster, Dahej and Ankleshwar chemical belt), Tamil Nadu (Chennai and Hosur automotive, electronics, and electric vehicle cluster with Anabond and Elkem facilities), Karnataka (Bengaluru aerospace, medical device, and electronics), and Telangana (Hyderabad pharmaceutical and medical device parks), supported by formulation plants, ports, and strong industrial consumption levels. North India contributes 25% of demand, led by Delhi NCR, Haryana, Uttar Pradesh, Rajasthan, and Punjab, supported by commercial facade construction in Gurugram and Noida, automotive seating and assembly clusters, mobile phone and appliance manufacturing, and personal care production. Central and East India together account for 13% of demand, supported by West Bengal (Wacker Metroark Chemicals at Amtala), Madhya Pradesh, Odisha, and Jharkhand, where construction, textile, and industrial demand is accelerating. In 2025, capacity and distribution operations by Wacker Metroark Chemicals across West Bengal, Supreme Silicones and Elantas Beck across Maharashtra, Anabond across Tamil Nadu, Pidilite across Maharashtra and Gujarat, and Dow, Momentive, Elkem, and Shin-Etsu distribution across Maharashtra, Gujarat, Tamil Nadu, and Delhi NCR reinforced regional supply hubs, supporting closer execution of construction, electronics, and automotive projects across the India silicones market.
Recent Developments: India Silicones Market
- The India silicones market witnessed strong momentum in policy support and capacity progress during 2024 and 2025. BIS quality control orders on silicone sealants and adhesives moved toward implementation, the advanced chemistry cell PLI scheme with an outlay of INR 18,100 crore advanced battery cell projects by Ola Cell Technologies, Reliance New Energy, and Amara Raja, and the European Union confirmed extended restrictions on D4, D5, and D6 in leave-on cosmetics and other applications from 2027, accelerating low cyclic reformulation among Indian exporters. Domestic silicone consumption is projected to reach 215 thousand tonnes in 2025 and 385 thousand tonnes by 2032, growing at 8.7% annually in volume terms, while solar module capacity crossed 100 GW and electric vehicle sales exceeded 2 million units in FY25.
- Domestic and global silicone majors have deepened India-focused capacity expansion. Wacker Metroark Chemicals expanded emulsion, fluid, and elastomer capacity and technical laboratories at Amtala in West Bengal, Supreme Silicones added high consistency and liquid silicone rubber compounding lines at Pune, Anabond scaled RTV sealant and adhesive capacity at Chennai, Elantas Beck expanded silicone insulation resin output at Pune, and Pidilite extended silicone sealant distribution through its dealer network. Dow, Momentive, Elkem, Shin-Etsu, Evonik, and KCC strengthened blending, warehousing, and application laboratories across Maharashtra, Gujarat, Tamil Nadu, and Delhi NCR. These developments are strengthening domestic supply and supporting the India silicones market forecast 2032.
- Construction, electronics, and electric vehicle momentum has gained strong traction in the India silicones market. In 2025, facade contractors and glass processors including Saint-Gobain and Asahi India Glass specified structural glazing silicones for metro, airport, and commercial projects, electric vehicle makers including Tata Motors, Mahindra, Ola Electric, Ather, and TVS qualified thermal gap fillers, potting gels, and fire barrier silicones for battery packs, electronics assemblers including Dixon, Havells, and Polycab scaled encapsulant and cable accessory usage under PLI, and solar makers including Waaree and Adani Solar expanded silicone sealant and potting consumption. Strategic partnerships between silicone producers, formulators, OEMs, and construction chemical companies are positioning India as one of the most actively scaling silicone markets globally, strengthening long-term competitive positioning in the India silicones market forecast 2032.
Key Market Players: India Silicones Market
- Wacker Metroark Chemicals Pvt. Ltd.
- Dow Chemical International Pvt. Ltd.
- Momentive Performance Materials (India) Pvt. Ltd.
- Elkem South Asia Pvt. Ltd.
- Shin-Etsu Silicones India Pvt. Ltd.
- Evonik India Pvt. Ltd.
- KCC Corporation
- Hoshine Silicon Industry Co., Ltd.
- Supreme Silicones India Pvt. Ltd.
- Anabond Ltd.
- Pidilite Industries Ltd.
- Elantas Beck India Ltd.
- CHT India Pvt. Ltd.
| By Product Type | By Form | By Processing | By Distribution | By End-User |
| Elastomers Fluids & Oils Resins Emulsions & Dispersions Gels & Encapsulants Silanes & Intermediates Others | Sealants & Adhesives Moulded & Extruded Parts Coatings & Release Agents Antifoams & Additives Personal Care Ingredients Others | Compression & Injection Moulding Extrusion & Calendering Dispensing & Coating | Direct Sales Distributors & Dealers Traders & Importers Online B2B Platforms Formulators & Compounders | Building & Construction Electrical & Electronics Automotive Personal Care Healthcare Energy Industrial |
Report Scope
In this report, the India Silicones Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Product Type
- Silicone Elastomers (HCR, LSR, RTV)
- Silicone Fluids & Oils
- Silicone Resins
- Silicone Emulsions & Dispersions
- Silicone Gels & Encapsulants
- Silanes & Siloxane Intermediates
- Others
- By Form
- Sealants & Adhesives
- Moulded & Extruded Parts
- Coatings & Release Agents
- Antifoams & Additives
- Personal Care Ingredients
- Others
- By Processing Technology
- Compression & Injection Moulding
- Extrusion & Calendering
- Dispensing & Coating
- By Distribution Channel
- Direct Sales
- Distributors & Dealers
- Traders & Importers
- Online B2B Platforms
- Formulators & Compounders
- By End-User
- Building & Construction
- Electrical & Electronics
- Automotive & Transportation
- Personal Care & Consumer Goods
- Healthcare & Medical
- Energy (Solar, Wind, Battery)
- Industrial & Others
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Silicones Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging domestic silicone formulators and sealant packers, rubber moulders and extruders, regional distributors, or niche medical, personal care, and thermal management grade importers.
The India Silicones Market report is part of our ongoing research coverage. For early access, customised insights, or to confirm the release timeline, please contact our team at sarita@marketresearchoutlook.com
Table of Contents
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Product Type
- By Form
- By Processing Technology
- By Distribution Channel
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Silicones Market
- India Silicones Market Insights
- Market Dynamics
- Growth Drivers
- Rapid growth in construction, facade glazing, and infrastructure activity driving silicone sealant and coating consumption across India.
- Electric vehicle, electronics, and solar manufacturing expansion creating structural demand for silicone elastomers, gels, and encapsulants.
- Domestic formulation capacity additions, compounding investments, and import substitution strengthening local supply of silicones.
- Restraints
- Complete dependence on imported siloxane monomers and intermediates exposing formulators to price and supply volatility.
- Price competition from low cost imports and thin conversion margins limiting profitability of smaller silicone formulators.
- Regulatory scrutiny on cyclic siloxanes, VOC emissions, and medical grade certification restricting conventional silicone formulations.
- Opportunities
- Bio-based, low cyclic, and recycled silicone systems opening premium formulation opportunities across urban India.
- EV battery thermal management, high voltage insulation, and electronics encapsulation supporting next generation silicone growth.
- Medical device, semiconductor, and personal care manufacturing under PLI creating new high purity silicone demand.
- Challenges
- Intense competition from unorganized sealant fillers and low priced imported silicone rubber and finished parts.
- Limited domestic availability of siloxane monomers, specialty silanes, and platinum catalyst systems.
- Maintaining consistent cure, purity, and performance at scale across diverse Indian climatic and processing conditions.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Raw Materials (silicon metal, methyl chloride, methylchlorosilanes, D4, D5, DMC, silanol fluids, fumed silica)
- Silicone Polymer & Intermediate Manufacturers (Dow, Wacker, Momentive, Shin-Etsu, Elkem, Hoshine, KCC)
- Additive, Filler & Catalyst Suppliers (fumed silica, platinum catalysts, crosslinkers, pigments, flame retardants)
- Formulators & Compounders (Wacker Metroark, Supreme Silicones, Anabond, Elantas Beck, CHT, regional system houses)
- Quality Control, R&D & Testing Laboratories (BIS, ISO, ASTM, USP, FDA, REACH compliance testing)
- Distributors, Dealers & Traders (B2B specialty chemical distribution networks)
- Moulders, Extruders & Sealant Packers (silicone rubber parts, tubing, gaskets, cartridges, keypads)
- Construction, Electronics & Automotive OEMs (Saint-Gobain, Dixon, Havells, Maruti Suzuki, Tata Motors, Waaree)
- Personal Care, Healthcare & Textile Brands (Hindustan Unilever, Dabur, Emami, Poly Medicure, Arvind)
- End-Users (construction, electronics, automotive, personal care, healthcare, energy, textiles, industrial)
- India Silicones Market: Regulatory Framework
- India Silicones Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (Thousand Tonnes)
- Market Share & Forecast
- By Product Type
- Silicone Elastomers (HCR, LSR, RTV)
- Silicone Fluids & Oils
- Silicone Resins
- Silicone Emulsions & Dispersions
- Silicone Gels & Encapsulants
- Silanes & Siloxane Intermediates
- Others
- By Form
- Sealants & Adhesives
- Moulded & Extruded Parts
- Coatings & Release Agents
- Antifoams & Additives
- Personal Care Ingredients
- Others
- By Processing Technology
- Compression & Injection Moulding
- Extrusion & Calendering
- Dispensing & Coating
- By Distribution Channel
- Direct Sales
- Distributors & Dealers
- Traders & Importers
- Online B2B Platforms
- Formulators & Compounders
- By End-User
- Building & Construction
- Electrical & Electronics
- Automotive & Transportation
- Personal Care & Consumer Goods
- Healthcare & Medical
- Energy (Solar, Wind, Battery)
- Industrial & Others
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Silicones Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Wacker Metroark Chemicals Pvt. Ltd.
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Dow Chemical International Pvt. Ltd.
- Momentive Performance Materials (India) Pvt. Ltd.
- Elkem South Asia Pvt. Ltd.
- Shin-Etsu Silicones India Pvt. Ltd.
- Evonik India Pvt. Ltd.
- KCC Corporation
- Hoshine Silicon Industry Co., Ltd.
- Supreme Silicones India Pvt. Ltd.
- Anabond Ltd.
- Pidilite Industries Ltd.
- Elantas Beck India Ltd.
- CHT India Pvt. Ltd.
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India silicones market and what is its growth forecast?
Ans: The India silicones market is valued at USD 840 million in 2025 and is projected to reach USD 1,530 million by 2032, growing at a CAGR of 8.9%, supported by construction, electronics, electric vehicle, and personal care demand.
2. Which segments are driving demand in the India silicones market?
Ans: Silicone elastomers lead with 39% value share across sealants, gaskets, and moulded parts, while liquid silicone rubber and thermal management gels are the fastest-growing segments, driven by electric vehicle, electronics, and medical device makers
3. What are the key drivers of growth in the India silicones market?
Ans: Key drivers include record construction and facade glazing activity, electric vehicle, electronics, and solar manufacturing under PLI, growing personal care and medical device production, domestic formulation capacity additions, and BIS quality control orders on sealants.
4. Which regions are driving growth in the India silicones market?
Ans: West India and South India lead with 62% of total value, driven by Maharashtra, Gujarat, Tamil Nadu, Karnataka, and Telangana. North India and Delhi NCR also show strong construction, automotive, and electronics demand.
5. What are the latest trends in the India silicones market?
Ans: The latest trends include rapid adoption of low cyclic and bio-based silicones, electric vehicle thermal management gels and fire barriers, liquid silicone rubber for medical and consumer parts, structural glazing sealants, and formulation localisation by global majors