

Africa Power Transmission Infrastructure Investment Gap Market, 2032
- Global Markets
- Oct 2026
- Pages 140
- Report Format: pdf
- Report Price: $3000 USD
Africa’s power transmission infrastructure investment gap market is witnessing strong structural growth, driven by large renewable and gas pipelines waiting for grid capacity, weak and outage-prone national networks, Eskom’s plan for 14,500 km of new lines by 2034, the first private transmission PPPs in Kenya and South Africa, regional power pool interconnectors and development finance support that are lifting spending on lines, substations, HVDC links and grid control systems.
| Study Duration | 2021-2032 |
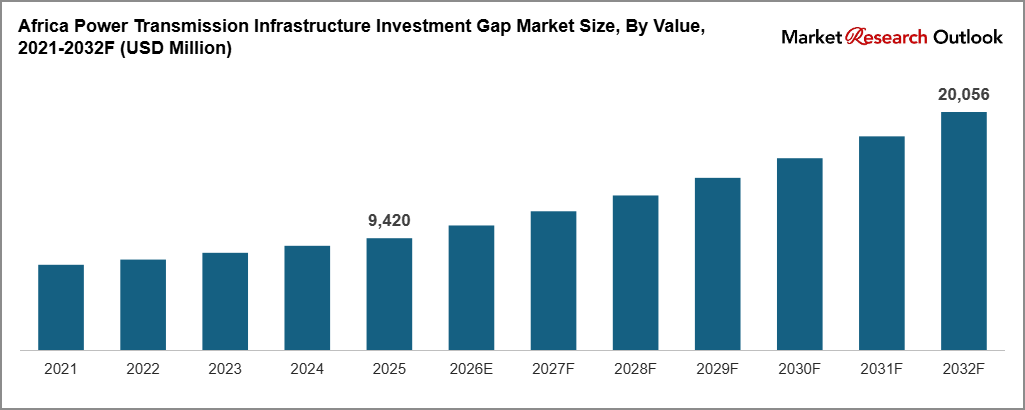
| Market Size (2025) | USD 9,420 Million |
| CAGR (2026-2032) | 11.4% |
| Leading Segment | Overhead Transmission Lines |
| Fastest Growing Segment | Independent Transmission Projects & PPP Concessions |
| Market Size (2032) | USD 20,056 Million |
Market Overview: Africa Power Transmission Infrastructure Investment Gap Market
The Africa power transmission infrastructure investment gap market size is witnessing rapid expansion, driven by renewable pipelines that cannot connect, aging and overloaded networks, frequent grid collapses, rising urban and mining demand, and new private financing routes for transmission. Valued at USD 9,420 million in 2025 and projected to reach USD 20,056 million by 2032, growing at a CAGR of 11.4%, the market is being fuelled by national utilities, independent transmission companies, power pools and development finance institutions working to close a large funding shortfall. Market Research Outlook estimates annual transmission investment needs across Africa at USD 21,500 million, more than double the USD 9,420 million spent in 2025, which defines the investment gap this market measures. Overhead transmission lines lead spending, while independent transmission projects and PPP concessions are emerging as the fastest growing financing route. About 600 million Africans still lack electricity, and among those connected, fewer than half enjoy a dependable supply. As utilities including Eskom, KETRACO, TCN, EEHC and Ethiopian Electric Power expand their grids, and suppliers including Hitachi Energy, Siemens Energy, GE Vernova and Larsen & Toubro scale African delivery, Africa’s power transmission infrastructure investment gap market is evolving into a finance-led, policy-backed and regionally integrated infrastructure category with strong long-term growth potential.
Key Report Takeaways: Africa Power Transmission Infrastructure Investment Gap Market
- Africa’s power transmission infrastructure investment gap market size is projected to grow from USD 9,420 million in 2025 to USD 20,056 million by 2032, registering a CAGR of 11.4%, driven by renewable integration needs, grid reinforcement and the structural shift toward private and blended transmission finance.
- Overhead transmission lines dominate spending, accounting for 34.8% of market value in 2025, driven by long 400 kV and 765 kV corridors that carry solar, wind and hydro power from remote resource zones to cities and mines.
- Independent transmission projects and PPP concessions are the fastest growing financing route, expected to expand at a CAGR of 27.4% through 2032 as South Africa, Kenya, Uganda and Zambia open grid build-out to private developers under availability-payment contracts.
- Eskom’s Transmission Development Plan calls for 14,500 km of new high-voltage lines to connect 56 GW of new generation by 2034, with 5,043 km targeted by the 2029 financial year and R112 billion earmarked over five years.
- Kenya’s USD 311 million transmission PPP with Africa50 and Power Grid Corporation of India, the 3,000 MW Egypt-Saudi Arabia HVDC link and the 2,000 MW Ethiopia-Kenya HVDC line are strengthening the project pipeline behind the market forecast 2032.
Key Market Drivers: Africa Power Transmission Infrastructure Investment Gap Market
Large Renewable and Gas Generation Pipelines Waiting for Grid Capacity Driving Transmission Build-Out
Growth in the market is being driven by a generation pipeline that national grids cannot yet absorb. In South Africa, Eskom expects 56 GW of new generation, mostly wind and solar, by 2034, and the best resource zones in the Northern Cape, Eastern Cape and Western Cape are far from load centres in Gauteng. Its Transmission Development Plan calls for 14,500 km of new high-voltage lines and 210 additional large transformers, with 5,043 km of lines targeted by the 2029 financial year. Egypt, Morocco and Algeria are building large solar and wind complexes in desert regions that need long 500 kV links to the coast, while Ethiopia’s Grand Ethiopian Renaissance Dam and Tanzania’s Julius Nyerere hydropower plant require new lines to move bulk power to cities and export markets. Every gigawatt of new generation typically needs hundreds of kilometres of lines and several substations, creating strong pull-through demand across Africa’s power transmission infrastructure investment gap market.
Source:
Weak, Outage-Prone National Grids and Rising Urban, Industrial and Mining Demand Requiring Grid Reinforcement
The market is benefiting from the urgent need to strengthen fragile networks. Nigeria’s national grid collapsed 12 times in 2024, and grid generation often averages near 4 GW for a population of more than 200 million, with transmission constraints limiting how much power reaches Lagos and other cities. South Africa endured its worst year of load shedding in 2023, partly because transmission limits blocked new renewable connections. Across the continent, high technical losses, overloaded transformers and single-circuit radial lines leave large areas exposed to outages. At the same time, urban populations, data centers, industrial parks and copper, cobalt, lithium and gold mines in Zambia, the Democratic Republic of Congo, Ghana and South Africa need firm, high-voltage supply. Grid reinforcement accounts for 26.7% of project purpose value in 2025, and substations and transformers make up 27.6% of infrastructure spending, lifting demand across Africa’s power transmission infrastructure investment gap market.
Private Transmission Financing Models, Development Finance and Power Pool Programs Unlocking Investment
New financing models are a major catalyst for the market. South Africa launched its Independent Transmission Projects programme to let private developers build, finance and operate transmission lines and recover costs through long-term payments. In December 2025, Kenya’s KETRACO signed a USD 311 million PPP with Africa50 and Power Grid Corporation of India to build the 180 km Lessos-Loosuk 400 kV line and the 72 km Kibos-Kakamega-Musaga 220 kV line, fully financed by the private sector under a 30-year concession with availability payments. Nigeria’s Electricity Act 2023 allows states to build and regulate their own grids. The World Bank and African Development Bank launched Mission 300 to connect 300 million people to electricity by 2030, and power pools are building regional markets under the Africa Single Electricity Market. Twelve West African Power Pool countries have permanently synchronised their grids. These measures are steering capital toward bankable transmission assets, structurally expanding Africa’s power transmission infrastructure investment gap market through 2032.
Key Market Challenges: Africa Power Transmission Infrastructure Investment Gap Market
Weak Utility Finances, High Sovereign Risk and Limited Public Budgets Constraining Transmission Funding
The market continues to face challenges around who pays for the grid. Many African utilities sell power below cost, collect only part of what they bill and carry large debts, which limits their ability to fund transmission or guarantee payments to private investors. Sovereign credit ratings in several countries are below investment grade, raising the cost of capital and requiring guarantees from development banks or export credit agencies. Public budgets are stretched by debt service, and transmission often loses out to generation or distribution in capital allocation because its benefits are spread across many users. Currency depreciation raises the local cost of dollar-priced equipment. Until utility finances improve and risk-sharing tools scale up, funding shortfalls will remain the main barrier to closing the gap across Africa’s power transmission infrastructure investment gap market.
Slow Land Acquisition, Right-of-Way Approvals and Environmental Permitting Delaying Line Construction
The market faces structural complexity from land and permits. A single 400 kV line can cross hundreds of land parcels, communal lands, farms, forests and protected areas, and each needs compensation, consent and environmental approval. Right-of-way disputes and resettlement claims can stall construction for years, and court challenges add further delay. Weak land registries and overlapping traditional and statutory tenure make it hard to confirm ownership. Environmental and social impact assessments required by development lenders add time but are essential for financing. In many countries, transmission lines take five years or more from planning to energisation, far longer than the two years needed to build a solar plant. Land and permitting therefore remain a near-term constraint on project schedules across Africa’s power transmission infrastructure investment gap market.
Long Equipment Lead Times, Import Dependence and Vandalism Raising Project Costs and Delivery Risk
The market faces practical constraints from supply chains and security. Large power transformers, high-voltage circuit breakers, HVDC converter equipment and specialised conductors are mostly imported from Europe, China and India, and lead times stretched to well over a year during 2024 and 2025 as global grid demand surged. Shipping, port congestion and import duties add further cost. Theft and vandalism of tower steel, conductors and substation equipment cause outages and costly repairs in South Africa, Nigeria and other markets. Skilled line crews, protection engineers and project managers are in short supply outside a few countries. Local manufacturing of towers, conductors and cables by firms such as Elsewedy Electric and regional fabricators is growing, but full localisation of high-voltage equipment will take several years across Africa’s power transmission infrastructure investment gap market.
Key Market Trends: Africa Power Transmission Infrastructure Investment Gap Market
Rise of Independent Transmission Projects and Availability-Payment PPP Concessions
The market is undergoing a clear shift in how transmission is financed. Independent transmission projects and PPP concessions are expected to account for 21.8% of financing model value by 2032, up from 6.4% in 2025. Under these models, private consortia design, finance, build and operate lines and substations, and the utility pays a fixed availability charge as long as the asset is available, which removes demand and tariff risk from investors. Kenya’s Lessos-Loosuk and Kibos-Kakamega-Musaga lines are the first full private transmission PPP in East Africa, and South Africa’s Independent Transmission Projects programme is expected to tender its first lines to private bidders. Power Grid Corporation of India, Africa50 and international infrastructure funds are building African transmission platforms. Public utility capex still leads at 46.1% of 2025 financing value, but its share is falling. This financing transition is reinforcing the market forecast 2032 across both national and regional projects.
Growth of HVDC Links and Cross-Border Interconnectors Under Regional Power Pools
A clear shift toward long-distance and cross-border transmission is reshaping the market. The 500 kV Ethiopia-Kenya HVDC line, which runs about 1,045 km and can carry 2,000 MW, now links the Eastern Africa Power Pool’s largest hydro producer with Kenya. The Egypt-Saudi Arabia HVDC link, with about 1,000 km of line and 3,000 MW of planned capacity, began commissioning its first 1,500 MW pole in late 2025, with Hitachi Energy supplying the converter stations. In West Africa, twelve power pool members have synchronised their grids, and new interconnectors are linking Côte d’Ivoire, Ghana, Nigeria, Senegal and the Sahel. HVDC links and converter stations account for 9.4% of market value in 2025 and are expected to grow at 18.6% annually through 2032, while cross-border interconnectors make up 11.2%. Developers are also studying export links from North Africa to Europe. This shift is lifting demand for HVDC equipment, long-span lines and regional control centres across the market.
Digital Substations, Grid Control Systems and Local Manufacturing of Towers, Conductors and Cables
A wave of technology and industrial investment is reshaping the market supply base. Utilities are moving from conventional air-insulated substations toward compact gas-insulated and digital substations with fibre-based protection, remote monitoring and automated switching, which cut land needs and improve reliability. SCADA, energy management systems and wide-area monitoring are being installed at national and power pool control centres to manage variable renewable output and cross-border flows. Grid control and protection systems accounted for 8.3% of market value in 2025. Hitachi Energy, Siemens Energy, GE Vernova, ABB and Schneider Electric are supplying digital substation and control platforms, while Elsewedy Electric, KEC International, Kalpataru Projects International and regional fabricators are expanding local production of towers, conductors and cables. Combined with private financing and power pool programs, these developments are reinforcing the market forecast 2032 across the entire value chain.
Segmental Insights: Africa Power Transmission Infrastructure Investment Gap Market
By Asset Owner: National Transmission Utilities Dominate Africa’s Power Transmission Infrastructure Investment Gap Market
The national transmission utilities segment dominates the market, accounting for 71.2% of market value in 2025, driven by grid programs at Eskom, TCN, KETRACO, the Egyptian Electricity Transmission Company, Ethiopian Electric Power, TANESCO and ONEE in Morocco. These utilities plan national networks, own most high-voltage assets and act as off-takers for private projects. Regional power pools and their member-owned interconnector companies contribute 11.4% of spending, supported by cross-border lines and shared control centres. Independent transmission companies account for 9.6% and are the fastest growing owner group, led by private consortia under PPP and independent transmission frameworks. Industrial and mining off-takers make up the remaining 7.8%, building dedicated lines and substations for mines and industrial parks in Zambia, the Democratic Republic of Congo, Guinea and South Africa. In 2025 and 2026, new private concessions and utility tenders reinforced segment growth across the market.
By Infrastructure Type: Overhead Transmission Lines Lead While HVDC Links Grow Fastest
Overhead transmission lines lead the market infrastructure mix, accounting for 34.8% of total value, driven by long high-voltage corridors linking renewable zones, hydro plants and mines to load centres. Substations and transformers contribute another 27.6%, followed by cross-border interconnectors at 11.2% and HVDC links and converter stations at 9.4%. Grid control and protection systems account for 8.3% of value, while underground and submarine cables, reactive power compensation and other items together form 8.7%. HVDC links are the fastest growing infrastructure category, expanding at a CAGR of 18.6% through 2032 as long-distance and cross-border projects move forward. By voltage, 400 kV lines hold the largest share at 31.5% of 2025 value. By purpose, renewable integration leads at 29.3%, ahead of grid reinforcement at 26.7%. Leading suppliers including Hitachi Energy, Siemens Energy, Larsen & Toubro and KEC International have aligned portfolios to this mix, driving higher value per kilometre across the market.
Regional Insights: Africa Power Transmission Infrastructure Investment Gap Market
Regional analysis of the market shows that Southern Africa leads with 31.4% of market value in 2025, driven by Eskom’s Transmission Development Plan, the Independent Transmission Projects programme and mining-linked grid work in Zambia, Zimbabwe, Mozambique and Botswana under the Southern African Power Pool. North Africa follows with 28.7%, supported by Egypt’s HVDC link with Saudi Arabia, large solar and wind evacuation lines in Egypt and Morocco, and grid upgrades in Algeria and Tunisia. West Africa contributes 17.6%, led by Nigeria’s grid expansion and West African Power Pool interconnectors. East Africa accounts for 15.3% and is the fastest growing region at a CAGR of 14.9%, supported by Kenya’s transmission PPP, the Ethiopia-Kenya HVDC line and new lines in Tanzania and Uganda. Central Africa holds 7.0%, with large hydro and mining-linked projects in the Democratic Republic of Congo and Cameroon. In 2025 and 2026, new concessions, interconnectors and utility tenders reinforced regional activity across the market.
Recent Developments: Africa Power Transmission Infrastructure Investment Gap Market
- The market witnessed strong momentum in planning and financing during 2025 and 2026. Eskom confirmed a Transmission Development Plan needing 14,500 km of new lines to connect 56 GW of new generation by 2034, with R112 billion earmarked over five years and 5,043 km of lines targeted by the 2029 financial year. In January 2025, African leaders, the World Bank and the African Development Bank met in Dar es Salaam for the Mission 300 Africa Energy Summit.
- Private and cross-border projects advanced. In December 2025, KETRACO signed a USD 311 million PPP with Africa50 and Power Grid Corporation of India for the 400 kV Lessos-Loosuk and 220 kV Kibos-Kakamega-Musaga lines under a 30-year concession. In November 2025, commissioning began on the first 1,500 MW pole of the 3,000 MW Egypt-Saudi Arabia HVDC interconnection, with Hitachi Energy supplying converter stations, supporting the market forecast 2032.
- Policy momentum has gained strong traction in the market. South Africa advanced its Independent Transmission Projects programme to bring private capital into grid build-out, Nigerian states began setting up their own electricity regulators under the Electricity Act 2023, and twelve West African Power Pool members operate synchronised grids. Combined with development finance support and the Africa Single Electricity Market, this positions Africa as one of the most important growth regions for transmission investment globally, strengthening long-term competitiveness in the market forecast 2032.
Key Market Players: Africa Power Transmission Infrastructure Investment Gap Market
- Hitachi Energy Ltd.
- Siemens Energy AG
- GE Vernova Inc.
- Schneider Electric SE
- ABB Ltd.
- Larsen & Toubro Limited
- KEC International Limited
- Kalpataru Projects International Limited
- Power Grid Corporation of India Limited
- China Electric Power Equipment and Technology Co., Ltd.
- Elsewedy Electric
- Prysmian S.p.A.
- NKT A/S
| By Infrastructure | By Voltage | By Financing | By Purpose | By Asset Owner |
| Overhead Lines Substations HVDC Interconnectors Grid Control Others | 66-110 kV 132 kV 220-230 kV 330 kV 400 kV 500 kV 765 kV | Public Utility Development Finance ITP PPP Concessions Blended Finance | Renewable Integration Evacuation Reinforcement Cross-Border Mining Urban | National Utilities Independent Transmission Power Pools Industrial & Mining |
Report Scope
In this report, the Africa Power Transmission Infrastructure Investment Gap Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive environment, and growth opportunities across the forecast period:
- By Infrastructure Type
- Overhead Transmission Lines
- Substations & Transformers
- HVDC Links & Converter Stations
- Cross-Border Interconnectors
- Grid Control, SCADA & Protection Systems
- Others (Underground & Submarine Cables, Reactive Power Compensation)
- By Voltage Level
- 66 kV to 110 kV
- 132 kV
- 220 kV to 230 kV
- 330 kV
- 400 kV
- 500 kV (including HVDC)
- 765 kV
- By Financing Model
- Public Utility Capex
- Concessional & Development Finance
- Independent Transmission Projects
- PPP & Availability-Payment Concessions
- Blended Finance & Green Bonds
- By Project Purpose
- Renewable Energy Integration
- Generation Evacuation
- Grid Reinforcement & Reliability
- Cross-Border Power Trade
- Mining & Industrial Load Connection
- Urban Demand & Data Center Supply
- By Asset Owner
- National Transmission Utilities
- Independent Transmission Companies
- Regional Power Pools
- Industrial & Mining Off-Takers
- By Geography
- Southern Africa
- North Africa
- West Africa
- East Africa
- Central Africa
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in Africa’s Power Transmission Infrastructure Investment Gap Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including independent transmission developers, infrastructure funds, regional EPC contractors, tower and conductor manufacturers, or grid software providers.
For a free sample of the Africa Power Transmission Infrastructure Investment Gap Market report, customised insights or delivery timelines, submit your query here
Africa Power Transmission Infrastructure Investment Gap Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Infrastructure Type
- By Voltage Level
- By Financing Model
- By Project Purpose
- By Asset Owner
- By Region
- Analyst Recommendations
- Geopolitical Impact on Power Transmission Investment in Africa
- Power Transmission Infrastructure Investment Gap Insights: Africa
- Market Dynamics
- Growth Drivers
- Large renewable and gas generation pipelines waiting for grid capacity driving transmission build-out.
- Weak, outage-prone national grids and rising urban, industrial and mining demand requiring grid reinforcement.
- Private transmission financing models, development finance and power pool programs unlocking investment.
- Restraints
- Weak utility finances, high sovereign risk and limited public budgets constraining transmission funding.
- Slow land acquisition, right-of-way approvals and environmental permitting delaying line construction.
- Long equipment lead times, import dependence and vandalism raising project costs and delivery risk.
- Opportunities
- Independent transmission project tenders and PPP concessions opening the grid to private investors.
- HVDC corridors and cross-border interconnectors expanding regional power trade.
- Renewable export links from North Africa to Europe and the Middle East.
- Challenges
- Currency depreciation raising the local cost of imported high-voltage equipment.
- Shortage of skilled line crews, protection engineers and project managers.
- Coordination gaps between national regulators, utilities and regional power pools.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Materials & Components (steel, aluminium, copper, insulators, transformer oil, power electronics)
- High-Voltage Equipment Manufacturers (Hitachi Energy, Siemens Energy, GE Vernova, ABB, Schneider Electric)
- Tower, Conductor & Cable Makers (Elsewedy Electric, Prysmian, NKT, regional fabricators)
- EPC Contractors (Larsen & Toubro, KEC International, Kalpataru Projects International, Chinese EPC firms)
- Project Developers & Independent Transmission Companies (Africa50, Power Grid Corporation of India, infrastructure funds)
- Financiers (World Bank, African Development Bank, export credit agencies, commercial banks, green bond investors)
- Regulators & Planning Bodies (national energy regulators, ministries, NERSA, NERC Nigeria, EPRA Kenya)
- National Transmission Utilities (Eskom, TCN, KETRACO, EETC, Ethiopian Electric Power, ONEE)
- Regional Power Pools (SAPP, WAPP, EAPP, COMELEC, CAPP)
- End-Users (distribution companies, mines, industrial parks, data centers, households and businesses)
- Africa Power Transmission Infrastructure Investment Gap Market: Regulatory Framework
- Africa Power Transmission Infrastructure Investment Gap Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Length (Circuit Kilometres)
- Market Share & Forecast
- By Infrastructure Type
- Overhead Transmission Lines
- Substations & Transformers
- HVDC Links & Converter Stations
- Cross-Border Interconnectors
- Grid Control, SCADA & Protection Systems
- Others (Underground & Submarine Cables, Reactive Power Compensation)
- By Voltage Level
- 66 kV to 110 kV
- 132 kV
- 220 kV to 230 kV
- 330 kV
- 400 kV
- 500 kV (including HVDC)
- 765 kV
- By Financing Model
- Public Utility Capex
- Concessional & Development Finance
- Independent Transmission Projects
- PPP & Availability-Payment Concessions
- Blended Finance & Green Bonds
- By Project Purpose
- Renewable Energy Integration
- Generation Evacuation
- Grid Reinforcement & Reliability
- Cross-Border Power Trade
- Mining & Industrial Load Connection
- Urban Demand & Data Center Supply
- By Asset Owner
- National Transmission Utilities
- Independent Transmission Companies
- Regional Power Pools
- Industrial & Mining Off-Takers
- By Geography
- Southern Africa
- North Africa
- West Africa
- East Africa
- Central Africa
- Competitive Landscape
- Company Market Share Analysis: Africa Power Transmission Infrastructure, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Hitachi Energy Ltd.
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Siemens Energy AG
- GE Vernova Inc.
- Schneider Electric SE
- ABB Ltd.
- Larsen & Toubro Limited
- KEC International Limited
- Kalpataru Projects International Limited
- Power Grid Corporation of India Limited
- China Electric Power Equipment and Technology Co., Ltd.
- Elsewedy Electric
- Prysmian S.p.A.
- NKT A/S
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the Africa power transmission infrastructure investment gap market and what is its growth forecast?
Ans: The market is valued at USD 9,420 million in 2025 and is projected to reach USD 20,056 million by 2032, growing at a CAGR of 11.4%, supported by renewable integration needs and private transmission finance.
2. Which segments are driving demand in Africa's power transmission infrastructure investment gap market?
Ans: Overhead transmission lines lead with a 34.8% value share in 2025, while independent transmission projects and PPP concessions are the fastest growing financing route at a 27.4% CAGR through 2032.
3. What are the key drivers of growth in the Africa power transmission infrastructure investment gap market?
Ans: Key drivers include large renewable and gas pipelines waiting for grid capacity, weak outage-prone national grids, rising urban and mining demand, and private financing models backed by development banks and power pools.
4. Which regions are driving growth in the Africa power transmission infrastructure investment gap market?
Ans: Southern Africa leads with a 31.4% share, driven by Eskom's grid plan. East Africa is the fastest growing region at a 14.9% CAGR, supported by Kenya's PPP and the Ethiopia-Kenya HVDC line.
5. What are the latest trends in the Africa power transmission infrastructure investment gap market?
Ans: The latest trends include independent transmission projects and availability-payment PPPs, HVDC links and cross-border interconnectors under power pools, and digital substations with growing local manufacturing of towers and conductors across the continent.