

India Solar Inverter Market, 2032
- Energy, Power & Storage, Renewables & Clean Fuels
- Nov 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s solar inverter market is witnessing strong structural growth, driven by record utility-scale solar additions, fast rooftop adoption under PM Surya Ghar, PM-KUSUM solar pump programmes, rising battery storage integration, green energy open access for industry, the national goal of 500 GW of non-fossil capacity by 2030, and rising investment by global and domestic brands in local inverter manufacturing, testing, and service networks.
| Study Duration | 2021-2032 |
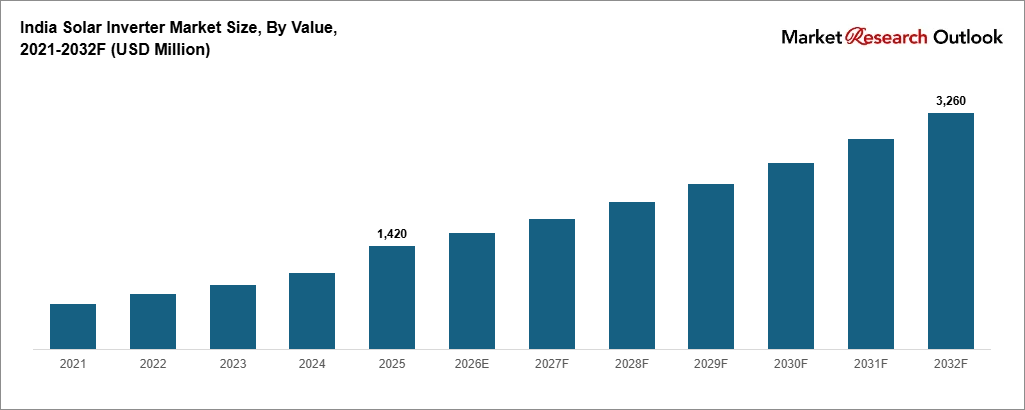
| Market Size (2025) | USD 1,420 Million |
| CAGR (2026-2032) | 12.6% |
| Leading Segment | String Inverters (Rooftop & C&I) |
| Fastest Growing Segment | Hybrid Inverters |
| Market Size (2032) | USD 3,260 Million |
Market Overview: India Solar Inverter Market
The India solar inverter market size is witnessing rapid expansion, driven by record solar capacity additions, fast rooftop growth, rising battery storage integration, state and central solar schemes, and the expansion of local manufacturing by leading inverter brands. Valued at USD 1,420 million in 2025 and projected to reach USD 3,260 million by 2032, growing at a CAGR of 12.6%, market growth is being fuelled by 37.9 GW of solar capacity added in 2025, more than 50 lakh rooftop installations under PM Surya Ghar, and rising use of open access solar by factories and commercial buildings. String inverters lead with a 41% value share, while hybrid inverters are the fastest growing product category. Lower module prices, higher efficiency targets, and grid code requirements for reactive power and fault ride-through are lifting the value of each inverter. As Sungrow India, Sineng Electric, TBEA Energy India, and FIMER India serve large utility parks, and SMA, Delta Electronics, Fronius, Growatt, GoodWe, Waaree, Polycab, and Luminous widen their rooftop and hybrid ranges, the India solar inverter market is evolving into a technology-led, storage-ready, and digitally monitored segment with strong long-term growth potential.
Key Report Takeaways: India Solar Inverter Market
- The India solar inverter market size is projected to grow from USD 1,420 million in 2025 to USD 3,260 million by 2032, registering a strong CAGR of 12.6%, driven by record solar additions, rooftop growth under PM Surya Ghar, and the structural shift toward hybrid and storage-ready inverters across urban and rural India.
- String inverters lead the India solar inverter market with a 41% value share in 2025, driven by strong demand from rooftop, C&I, and smaller ground-mounted projects, the wide product ranges of TBEA, Sungrow, Sineng, Solis, SMA, and Growatt, and rising preference for multi-MPPT designs that suit bifacial modules.
- Hybrid inverters are the fastest growing product category, expected to expand at a CAGR of 21.4% as homes, shops, and factories add battery storage to cut evening grid purchases, manage power cuts, and use more of their own solar generation across metro and tier-2 cities.
- Record solar build-out is lifting demand, with 37.9 GW of solar added in 2025, including 28.6 GW of utility-scale, 7.9 GW of rooftop, and 1.35 GW of off-grid and distributed capacity, while total solar capacity reached 164.59 GW by 31 July 2026.
- Rising investment by global and domestic inverter makers in Indian manufacturing, service centres, and testing, together with the BIS quality control framework for inverters, is strengthening local supply and supporting the India solar inverter market forecast 2032.
Key Market Drivers: India Solar Inverter Market
Record Solar Capacity Additions and the 500 GW Non-Fossil Target Driving Inverter Demand Across India
Growth in inverter demand is being driven by the fastest solar build-out in India’s history. The country added a record 37.9 GW of solar capacity in calendar year 2025, about 54.7% more than in 2024, including 28.6 GW of utility-scale capacity, 7.9 GW of rooftop systems, and 1.35 GW of off-grid and distributed capacity. In FY2026, solar additions reached 44.6 GW, and total installed solar capacity rose to 150.26 GW by the end of March 2026 and to 164.59 GW by 31 July 2026. India’s non-fossil power capacity crossed 300 GW in July 2026, more than 60% of the 500 GW goal for 2030, which keeps a large pipeline of solar parks, hybrid projects, and firm power tenders moving through SECI, NTPC, NHPC, and state agencies. Every gigawatt of new solar needs a matching block of inverter capacity, while hybrid and storage-linked tenders call for more advanced power conversion. Inverter shipments to solar projects rose 40.8% in 2025, creating strong structural pull-through across the India solar inverter market.
PM Surya Ghar, PM-KUSUM, and Rooftop Solar Growth Fuelling Residential and Distributed Inverter Adoption
Distributed solar has become a major growth engine for inverters in India. Rooftop additions reached 7.9 GW in 2025, 72% higher than in 2024, led by the PM Surya Ghar Muft Bijli Yojana, which aims to equip 1 crore households with rooftop solar. By July 2026, the scheme had crossed 50.06 lakh household installations with cumulative rooftop capacity of 14.8 GW, and subsidies of INR 28,024 crore had been released through Direct Benefit Transfer. July 2026 alone recorded 5.06 lakh installations, the highest monthly figure so far, and the government aims to cover 75 lakh households by December 2026. Most of these homes use single-phase string inverters of 1 kW to 5 kW, which has made the up to 5 kW rating the largest by unit volume. Under PM-KUSUM, solar pumps and solarised agricultural feeders use pump controllers and grid-tied inverters in large numbers across Rajasthan, Maharashtra, Haryana, and Madhya Pradesh. Together, these schemes are widening the buyer base for rooftop, hybrid, and off-grid inverters and supporting steady growth of residential and agricultural demand.
Battery Storage Integration and C&I Open Access Demand Strengthening Hybrid and String Inverter Growth
Battery storage is becoming a major catalyst for inverter value growth in India, with hybrid inverters projected to grow at a CAGR of 21.4% through 2032. Utility tenders for solar-plus-storage and firm and dispatchable renewable power require inverters that can manage battery charging, grid support, and ramp control, while homes and shops in areas with frequent power cuts are adding batteries to rooftop systems. Commercial and industrial buyers are also adopting solar faster under green energy open access rules, which allow consumers with a contracted load of 100 kW and above to buy renewable power, and many factories are adding captive rooftop and ground-mounted plants to cut power costs and meet emission goals. These buyers prefer three-phase string inverters of 50 kW to 350 kW with advanced monitoring and high efficiency. C&I applications already account for an estimated 22% of market value in 2025, and storage-ready string and hybrid designs are lifting average selling prices per kilowatt across C&I and residential segments through 2032.
Key Market Challenges: India Solar Inverter Market
High Import Dependence on Inverters and Power Semiconductors Exposing Supply Chains to Cost and Policy Risks
The sector continues to rely heavily on imported inverters, sub-assemblies, and power semiconductors, with Chinese brands and supply chains holding a large share of shipments. In 2025, Sungrow held nearly one-third of shipments, Sineng over 19%, and TBEA about 18%, and even locally assembled units depend on imported IGBT and silicon carbide devices, capacitors, and control boards. This exposes buyers to currency movements, freight costs, trade measures, and possible security reviews of grid-connected equipment. Domestic content rules already apply to solar modules and cells, and any extension of similar rules to inverters could reshape sourcing quickly. Smaller Indian assemblers struggle to match the scale and pricing of large global suppliers, and the local base for power electronics design remains thin. Building deeper local supply of semiconductors and key parts remains a medium-term challenge for the India solar inverter market.
Grid Integration Limits, Transmission Constraints, and Curtailment Risks Across High-Solar States
Inverter demand is closely tied to how quickly new solar plants can connect to the grid and sell power. Rajasthan and Gujarat host a large share of India’s utility-scale solar capacity, but transmission lines and substations in these regions have not always kept pace with project commissioning, which has led to connection delays and curtailment at some sites. Developers rushed to commission projects ahead of the deadline for the inter-state transmission charge waiver, which lifted 2025 additions but may create uneven demand in later years. Grid codes are also becoming stricter, with requirements for reactive power support, low and high voltage ride-through, and power quality, which raise testing and compliance costs for inverter makers. At the distribution level, many DISCOMs face voltage rise issues on feeders with high rooftop penetration and have tightened approval norms. These grid factors can slow project timelines and shift order flows, creating a near-term constraint for inverter suppliers in India.
Price Pressure, Thin Margins, and Testing and Certification Bottlenecks Under BIS Quality Control Rules
Inverter suppliers in India face intense price competition, as large tenders are won on the lowest levelised cost and rooftop buyers compare prices closely across brands. Falling global inverter prices and aggressive pricing by Chinese suppliers have squeezed margins for both importers and local assemblers, while dealers and installers also operate on thin margins. Quality rules are adding cost and time. The Solar Systems, Devices and Components Goods Order, 2025 covers inverters under standards including IS 16221 (Part 2), IS 16169, and IS 17980, but a shortage of accredited test labs led the government to extend self-certification for inverters above 200 kW until 31 December 2026. Getting new models tested and approved can take months, which slows launches. Warranty claims, service visits to remote sites, and spare part logistics further raise costs. Price discipline and faster testing capacity are needed to protect margins across the India solar inverter market.
Key Market Trends: India Solar Inverter Market
Shift Toward 1,500 V High-Power String and Central Inverters for Utility-Scale and Hybrid Projects
Utility-scale solar in India is moving clearly toward 1,500 V DC systems and larger inverter blocks, which lower cable losses, reduce the number of combiner boxes, and cut balance of system costs. Central inverters made up about 51% of 2025 shipments by capacity, overtaking string inverters as large standardised projects in Gujarat and Rajasthan were commissioned, while string inverters held 49%. Medium voltage inverter skids that combine the inverter, transformer, and switchgear in one factory-built unit are becoming common at large parks, while high-power string inverters of 300 kW and above are gaining share in projects that want better fault isolation and higher energy yield. Multi-MPPT designs that suit bifacial modules and tracker systems are also spreading. Sungrow India, Sineng Electric, TBEA Energy India, FIMER India, and TMEIC lead central inverter supply, while TBEA, Sungrow, Sineng, Solis, and NingBo Deye lead string supply. This trend is lifting product value and reinforcing long-term growth across utility and hybrid categories.
Growth of Hybrid and Storage-Ready Inverters With Smart Monitoring and Grid Support Features in the India Solar Inverter Market
Digital features and storage readiness are reshaping how inverters are designed and sold in India. Most new rooftop and C&I inverters now include Wi-Fi, Ethernet, or 4G data loggers with cloud apps that show live generation, faults, and savings, while utility inverters connect to plant SCADA for remote control. Hybrid inverters with built-in battery ports allow homes and businesses to add storage now or later, and brands such as Luminous, Polycab, Growatt, GoodWe, Solis, and Delta have widened their hybrid ranges for single-phase and three-phase users. Grid support functions such as reactive power control, active power limits, and ride-through are now standard in larger models, and some suppliers are trialling grid-forming inverters for storage projects. For EPC firms and asset owners, monitoring data supports faster fault fixes and higher plant uptime. These digital layers are raising product value, improving after-sales service, and becoming a key point of competition among inverter brands in India.
Localisation of Inverter Manufacturing and Capacity Expansion by Global and Domestic Players
A wave of local manufacturing and service expansion is reshaping inverter supply in India. Global leaders including Sungrow, SMA, Delta Electronics, Fronius, and FIMER run manufacturing, assembly, or service operations in India, while domestic brands such as Waaree, Polycab, and Luminous have added solar inverters to their portfolios to serve rooftop and C&I buyers through existing dealer networks. Module makers are increasingly bundling inverters with panels for rooftop and PM Surya Ghar projects, which gives them a larger share of the system value. India’s solar module manufacturing capacity reached about 172 GW by the end of March 2026, and inverter makers are following this localisation trend to meet BIS rules, shorten lead times, and support future domestic content requirements. More service centres and spare part warehouses in tier-2 and tier-3 cities are also improving uptime for rural and agricultural users. Together, these moves are strengthening the entire inverter value chain in India.
Segmental Insights: India Solar Inverter Market
By Application: Utility-Scale Segment Leads the India Solar Inverter Market
The utility-scale segment leads the India solar inverter market, accounting for an estimated 46% of total value in 2025, driven by 28.6 GW of utility-scale solar added in 2025, large solar park tenders, and hybrid and firm power projects that need high-power central and string inverters. 1,500 V systems and medium voltage skids are the dominant formats within this segment. The residential segment contributes another 25% of value, driven by PM Surya Ghar, rising electricity tariffs, and fast adoption of single-phase string and hybrid inverters. Commercial and industrial users account for 22%, led by factories, warehouses, hospitals, and offices using rooftop and open access solar. Agricultural applications, including solar pumps and solarised feeders under PM-KUSUM, account for 7% of value. In 2025, Sungrow, Sineng, TBEA, and FIMER supplied most large utility projects, while SMA, Delta, Growatt, GoodWe, Waaree, and Polycab expanded rooftop and C&I ranges, reinforcing segment leadership.
By Product Type: String Inverters Lead While Hybrid Inverters Grow Fastest
String inverters lead the India solar inverter market with a 41% value share in 2025, driven by their use across homes, C&I rooftops, and an increasing number of ground-mounted projects, along with easier maintenance and higher energy yield on uneven sites. Central inverters contribute 34% of value, mainly from large utility parks in Rajasthan and Gujarat, where their lower cost per kilowatt suits blocks of several megawatts. Hybrid inverters account for 14% of value and are the fastest growing category at a CAGR of 21.4%, driven by battery storage adoption in homes, shops, and C&I sites. Off-grid inverters and solar PCUs hold 6% of value, serving rural homes, telecom towers, and solar pumps, while micro inverters account for 3% and power optimisers and others for 2%. Leading suppliers including Sungrow, Sineng, TBEA, SMA, Delta, and Waaree have aligned their portfolios to this mix, supporting higher-value product adoption across the market.
Regional Insights: India Solar Inverter Market
Regional analysis shows that North India and West India together account for an estimated 64% of market value in 2025, with North India at 33% and West India at 31%. North India is led by Rajasthan, the largest solar state, along with Uttar Pradesh, Punjab, Haryana, and Delhi, where large solar parks, PM-KUSUM pumps, and fast rooftop growth support demand. West India is led by Gujarat and Maharashtra, home to large utility parks, strong C&I demand from industrial clusters, and high rooftop adoption in cities such as Ahmedabad, Surat, Mumbai, and Pune. South India contributes 24% of value, led by Karnataka, Tamil Nadu, Andhra Pradesh, Telangana, and Kerala, where open access solar for industry and rooftop demand in Bengaluru, Chennai, and Hyderabad remain strong. Central and East India together account for 12% of value, supported by Madhya Pradesh, Chhattisgarh, Odisha, West Bengal, and Bihar, where state tenders and rooftop programmes are scaling. Distribution and service expansion by Sungrow, TBEA, Polycab, Luminous, and Waaree is supporting balanced growth across the country.
Recent Developments: India Solar Inverter Market
- Inverter demand in India recorded strong progress during 2025 and 2026. India added a record 37.9 GW of solar capacity in calendar year 2025, and inverter shipments to solar projects rose 40.8% over 2024, with central inverters taking about 51% of shipments and string inverters 49%. In FY2026, India added 44.6 GW of solar, taking total solar capacity to 150.26 GW by the end of March 2026, and to 164.59 GW by 31 July 2026. India’s non-fossil power capacity crossed 300 GW in July 2026.
- Distributed solar has gained strong momentum. The PM Surya Ghar Muft Bijli Yojana crossed 50.06 lakh household installations with 14.8 GW of rooftop capacity by July 2026, with a record 5.06 lakh installations in that month and subsidies of INR 28,024 crore released. The government aims to reach 75 lakh households by December 2026. These developments are lifting demand for single-phase string and hybrid inverters and supporting long-term rooftop growth through 2032.
- Quality and localisation measures have also advanced in the India solar inverter market. In July 2026, the government extended self-certification for inverters above 200 kW under the Solar Systems, Devices and Components Goods Order, 2025 until 31 December 2026, citing limited testing capacity. Global and domestic suppliers continued to add local assembly, testing, and service capacity, strengthening long-term competitive positioning in the India solar inverter market forecast 2032.
Key Market Players: India Solar Inverter Market
- Sungrow India Private Limited
- Sineng Electric Co., Ltd.
- TBEA Energy (India) Private Limited
- FIMER India Private Limited
- Ginlong (Solis) Technologies Co., Ltd.
- SMA Solar India Private Limited
- Delta Electronics India Private Limited
- Fronius India Private Limited
- Growatt New Energy Co., Ltd.
- GoodWe Technologies Co., Ltd.
- Waaree Energies Limited
- Polycab India Limited
- Luminous Power Technologies Private Limited
| By Product Type | By Power Rating | By System Voltage | By Sales Channel | By Application |
| Central Inverters String Inverters Hybrid Inverters Micro Inverters Off-Grid Inverters & Solar PCUs Power Optimisers & Others |
Up to 5 kW 5 kW to 10 kW 10 kW to 50 kW 50 kW to 100 kW 100 kW to 500 kW 500 kW to 1 MW Above 1 MW |
Single-Phase (230 V AC) Three-Phase (415 V AC) 1,100 V DC Systems 1,500 V DC Systems Medium Voltage Inverter Skids |
Direct Sales to EPC Contractors & IPPs Distributors & Dealers System Integrators & Installers Online Channels Government & DISCOM Tenders Module Bundled Supply |
Utility-Scale Commercial & Industrial (C&I) Residential Agricultural (Solar Pumps & PM-KUSUM) |
Report Scope
In this report, the India Solar Inverter Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Product Type
- Central Inverters
- String Inverters
- Hybrid Inverters
- Micro Inverters
- Off-Grid Inverters & Solar PCUs
- Power Optimisers & Others
- By Power Rating
- Up to 5 kW
- 5 kW to 10 kW
- 10 kW to 50 kW
- 50 kW to 100 kW
- 100 kW to 500 kW
- 500 kW to 1 MW
- Above 1 MW
- By System Voltage
- Single-Phase (230 V AC)
- Three-Phase (415 V AC)
- 1,100 V DC Systems
- 1,500 V DC Systems
- Medium Voltage Inverter Skids
- By Sales Channel
- Direct Sales to EPC Contractors & IPPs
- Distributors & Dealers
- System Integrators & Installers
- Online Channels
- Government & DISCOM Tenders
- Module Bundled Supply
- By Application
- Utility-Scale
- Commercial & Industrial (C&I)
- Residential
- Agricultural (Solar Pumps & PM-KUSUM)
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Solar Inverter Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging domestic inverter brands, specialty hybrid and micro inverter producers, regional assemblers, or niche solar pump controller makers.
For a free sample of the India Solar Inverter Market report, customised insights or delivery timelines, submit your query here
India Solar Inverter Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Product Type
- By Power Rating
- By System Voltage
- By Sales Channel
- By Application
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Solar Inverter Market
- India Solar Inverter Market Insights
- Market Dynamics
- Growth Drivers
- Record solar capacity additions and the 500 GW non-fossil target driving inverter demand across India.
- PM Surya Ghar, PM-KUSUM, and rooftop solar growth fuelling residential and distributed inverter adoption.
- Battery storage integration and C&I open access demand strengthening hybrid and string inverter growth.
- Restraints
- High import dependence on inverters and power semiconductors exposing supply chains to cost and policy risks.
- Grid integration limits, transmission constraints, and curtailment risks across high-solar states.
- Price pressure, thin margins, and testing and certification bottlenecks under BIS quality control rules.
- Opportunities
- Solar-plus-storage and battery energy storage projects opening demand for hybrid and storage-ready inverters.
- PM-KUSUM solar pumps and agrivoltaics creating demand for pump controllers and off-grid inverters in rural India.
- Repowering and replacement of ageing inverters across early utility-scale and rooftop solar plants.
- Challenges
- Intense price competition from low-cost imported inverters and unorganised local assemblers.
- Limited accredited testing laboratories delaying BIS certification and new product launches.
- Ensuring after-sales service, uptime, and warranty support across remote and rural solar sites.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Components (IGBT and SiC power semiconductors, capacitors, magnetics, PCBs, enclosures, cooling systems)
- Inverter Manufacturers (Sungrow, Sineng, TBEA, FIMER, SMA, Delta, Waaree, Polycab)
- Firmware, Monitoring & Software Providers (SCADA, IoT data loggers, cloud monitoring, grid control functions)
- Battery & Energy Storage Partners (lithium-ion packs, battery management systems, storage integrators)
- Testing, Certification & Standards Bodies (BIS, MNRE, CEA, NABL-accredited test laboratories)
- Distributors, Dealers & Online Channels (B2B and B2C distribution networks)
- EPC Contractors & System Integrators (utility-scale, C&I, and rooftop project developers)
- Independent Power Producers & Developers (utility-scale and hybrid solar park owners)
- DISCOMs & Government Agencies (PM Surya Ghar, PM-KUSUM, SECI and state tenders)
- End-Users (utilities, factories, commercial buildings, households, farmers)
- India Solar Inverter Market: Regulatory Framework
- India Solar Inverter Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (GW)
- Market Share & Forecast
- By Product Type
- Central Inverters
- String Inverters
- Hybrid Inverters
- Micro Inverters
- Off-Grid Inverters & Solar PCUs
- Power Optimisers & Others
- By Power Rating
- Up to 5 kW
- 5 kW to 10 kW
- 10 kW to 50 kW
- 50 kW to 100 kW
- 100 kW to 500 kW
- 500 kW to 1 MW
- Above 1 MW
- By System Voltage
- Single-Phase (230 V AC)
- Three-Phase (415 V AC)
- 1,100 V DC Systems
- 1,500 V DC Systems
- Medium Voltage Inverter Skids
- By Sales Channel
- Direct Sales to EPC Contractors & IPPs
- Distributors & Dealers
- System Integrators & Installers
- Online Channels
- Government & DISCOM Tenders
- Module Bundled Supply
- By Application
- Utility-Scale
- Commercial & Industrial (C&I)
- Residential
- Agricultural (Solar Pumps & PM-KUSUM)
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Solar Inverter Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Sungrow India Private Limited
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Sineng Electric Co., Ltd.
- TBEA Energy (India) Private Limited
- FIMER India Private Limited
- Ginlong (Solis) Technologies Co., Ltd.
- SMA Solar India Private Limited
- Delta Electronics India Private Limited
- Fronius India Private Limited
- Growatt New Energy Co., Ltd.
- GoodWe Technologies Co., Ltd.
- Waaree Energies Limited
- Polycab India Limited
- Luminous Power Technologies Private Limited
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India solar inverter market and what is its growth forecast?
Ans: The India solar inverter market is valued at USD 1,420 million in 2025 and is projected to reach USD 3,260 million by 2032, growing at a CAGR of 12.6%, supported by record solar additions and rooftop growth.
2. Which segments are driving demand in the India solar inverter market?
Ans: String inverters lead with a 41% value share, while hybrid inverters are the fastest growing category at a 21.4% CAGR, driven by battery storage adoption in homes, shops, and commercial and industrial sites.
3. What are the key drivers of growth in the India solar inverter market?
Ans: Key drivers include 37.9 GW of solar added in 2025, PM Surya Ghar rooftop installations, PM-KUSUM solar pumps, the 500 GW non-fossil target for 2030, and rising battery storage integration across segments.
4. Which regions are driving growth in the India solar inverter market?
Ans: North India and West India lead with a combined 64% value share, driven by Rajasthan, Gujarat, Maharashtra, and Uttar Pradesh. South India follows with 24%, led by Karnataka and Tamil Nadu.
5. What are the latest trends in the India solar inverter market?
Ans: Key trends include the shift to 1,500 V high-power inverters, growth of hybrid and storage-ready models, smart cloud monitoring, grid support features, and local manufacturing expansion by global and domestic brands.