

India BESS Manufacturing Market Size, Share & Forecast 2032
- Battery Storage & Materials, Energy, Power & Storage
- Oct 2026
- Pages 140
- Report Format: pdf
- Report Price: $2400 USD
India’s BESS manufacturing base is witnessing strong structural growth, driven by the 20% domestic content mandate attached to viability gap funding, the ACC PLI outlay of INR 18,100 crore, higher customs duty on imported cells, duty-free feedstock and capital goods, the Critical Minerals Mission, gigafactory commissioning by domestic manufacturers, and rising interest from global technology owners forming India-specific licensing, joint venture, and contract manufacturing partnerships.
| Study Duration | 2021-2032 |
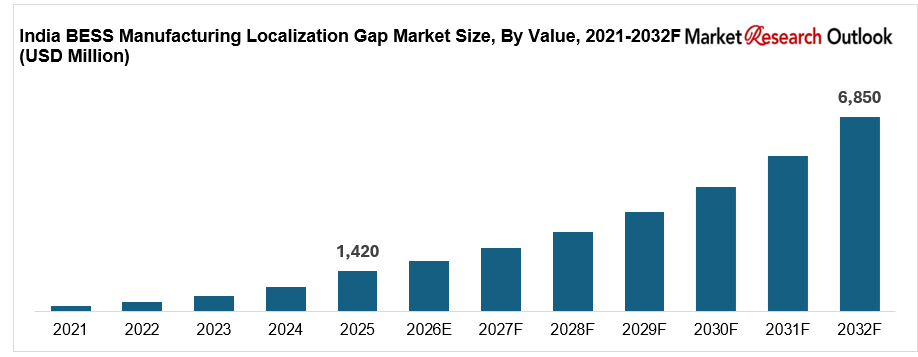
| Market Size (2025) | USD 1,420 Million |
| CAGR (2026-2032) | 25.2% |
| Leading Segment | Cells, Modules & Packs (Imported Cells, Local Assembly) |
| Fastest Growing Segment | Domestic Cell Manufacturing & Indigenous Software |
| Market Size (2032) | USD 6,850 Million |
India BESS Manufacturing Market Overview
The India BESS manufacturing localization gap market size is witnessing rapid expansion, driven by the 20% domestic content mandate, higher customs duty on imported cells, duty-free feedstock and capital goods, the ACC PLI outlay, and the first gigafactories reaching commercial output. Valued at USD 1,420 million in 2025 and projected to reach USD 6,850 million by 2032, growing at a CAGR of 25.2%, the India BESS manufacturing localization gap market growth is being fuelled by storage volumes contracted across Gujarat, Rajasthan, Andhra Pradesh, Tamil Nadu, Telangana and Uttar Pradesh. Cells, modules and packs lead the component mix, while domestic cell production and indigenous control software are the fastest growing localization stages. Around 82% of equipment value delivered in 2025 still originated outside India, and narrowing that share is the central commercial question. As Exide Energy Solutions, Amara Raja Energy & Mobility, Ola Electric, Reliance New Energy and Agratas scale capacity, and as integrators such as Waaree, Tata AutoComp and Larsen & Toubro deepen local content, the India storage manufacturing base is evolving into a policy-led, capital-intensive, and technology-driven industry with strong long-term growth potential.
Related research: India Battery Energy Storage System Market, India Grid-Scale Battery Storage Market and India Battery Materials Market.
Key Report Takeaways: India BESS Manufacturing Market
- The India BESS manufacturing localization gap market size is projected to grow from USD 1,420 million in 2025 to USD 6,850 million by 2032, registering a strong CAGR of 25.2%, driven by local content mandates, gigafactory commissioning, and the structural shift from imported systems toward domestically built storage equipment.
- Cells, modules and packs dominate the India BESS manufacturing localization gap market, accounting for 58% of equipment value in 2025, driven by their share of system cost, the concentration of cell supply outside India, and the pack assembly capacity of 60 GWh already installed across domestic plants.
- Domestic cell production and indigenous software are emerging as the fastest growing localization stages in the India BESS manufacturing localization gap market, expected to grow at 41.6% annually as gigafactories ramp and the mandated energy management system requirement takes effect across viability gap funding projects.
- The localization gap remains wide, with 82% of equipment value delivered into India in 2025 sourced from outside the country, a share projected to narrow to 39% by 2032, structurally expanding the India BESS manufacturing localization gap market across component, integration, and software categories.
- Rising investment by manufacturers such as Exide Energy Solutions, Amara Raja Energy & Mobility, Ola Electric, Reliance New Energy and Agratas in cell lines, pack assembly and materials capacity is strengthening local supply and supporting the India BESS manufacturing localization gap market forecast 2032.
Key Drivers of the India BESS Manufacturing Market
ACC PLI, Viability Gap Funding and the 20% Domestic Content Mandate Pulling BESS Manufacturing Onshore
Growth in the India BESS manufacturing localization gap market is being driven by a policy stack that now ties money to local content. The advanced chemistry cell production linked incentive scheme, notified in October 2021, carries an outlay of INR 18,100 crore against a 50 GWh target, with a minimum investment threshold of INR 225 crore per GWh and 40 GWh awarded across two rounds. The Ministry of Power directive of December 2025 requires every battery storage project supported under viability gap funding to meet a minimum 20% local content threshold, applied to NTPC and 15 beneficiary states, with indigenously developed energy management software mandated under the guidelines amendment of 4 August 2025. Requests from states for exemption under the public procurement rules were rejected outright. The second viability gap funding tranche of INR 5,400 crore for 30 GWh carries the same condition, making domestic value addition a disbursement test rather than a preference across the India BESS manufacturing market.
Rising Import Bill, Higher Customs Duty and Supply Concentration Risk Driving Localization Urgency
The India BESS manufacturing localization gap market is benefiting from the sheer cost of continued import dependence. Lithium-ion accumulator imports reached USD 4,934 million in the twelve months to April 2026, a rise of 57.14%, on volumes of 115,737 tonnes, with China supplying 93.79% of that value. The battery import bill has risen eightfold, from USD 384 million in FY2019 to more than USD 3 billion in FY2025. At a cell price near USD 85 per kWh, serving projected demand of 272 GWh by FY2030 without domestic cell output would carry an annual import bill above USD 23 billion. Policy has responded on both sides of the ledger: basic customs duty on imported cells and batteries has risen from 10% to 20%, while lithium carbonate, lithium hydroxide, cobalt powder and cell manufacturing capital goods now enter duty free. Concentration risk adds urgency, since roughly 80% of global lithium processing sits in a single country, sharpening the case for building BESS manufacturing capacity inside India.
Storage Demand Scale-Up and Gigafactory Commissioning Creating Bankable Volumes for Local Manufacturing
Demand visibility remains a major catalyst for the India BESS manufacturing localization gap market. Operational battery storage capacity reached 8.5 GWh by mid-2026 against 281 GWh tendered, of which 105 GWh sits under execution, giving manufacturers an order book rather than a forecast. Ola Electric operates 5 GWh of nickel manganese cobalt cell capacity at Krishnagiri in Tamil Nadu, targeting 100 GWh by 2030. Amara Raja Energy & Mobility is building a Giga Corridor at Divitipalle in Telangana at a cost of INR 9,500 crore, planned at 16 GWh of cell and 5 GWh of pack capacity, with a 1.5 GWh pack line already inaugurated. Reliance New Energy is commissioning cells at the Jamnagar green energy complex spread over 5,000 acres, and Agratas is building a 20 GWh plant in Gujarat. Outside the incentive scheme, a parallel base of 76 GWh in first-phase capacity and 112 GWh in announced additions is being led by Agratas, Amara Raja, Waaree and Adani, widening the supply pool across the India BESS manufacturing market.
India BESS Manufacturing Market Challenges
Absence of Domestic Cell and Refined Material Capacity Keeping the Localization Gap Wide
The India BESS manufacturing localization gap market continues to face a hard constraint at the two ends of the chain it does not yet control. More than 100 GWh of lithium-ion capacity has been announced, yet only 1.4 GWh of cell output was commissioned by the end of 2025, a delivery rate of 2.8% against the 50 GWh target set under the incentive scheme, and that output came from a single producer. Pack assembly tells a different story, with roughly 60 GWh of installed capacity, which is why the prevailing model remains imported cells finished into packs locally. Upstream, domestic lithium refining is effectively zero and cobalt refining stands at 2,060 tonnes per year, while India imported 18,200 tonnes of lithium compounds worth USD 1.2 billion during 2025, 68% from China and 24% from Chile. Until cell and refining capacity scale together, headline local content will keep outrunning genuine value addition across the India storage manufacturing base.
Slow Execution Against ACC PLI Targets, Equipment Delays and Technology Access Constraints
The India BESS manufacturing localization gap market faces structural complexity in converting awards into operating lines. Stringent domestic value addition conditions, a two-year installation timeline, and supply chain bottlenecks have all slowed commissioning under the incentive scheme, including visa delays affecting the overseas technical specialists many plants require for equipment installation. The first disbursement under the programme, of INR 73.7 crore to Ola Electric in March 2025, arrived more than three years after notification. Several experienced manufacturers chose to operate outside the scheme entirely, importing cells and assembling packs on commercially viable timelines without penalty clauses for missed milestones. Access to cell technology, electrode formulation and process know-how remains concentrated among a small group of licensors, and equipment export controls in supplier markets add further delay, holding back the pace of onshoring across the India BESS manufacturing market.
Cost Disadvantage Against Imported Cells and Thin Margins Limiting Domestic Scale-Up
The India BESS manufacturing localization gap market faces practical constraints around unit cost, scale and margin. Imported cells arrive from plants running at multiples of Indian volumes, with amortised equipment, established yields and integrated material supply, so early domestic output carries a structural cost penalty even after the duty step-up from 10% to 20%. Imported unit values fell 17.68% over the year to April 2026, compressing the headroom a new Indian line needs to recover capital. Storage developers bidding fixed capacity charges over 12-year and 15-year tenors have limited ability to absorb a premium for local sourcing beyond the mandated threshold. Scale, yield improvement, backward integration into cathode and anode materials, and recycling-led material recovery are the recognised routes out, but each takes several years, leaving cost the binding constraint on the India storage manufacturing base.
India BESS Manufacturing Market Trends
Imported Cells with Local Pack Assembly Emerging as India’s Default BESS Manufacturing Model
The India BESS manufacturing localization gap market is settling, for now, on a hybrid model in which cells are imported and everything around them is built locally. This stage accounts for 39% of equipment value in 2025, ahead of fully imported systems at 34%, and it is the route that lets developers satisfy the 20% local content floor without waiting for domestic cell output. Pack assembly capacity of 60 GWh already exists against cell capacity near 1 GWh, so the asymmetry is structural rather than temporary. Lithium iron phosphate chemistry carries 78% of stationary requirement, which simplifies module design and favours standardised local assembly. Amara Raja runs pack operations at Tirupati and Divitipalle with 2.5 GWh of combined verified capacity and has deployed more than 1 GWh of lithium storage across 50,000 telecom sites. This configuration is reinforcing the India BESS manufacturing localization gap market forecast 2032 across grid-scale, commercial and telecom applications.
Indigenous EMS Software and Power Electronics Emerging as the First Real Localization Wins
A visible shift toward software and power electronics is reshaping the India BESS manufacturing localization gap market. The viability gap funding guidelines amendment of 4 August 2025 made indigenously developed energy management system software compulsory for every supported project, and the December 2025 directive folded that software into the 20% local content calculation alongside hardware and labour. Power conversion systems account for 13% of equipment value and battery and energy management systems a further 9%, together representing the most accessible near-term substitution opportunity, since Indian firms already manufacture inverters, transformers, switchgear and control platforms at scale. Thermal management at 7% and enclosures at 8% follow the same logic. Larsen & Toubro, Bharat Heavy Electricals, Sterling and Wilson and Vision Mechatronics are building capability across these blocks, lifting measurable domestic content in BESS manufacturing well before cell supply arrives in volume.
Upstream Push into Cathode, Anode, Recycling and Critical Mineral Refining
A wave of upstream investment is reshaping supply depth across the India BESS manufacturing localization gap market. The Critical Minerals Mission, approved in January 2025, targets exploration, refining and stockpiling of the inputs cell plants depend on, while duty exemptions on lithium carbonate, lithium hydroxide, cobalt powder, battery scrap and a dozen other listed minerals cut the landed cost of feedstock. Epsilon Advanced Materials is building graphite anode and cathode capacity, and recyclers are scaling black mass recovery to return lithium, cobalt and nickel into domestic supply. Without this layer, local content claims rest on assembly labour rather than material value. Combined with the 20% mandate, 40 GWh of awarded incentive capacity, and a 105 GWh execution pipeline giving manufacturers visibility, these developments are reinforcing the India BESS manufacturing localization gap market forecast 2032 across the entire value chain.
India BESS Manufacturing Market Share by Segment
By End-Use Application: Grid-Scale & Utility Storage Dominates the India BESS Manufacturing Market
The grid-scale and utility storage application dominates the India BESS manufacturing localization gap market, accounting for an estimated 62% of equipment value, driven by viability gap funding volumes, state procurement programmes, and the 105 GWh execution pipeline feeding order books. Lithium iron phosphate packs in containerised blocks are the dominant configuration within this segment, with two-hour and four-hour systems taking most of the demand. Commercial and industrial storage contributes another 18% of value, concentrated in open access, captive solar and demand charge management installations. Telecom and data centre backup accounts for 14%, a segment where Indian pack assembly already holds high share, with more than 1 GWh deployed across 50,000 telecom sites. Residential and microgrid storage makes up 6%. In 2025, utility-led procurement by NTPC, GUVNL, APTRANSCO and UPPCL reinforced segment dominance in the India storage manufacturing base.
By Component: Cells, Modules & Packs Lead While Software and Power Electronics Localize Fastest
Cells, modules and packs lead the India BESS manufacturing localization gap market component mix, accounting for approximately 58% of equipment value, driven by their share of system cost and the concentration of cell supply outside the country. Power conversion systems contribute another 13%, enclosures, containers and structures 8%, battery and energy management systems 9%, thermal management 7%, and fire safety, electricals and other items the remaining 5%. Domestic cell production and indigenous software are the fastest growing localization stages within the India BESS manufacturing market, expanding at 41.6% annually, driven by gigafactory ramp-up and the mandated energy management system requirement. Leading manufacturers including Exide Energy Solutions, Amara Raja Energy & Mobility, Ola Electric, Reliance New Energy and Agratas have aligned capacity plans to this mix, lifting measurable domestic value addition across the India storage manufacturing base.
India BESS Manufacturing Market by Region
Regional analysis of the India BESS manufacturing localization gap market shows that South India and West India collectively account for approximately 66% of manufacturing value, driven by Tamil Nadu (the Ola Electric cell plant at Krishnagiri), Karnataka (the Exide Energy Solutions plant at Bengaluru), Telangana and Andhra Pradesh (the Amara Raja Giga Corridor and Tirupati pack lines), Gujarat (the Reliance complex at Jamnagar and the Agratas plant) and Maharashtra, supported by state incentives and established industrial clusters. North India contributes around 20% of value, led by Uttar Pradesh, Haryana and Rajasthan, where pack assembly, enclosure fabrication and power electronics capacity is expanding. East India accounts for 8%, supported by West Bengal and Odisha, while Central India accounts for 6%, led by Madhya Pradesh and Chhattisgarh. In 2025, capacity additions across Tamil Nadu, Telangana, Karnataka and Gujarat reinforced these production hubs across the India BESS manufacturing market.
Recent Developments in the India BESS Manufacturing Market
- The India BESS manufacturing localization gap market recorded strong momentum in policy and capacity during 2025 and 2026. The Ministry of Power issued a directive in December 2025 setting a minimum 20% local content threshold for every battery storage project supported under viability gap funding, addressed to NTPC and 15 beneficiary states, and rejected state requests for exemption under the public procurement rules. Indigenous energy management software had already been made compulsory through the guidelines amendment of 4 August 2025. Battery storage is not yet notified for exclusive procurement from Class-I local suppliers, so both Class-I and Class-II suppliers remain eligible provided the threshold is met.
- Production capacity moved from announcement to output. Ola Electric reached 5 GWh of cell capacity at Krishnagiri with a stated path to 100 GWh by 2030, and received the first incentive disbursement of INR 73.7 crore in March 2025. Amara Raja Energy & Mobility advanced its INR 9,500 crore Giga Corridor in Telangana toward 16 GWh of cell and 5 GWh of pack capacity. Exide Energy Solutions moved its Bengaluru cell plant into ramp-up, Reliance New Energy progressed cell commissioning at Jamnagar, and Agratas continued building its 20 GWh plant in Gujarat, together strengthening domestic supply across the India BESS manufacturing localization gap market.
- Trade and tax measures reshaped landed economics for the India BESS manufacturing localization gap market. Basic customs duty on imported cells and batteries moved from 10% to 20%, while lithium carbonate, lithium hydroxide, lithium oxide, cobalt powder, battery scrap and other listed minerals were exempted, down from 7.5% previously, alongside continued exemptions on cell manufacturing capital goods. Lithium-ion accumulator imports still reached USD 4,934 million in the year to April 2026 with China at 93.79%, underlining how far the substitution runway extends and strengthening long-term positioning in the India BESS manufacturing localization gap market forecast 2032.
Key Companies in the India BESS Manufacturing Market
- Exide Energy Solutions Limited
- Amara Raja Energy & Mobility Limited
- Ola Electric Mobility Limited (Ola Cell Technologies)
- Reliance New Energy Limited
- Agratas Energy Storage Solutions Private Limited (Tata Group)
- Adani New Industries Limited
- Waaree Energies Limited (Waaree ESS)
- Tata AutoComp Systems Limited
- Larsen & Toubro Limited
- Bharat Heavy Electricals Limited (BHEL)
- Sterling and Wilson Renewable Energy Limited
- GODI India Private Limited
- Vision Mechatronics Private Limited
| By Component | By Localization Stage | By Chemistry | By Supply Route | By Application |
| Cells & Packs PCS BMS & EMS Thermal Enclosures Fire Safety | Fully Imported Local Pack Assembly Local Modules Domestic Cells Power Electronics Software Others | LFP NMC Sodium-Ion Flow Advanced Lead-Acid | Direct Import Gigafactory Contract Manufacturing Joint Venture Integrator Aftermarket | Grid-Scale & Utility C&I Storage Telecom & Data Centre Residential & Microgrid |
Report Scope
In this report, the India BESS Manufacturing Localization Gap Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Component
- Cells, Modules & Packs
- Power Conversion Systems (PCS)
- Battery & Energy Management Systems
- Thermal Management & HVAC
- Enclosures, Containers & Structures
- Fire Safety, Electricals & Others
- By Localization Stage
- Fully Imported Systems
- Imported Cells with Local Pack Assembly
- Local Module & Pack Manufacturing
- Domestic Cell Manufacturing
- Local Power Electronics Manufacturing
- Indigenous Software & Controls
- Others
- By Battery Chemistry
- Lithium Iron Phosphate (LFP)
- Nickel Manganese Cobalt (NMC)
- Sodium-Ion
- Flow Batteries
- Advanced Lead-Acid & Others
- By Supply Route
- Direct Import (OEM to Developer)
- Domestic Gigafactory Supply
- Contract Manufacturing & Assembly
- Joint Venture & Technology Licensing
- System Integrator Supply
- Aftermarket & Replacement Supply
- By End-Use Application
- Grid-Scale & Utility Storage
- Commercial & Industrial Storage
- Telecom & Data Centre Backup
- Residential & Microgrid Storage
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India BESS Manufacturing Localization Gap Market, including business overview, capacity portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging cell and pack manufacturers, specialty power electronics suppliers, regional enclosure fabricators, or niche materials and recycling companies.
For a free sample of the India BESS Manufacturing Localization Gap Market report, customised insights or delivery timelines, submit your query here
India BESS Manufacturing Localization Gap Market, 2032
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Component
- By Localization Stage
- By Battery Chemistry
- By Supply Route
- By End-Use Application
- By Region
- Analyst Recommendations
- Geopolitical Impact on India BESS Manufacturing Localization Gap Market
- India BESS Manufacturing Localization Gap Market Insights
- Market Dynamics
- Growth Drivers
- ACC PLI, viability gap funding and the 20% domestic content mandate pulling BESS manufacturing onshore.
- Rising import bill, higher customs duty and supply concentration risk driving localization urgency in India.
- Storage demand scale-up and gigafactory commissioning creating bankable volumes for local BESS manufacturing.
- Restraints
- Absence of domestic cell and refined material capacity keeping the BESS manufacturing localization gap wide.
- Slow execution against ACC PLI targets, equipment delays and technology access constraints in India.
- Cost disadvantage against imported Chinese cells and thin margins limiting domestic manufacturing scale-up.
- Opportunities
- Indigenous EMS and BMS software, mandated under viability gap funding, opening a high-value entry point.
- Power conversion, thermal management and enclosure manufacturing offering near-term import substitution.
- Cathode, anode and recycling capacity building upstream depth in BESS manufacturing across India.
- Challenges
- Critical mineral refining capacity effectively absent, leaving BESS manufacturing localization exposed to imported inputs.
- Technology licensing, equipment imports and specialist visa delays slowing gigafactory commissioning.
- Measuring, auditing and enforcing domestic value addition claims across complex BESS supply chains.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Critical Mineral Mining & Refining (lithium, cobalt, nickel, graphite, manganese)
- Cathode, Anode & Electrolyte Material Producers (Epsilon Advanced Materials, Altmin)
- Cell Manufacturers & Gigafactories (Ola Cell Technologies, Exide Energy Solutions, Agratas)
- Module & Pack Assembly Lines (Amara Raja, Tata AutoComp, Waaree ESS, Vision Mechatronics)
- Power Conversion & Electrical Equipment Makers (inverters, transformers, switchgear)
- Battery & Energy Management System Developers (indigenous EMS and BMS software teams)
- Thermal, Enclosure & Fire Safety Suppliers (liquid cooling, containers, suppression systems)
- System Integrators & EPC Contractors (containerised block delivery, testing, commissioning)
- Project Developers, Utilities & Procurement Agencies (SECI, NTPC, NVVN, state discoms)
- Recycling, Second-Life & Material Recovery Operators (black mass, closed-loop supply)
- India BESS Manufacturing Localization Gap Market: Regulatory Framework
- India BESS Manufacturing Localization Gap Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (GWh)
- Market Share & Forecast
- By Component
- Cells, Modules & Packs
- Power Conversion Systems (PCS)
- Battery & Energy Management Systems
- Thermal Management & HVAC
- Enclosures, Containers & Structures
- Fire Safety, Electricals & Others
- By Localization Stage
- Fully Imported Systems
- Imported Cells with Local Pack Assembly
- Local Module & Pack Manufacturing
- Domestic Cell Manufacturing
- Local Power Electronics Manufacturing
- Indigenous Software & Controls
- Others
- By Battery Chemistry
- Lithium Iron Phosphate (LFP)
- Nickel Manganese Cobalt (NMC)
- Sodium-Ion
- Flow Batteries
- Advanced Lead-Acid & Others
- By Supply Route
- Direct Import (OEM to Developer)
- Domestic Gigafactory Supply
- Contract Manufacturing & Assembly
- Joint Venture & Technology Licensing
- System Integrator Supply
- Aftermarket & Replacement Supply
- By End-Use Application
- Grid-Scale & Utility Storage
- Commercial & Industrial Storage
- Telecom & Data Centre Backup
- Residential & Microgrid Storage
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India BESS Manufacturing Localization Gap Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Exide Energy Solutions Limited
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- Amara Raja Energy & Mobility Limited
- Ola Electric Mobility Limited (Ola Cell Technologies)
- Reliance New Energy Limited
- Agratas Energy Storage Solutions Private Limited (Tata Group)
- Adani New Industries Limited
- Waaree Energies Limited (Waaree ESS)
- Tata AutoComp Systems Limited
- Larsen & Toubro Limited
- Bharat Heavy Electricals Limited (BHEL)
- Sterling and Wilson Renewable Energy Limited
- GODI India Private Limited
- Vision Mechatronics Private Limited
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India BESS manufacturing localization gap market and what is its growth forecast?
Ans: The India BESS manufacturing localization gap market is valued at USD 1,420 million in 2025 and is projected to reach USD 6,850 million by 2032, growing at a CAGR of 25.2% on delivered equipment value.
2. Which segments are driving demand in the India BESS manufacturing localization gap market?
Ans: Cells, modules and packs lead with 58% of equipment value, while domestic cell production and indigenous control software are the fastest growing localization stages, supported by gigafactory ramp-up and mandated software rules.
3. What are the key drivers of growth in the India BESS manufacturing localization gap market?
Ans: Key drivers include the 20% local content mandate, the ACC PLI outlay of INR 18,100 crore, higher customs duty on imported cells, duty-free feedstock and capital goods, and rising contracted storage volumes across India.
4. Which regions are driving growth in the India BESS manufacturing localization gap market?
Ans: South India and West India lead with around 66% of manufacturing value, driven by Tamil Nadu, Karnataka, Telangana, Andhra Pradesh and Gujarat. North India follows at 20%, led by Uttar Pradesh and Haryana.
5. What are the latest trends in the India BESS manufacturing localization gap market?
Ans: Latest trends include imported cells paired with local pack assembly, mandated indigenous energy management software, faster localization of power electronics and enclosures, and upstream investment in cathode, anode and recycling capacity.