India Engineering Plastics Market: Automotive Lightweighting, Electronics Manufacturing and Domestic Capacity Additions Power Structural Growth, Forecasts 2032
- AI and Automation, Chemicals & Advanced Materials
- Sep 2026
- Pages 171
- Report Format: pdf
- Report Price: $1800 USD
Market research reports focusing on the India Engineering Plastics Market (2021–2032) highlight a detailed quantitative and qualitative breakdown of structural growth, industry drivers, and competitive benchmarking. This analysis delivers deep insights across key Product Types (ABS & SAN, Polyamides, Polycarbonate, PBT & PET Engineering Grades, POM, PMMA, High Performance Polymers, and Fluoropolymers) alongside distinct Material Grades (Unfilled, Glass Fibre Reinforced, Flame Retardant, Mineral Filled, Polymer Alloys & Blends, and Recycled). The study further segments processing mechanisms into Injection Moulding, Extrusion, and Blow Moulding, while analyzing supply chain routes across Distribution Channels including Direct Sales, Authorized Distributors & Dealers, Importers, B2B Digital Platforms, and Masterbatch Compounders. End-use adoption is evaluated across key economic pillars: Automotive & Transportation, Electrical & Electronics, Consumer Appliances, Industrial & Machinery, Medical & Healthcare, and Building & Construction.
Report Description
| Report Title: | India Engineering Plastics Market, By Product Type (ABS & SAN, Polyamides, Polycarbonate, PBT & PET Engineering Grades, POM, PMMA, High Performance Polymers, Fluoropolymers & Others); By Grade (Unfilled, Glass Fibre Reinforced, Flame Retardant, Mineral Filled, Alloys & Blends, Recycled); By Processing Technology (Injection Moulding, Extrusion, Blow Moulding & Others); By Distribution Channel (Direct Sales, Distributors & Dealers, Traders & Importers, Online B2B Platforms, Compounders); By End-User (Automotive & Transportation, Electrical & Electronics, Consumer Appliances, Industrial & Machinery, Medical & Healthcare, Building & Construction, Others); By Trend Analysis, Competitive Landscape & Forecast, 2021-2032 |
| Industry: | Chemicals & Materials / Polymers |
| No. of Pages: | 130-140 Pages |
| Summary: | India’s engineering plastics market is witnessing strong structural growth, driven by record passenger vehicle and electric vehicle production, expanding electronics, appliance, and electrical equipment manufacturing under PLI, accelerating metal-to-plastic substitution in industrial and medical applications, rising demand for flame retardant and glass fibre reinforced compounds, growing recycled content mandates, and rising interest from domestic and global polymer majors investing in India-specific ABS, polyamide, and fluoropolymer capacity, compounding lines, colour centres, and application development laboratories. |
| Study Duration | 2021-2032 |
| Market Size (2025) | USD 4,650 Million |
| CAGR (2026-2032) | 7.9% |
| Leading Segment | ABS & SAN (Automotive & Appliances) |
| Fastest Growing Segment | High Performance Polymers & Recycled Engineering Plastics |
| Market Size (2032) | USD 7,920 Million |
Market Overview: India Engineering Plastics Market
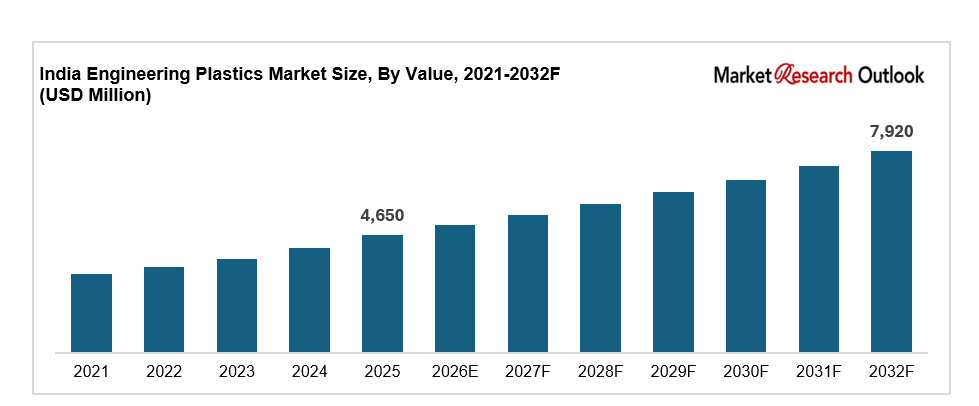
The India engineering plastics market size is witnessing rapid expansion, driven by record automotive and electric vehicle production, growing electronics and appliance assembly, rising electrical switchgear and solar equipment manufacturing, expanding industrial machinery and medical device output, increasing demand for lightweight and flame retardant materials, and major capacity additions by domestic and global polymer majors. Valued at USD 4,650 million in 2025 and projected to reach USD 7,920 million by 2032, growing at a CAGR of 7.9%, the India engineering plastics market growth is being fuelled by strong demand from automotive tier suppliers, electronics manufacturers, and appliance makers, alongside BIS quality control orders on polymers and the DGTR investigation into ABS imports that are shifting demand toward domestic supply. ABS and SAN lead consumption across automotive and appliance applications, while high performance polymers and recycled engineering plastics are emerging as the fastest growing categories. Shifting converter preferences toward halogen free flame retardant grades, growing electric vehicle lightweighting needs, and rising demand for circular materials are reshaping the supply landscape. As domestic producers including INEOS Styrolution India, Bhansali Engineering Polymers, Supreme Petrochem, Reliance Industries, and Gujarat Fluorochemicals expand resin capacity, and global players including SABIC, Covestro, BASF, DuPont, Celanese, Lanxess, and Kingfa scale compounding and technical service networks, the Indian engineering plastics sector is evolving into a specification-led, innovation-driven, and increasingly self-reliant industrial materials ecosystem with strong long-term growth potential.
Key Report Takeaways: India Engineering Plastics Market
- The India engineering plastics market size is projected to grow from USD 4,650 million in 2025 to USD 7,920 million by 2032, registering a strong CAGR of 7.9%, driven by accelerated automotive and electric vehicle production, rising electronics and appliance demand, and the structural shift toward domestically produced and compounded engineering plastics across industrial India.
- ABS and SAN dominate the Indian engineering polymer market, accounting for 31% of total value in 2025, driven by their balance of impact strength, surface finish, and cost across automotive interiors, appliance housings, and consumer electronics, the domestic manufacturing presence of INEOS Styrolution India, Bhansali Engineering Polymers, and Supreme Petrochem, and rising demand across two wheeler, passenger car, and appliance channels.
- High performance polymers and recycled engineering plastics are emerging as the fastest growing segments in the engineering plastics industry in India, expected to grow at 11.2% annually as electric vehicle makers, electronics assemblers, and appliance brands reshape sourcing strategies toward PPS, PEEK, LCP, and post-consumer recycled ABS and polycarbonate across Maharashtra, Tamil Nadu, and Gujarat clusters.
- Rapid scaling of end-use manufacturing, with passenger vehicle production crossing 5 million units, electric vehicle sales exceeding 2 million units, and mobile phone output reaching INR 5.25 lakh crore in FY25, is structurally expanding the Indian engineering plastics sector across automotive, electronics, and appliance categories.
- Rising investments by domestic and global majors such as INEOS Styrolution India, Bhansali Engineering Polymers, Supreme Petrochem, SABIC, BASF, Lanxess, and Kingfa in ABS and polyamide capacity, compounding lines, colour centres, and recycled and flame retardant grades, together with BIS quality control orders on polymers and trade remedy actions on ABS imports, are strengthening local supply and supporting the domestic engineering plastics industry forecast 2032.
Key Market Drivers: India Engineering Plastics Market
Rapid Growth in Automotive Production, Electric Vehicle Adoption, and Lightweighting Driving Engineering Plastics Consumption Across India
Growth in the India engineering plastics market is being driven by record automotive production, accelerating electric vehicle adoption, and rising lightweighting requirements across passenger cars, two wheelers, commercial vehicles, and electric mobility platforms. India’s passenger vehicle production crossed 5 million units in FY25, two wheeler production exceeded 23 million units, and electric vehicle sales surpassed 2 million units, with each passenger car consuming 55 to 75 kilograms of engineering plastics across bumpers, instrument panels, door trims, lighting, under-bonnet parts, and electrical connectors. Automotive and transportation absorbs 36% of engineering plastics consumption in India, led by component makers such as Motherson, Minda, Lumax, Varroc, and Uno Minda supplying Maruti Suzuki, Tata Motors, Mahindra, Hyundai, and Bajaj. Electric vehicles add battery housings, high voltage connectors, busbar insulation, and charging components that raise engineering plastics content by 8 to 12 kilograms per vehicle. Glass fibre reinforced polyamide 66 and PBT grades are priced between INR 280 and INR 420 per kilogram, while PPS and PEEK for high voltage and thermal management applications command INR 900 to INR 4,500 per kilogram. Per capita engineering plastics consumption in India remains below 1.1 kilograms per year compared with more than 9 kilograms in developed markets, indicating significant long-term headroom. Rising vehicle exports, premiumisation, and safety norms are creating strong structural pull-through demand across the domestic engineering plastics industry
Source: Market Research Outlook
Electronics, Appliance, and Electrical Equipment Manufacturing Expansion Under PLI Creating Structural Demand for Flame Retardant and High Performance Polymers
The India engineering plastics market is benefiting from sustained growth in electronics, appliance, and electrical equipment manufacturing, with electrical and electronics accounting for 24% of demand in 2025 and consumer appliances another 14%. Mobile phone production reached INR 5.25 lakh crore in FY25 under the electronics PLI scheme, refrigerator output crossed 20 million units, and air conditioner and washing machine production expanded under the white goods PLI scheme with an outlay of INR 6,238 crore, with each refrigerator consuming 6 to 9 kilograms and each air conditioner 4 to 6 kilograms of ABS, polystyrene, polycarbonate, and PBT. Halogen free flame retardant polycarbonate, PC and ABS alloys, and glass filled PBT are being qualified by Dixon, Samsung, LG, Voltas, Havells, Polycab, and Amber Enterprises for chargers, switchgear, connectors, and housings meeting UL 94 V-0 and BIS safety standards. Flame retardant compounds command realisations of INR 260 to INR 380 per kilogram, compared with INR 150 to INR 190 per kilogram for general purpose ABS, supporting mix improvement across the Indian engineering plastics sector. Solar module junction boxes, EV chargers, smart meters, and data centre equipment are adding further demand for PBT, polyamide, and polycarbonate alongside grid investment of INR 9.15 lakh crore planned through 2032.
Domestic Capacity Additions, Compounding Investments, and Trade Protection Strengthening Local Supply of Engineering Plastics
Domestic capacity additions, compounding investments, and trade protection are a major catalyst for the India engineering plastics market, with imports still supplying 100% of polycarbonate and POM and 58% of ABS consumed in India in 2024. INEOS Styrolution India operates ABS and SAN capacity at Nandesari, Dahej, and Moxi in Gujarat, Bhansali Engineering Polymers has expanded ABS capacity at Abu Road in Rajasthan to 137 thousand tonnes per annum with a further phase planned, and Supreme Petrochem commissioned a 140 thousand tonne ABS plant at Amdoshi in Maharashtra in 2024, its first entry into the product. Gujarat Fluorochemicals produces PTFE, PVDF, and fluoropolymers at Dahej, and Reliance Industries supplies PET engineering grades and styrenic intermediates. Compounders including Kingfa, APPL Industries, Lanxess, Celanese, SABIC, BASF, and DuPont operate glass filled, flame retardant, and alloy compounding lines in Gujarat, Maharashtra, Tamil Nadu, and Haryana that supplied 62% of specialty compounds in 2025. The Directorate General of Trade Remedies initiated an anti-dumping investigation into ABS imports from China, Korea, Taiwan, Malaysia, and Japan in 2024, and BIS quality control orders on polycarbonate, polyamide, and ABS are tightening import compliance. Production Linked Incentive schemes for electronics, automotive components, and white goods are structurally expanding engineering polymer demand in India growth across all major end-user categories through 2032.
Key Market Challenges: India Engineering Plastics Market
Dependence on Imported Polycarbonate, POM, PA66, and Specialty Polymers Exposing Converters to Price and Supply Volatility
The India engineering plastics market continues to face challenges around import dependence, with polycarbonate, POM, polyamide 66, PPS, and PMMA almost entirely sourced from China, Korea, Taiwan, Thailand, Japan, Saudi Arabia, and Europe. India imports its full polycarbonate requirement of 310 thousand tonnes and full POM requirement of 95 thousand tonnes, while polyamide 66 depends on imported adiponitrile and hexamethylene diamine because India has no domestic capacity for these intermediates. Polycarbonate prices moved between USD 1,700 and USD 2,900 per tonne during 2022 and 2025, ABS ranged between USD 1,350 and USD 2,300 per tonne, and polyamide 66 between USD 2,600 and USD 4,200 per tonne, compressing moulder margins by 300 to 600 basis points in weak quarters. Styrene, acrylonitrile, butadiene, and caprolactam feedstocks are also partly imported, and container freight disruptions in 2024 and 2025 stretched lead times to 8 to 12 weeks. Rupee depreciation and anti-dumping duties on intermediates add further cost uncertainty for downstream converters. India’s continued dependence on imported resins and intermediates limits pricing flexibility across the Indian engineering plastics sector.
Price Competition from Low Cost Imports and Thin Conversion Margins Limiting Profitability of Smaller Compounders and Moulders
The India engineering plastics market faces structural complexity from variations in import pricing, product quality, and channel margins across different regions. Chinese, Korean, and Taiwanese producers continue to offer prime ABS, polycarbonate, and polyamide at prices 8% to 15% below domestic realisations, and imported compounds and finished components from China and Southeast Asia enter through electronics and appliance supply chains at similar discounts. Average EBITDA margins for standalone Indian compounders range between 7% and 12%, and working capital cycles stretch to 75 to 110 days because automotive and appliance customers demand extended credit and annual price reductions. Differential availability of colour matching, testing, and application support across states creates operational complexity for players such as INEOS Styrolution India, Bhansali Engineering Polymers, Kingfa, APPL Industries, and Lanxess operating pan-India. While BIS quality control orders and the ABS anti-dumping investigation are improving pricing discipline, import competition remains a near-term challenge for the domestic engineering plastics industry.
Regulatory Scrutiny on Halogenated Flame Retardants, BPA, and Plastic Waste Restricting Conventional Engineering Plastic Formulations
The India engineering plastics market faces practical constraints around flame retardant regulation, bisphenol A scrutiny, plastic waste rules, and reformulation costs across the value chain. The European Union RoHS and REACH frameworks are restricting brominated flame retardants and specific phthalates, and Indian exporters of electronics, appliances, and automotive components must qualify halogen free polycarbonate, PBT, and polyamide grades that add 15% to 25% to compound cost. The European Union restricted bisphenol A in food contact materials from January 2025, affecting polycarbonate water bottles, appliance parts, and medical components, while the Plastic Waste Management Rules and extended producer responsibility obligations require brand owners to collect and recycle rigid plastic packaging and electronic waste. BIS quality control orders on polymers are tightening compliance for both importers and small compounders. Reformulating to halogen free, recycled, or bio-based grades adds 10% to 20% to raw material cost and requires requalification with OEMs. Smaller moulders face additional compliance complexity under E-Waste Management Rules and vehicle end-of-life norms. Recycled ABS and polycarbonate, bio-based polyamides, and phosphorus based flame retardant systems are emerging as solutions to differentiate, but higher pricing and limited qualification bandwidth remain barriers to widespread adoption across the domestic engineering plastics industry.
Key Market Trends: India Engineering Plastics Market
Rapid Adoption of Recycled, Bio-Based, and Halogen Free Engineering Plastics in India
The India engineering plastics market is undergoing a clear technology shift toward recycled, bio-based, and halogen free engineering plastics, with these advanced variants expected to capture 20% of new compound grades by 2028. Post-consumer recycled ABS and polycarbonate from appliance, automotive, and electronic waste deliver 30% to 50% recycled content at cost parity with prime resin, while bio-based polyamide 610 and 1010 from castor oil offer 60% to 100% renewable carbon, and India’s position as the largest castor oil producer offers a natural feedstock advantage. Halogen free flame retardant polycarbonate, PBT, and polyamide grades meeting UL 94 V-0 are replacing brominated systems in chargers, switchgear, and connectors. Leading domestic and global players including SABIC, Covestro, BASF, Lanxess, Kingfa, APPL Industries, and Bhansali Engineering Polymers have introduced recycled, bio-based, and halogen free ranges for the Indian market through 2024 and 2025. Chemical recycling of polyamide and polycarbonate into monomers is also gaining traction, particularly in Maharashtra and Gujarat where appliance and automotive brands are preparing for extended producer responsibility and end-of-life vehicle obligations. This product transition is reinforcing the Indian engineering polymer market forecast 2032 across both automotive and electronics categories.
Growth of Electric Vehicle, High Voltage, and Battery System Applications in the India Engineering Plastics Market
A clear shift toward electric vehicle, high voltage, and battery system applications is reshaping the India engineering plastics market, particularly in the automotive and transportation segment. India’s electric vehicle sales exceeded 2 million units in FY25 across two wheelers, three wheelers, passenger cars, and buses, and each electric passenger car consumes 8 to 12 kilograms more engineering plastics than a comparable internal combustion vehicle through battery module housings, cell holders, busbar insulation, high voltage connectors, charging inlets, and thermal management components. Orange coloured flame retardant polyamide 66, PBT, and PPS grades with comparative tracking index above 600 volts are being qualified by Tata Motors, Mahindra, Ola Electric, Ather, TVS, and Bajaj alongside tier suppliers such as Motherson, Uno Minda, and TE Connectivity India. Lanxess has invested in a specialty polyamide compounding unit targeting high voltage EV connectors in India, and battery cell and pack manufacturers including Exide Energy, Amara Raja, and Ola Cell Technologies are adding polycarbonate and polyamide demand for cell holders and module covers. Electric vehicle applications accounted for 6% of engineering plastics demand in 2025 and are expected to reach 14% by 2032, with EV makers increasingly preferring locally compounded grades to shorten qualification cycles.
Capacity Expansion, Compounding Localisation, and Trade Protection by Domestic and Global Polymer Majors
A wave of capacity expansion, compounding localisation, and trade protection is reshaping the India engineering plastics market supply landscape. Combined India-focused capital expenditure announcements in ABS, polyamide, fluoropolymer, and compounding capacity exceeded USD 900 million across 2023 to 2025. Supreme Petrochem commissioned its 140 thousand tonne ABS plant at Amdoshi, Bhansali Engineering Polymers expanded ABS capacity at Abu Road to 137 thousand tonnes with a further phase under implementation, INEOS Styrolution India is debottlenecking ABS and SAN lines in Gujarat, Gujarat Fluorochemicals is expanding PVDF and fluoropolymer capacity at Dahej for battery and solar applications, and SABIC, BASF, Lanxess, Celanese, DuPont, Kingfa, and APPL Industries have added compounding lines, colour centres, and application laboratories in Gujarat, Maharashtra, Tamil Nadu, and Haryana. The DGTR anti-dumping investigation into ABS imports, BIS quality control orders on polymers, and PLI allocations for electronics, automotive components, and white goods have structurally favoured organized domestic supply. Combined with electric vehicle and appliance capacity additions driving compound demand and export orders to the Middle East, Africa, and Southeast Asia, these developments are reinforcing the engineering plastics industry in India forecast 2032 across the entire value chain.
Segmental Insights: India Engineering Plastics Market
By End-User: Automotive & Transportation Segment Dominates the India Engineering Plastics Market
The automotive and transportation end-user segment dominates the India engineering plastics market, accounting for 36% of total value in 2025, driven by record vehicle production, accelerating electric vehicle adoption, and improving lightweighting economics. ABS, polypropylene alloys, polyamide, and polycarbonate for bumpers, instrument panels, lighting, and under-bonnet parts are the dominant products within this segment, with interior and exterior trim capturing 47% of automotive related engineering plastics purchases. The electrical and electronics segment contributes another 24% of demand, driven by mobile phones, chargers, switchgear, connectors, and solar equipment across Tamil Nadu, Uttar Pradesh, Karnataka, and Gujarat clusters. The consumer appliances segment accounts for 14%, led by refrigerators, air conditioners, washing machines, and kitchen appliances, while industrial and machinery contributes 10% through gears, bearings, pump components, and conveyor parts, and medical and healthcare adds 5% through syringes, diagnostic housings, and device components. In 2025, leading engineering plastics players including INEOS Styrolution India, Bhansali Engineering Polymers, SABIC, BASF, Lanxess, and Kingfa scaled up automotive and electric vehicle focused compound supply, reinforcing segment dominance in the Indian engineering plastics sector.
By Product Type: ABS & SAN Lead While High Performance Polymers and Recycled Grades Grow Fastest
ABS and SAN lead the India engineering plastics market product landscape, accounting for 31% of total value, driven by their balanced impact strength, surface gloss, paintability, and cost efficiency across automotive interiors, two wheeler panels, appliance housings, and consumer electronics. Polyamides contribute another 22%, primarily across under-bonnet automotive parts, electrical connectors, and industrial components, while polycarbonate accounts for 17% through lighting, chargers, appliance panels, and optical applications. High performance polymers and recycled engineering plastics are the fastest growing categories within the Indian engineering plastics sector, expanding at 11.2% annually, driven by PPS, PEEK, and LCP demand for electric vehicle high voltage systems and electronics, and post-consumer recycled ABS and polycarbonate mandated by appliance and electronics brands. PBT and PET engineering grades and POM together account for 12% of the market, PMMA contributes 7%, and fluoropolymers and other specialty polymers add 11%, with the medical, aerospace, and semiconductor grade segment expected to grow rapidly through 2032. Leading manufacturers including INEOS Styrolution India, Bhansali Engineering Polymers, Supreme Petrochem, SABIC, Covestro, BASF, DuPont, and Celanese have aligned product portfolios to this mix, driving specialty engineering plastics adoption across the Indian engineering plastics sector.
Regional Insights: India Engineering Plastics Market
Regional analysis of the India engineering plastics market shows that West India and South India collectively account for 62% of total engineering plastics value, driven by Gujarat (Nandesari, Dahej, and Moxi ABS plants, Dahej fluoropolymer complex, Sanand automotive and appliance cluster), Maharashtra (Amdoshi ABS plant, Pune and Chakan automotive belt, Mumbai compounding hubs), Tamil Nadu (Chennai automotive, electronics, and appliance cluster, Hosur electric vehicle manufacturing), Karnataka (Bengaluru aerospace, electronics, and medical devices), and Telangana, supported by resin plants, compounders, ports, and strong industrial consumption levels. North India contributes 25% of demand, led by Haryana, Delhi NCR, Uttar Pradesh, Rajasthan, and Punjab, supported by Maruti Suzuki, Hero, and Honda automotive clusters, mobile phone and appliance assembly in Noida and Greater Noida, and the Abu Road ABS plant in Rajasthan. Central and East India together account for 13% of demand, supported by Madhya Pradesh, West Bengal, Odisha, and Jharkhand, where two wheeler, appliance, and industrial machinery demand is accelerating. In 2025, capacity and distribution operations by INEOS Styrolution India and Gujarat Fluorochemicals across Gujarat, Supreme Petrochem and Kingfa across Maharashtra, Bhansali Engineering Polymers across Rajasthan, Lanxess and SABIC across Gujarat and Tamil Nadu, and APPL Industries across Haryana and Tamil Nadu reinforced regional supply hubs, supporting closer execution of automotive, electronics, and appliance projects across the domestic engineering plastics industry.
Recent Developments: India Engineering Plastics Market
- The India engineering plastics market witnessed strong momentum in trade policy and capacity progress during 2024 and 2025. The Directorate General of Trade Remedies initiated an anti-dumping investigation into ABS imports from China, Korea, Taiwan, Malaysia, and Japan in 2024 following an application by domestic producers, and BIS quality control orders on polycarbonate, polyamide, and ABS moved toward implementation. Domestic engineering plastics consumption is projected to reach 1,540 thousand tonnes in 2025 and 2,480 thousand tonnes by 2032, growing at 7.0% annually in volume terms, while electric vehicle sales exceeded 2 million units and passenger vehicle production crossed 5 million units in FY25.
- Domestic and global polymer majors have deepened India-focused capacity expansion. Supreme Petrochem commissioned a 140 thousand tonne ABS plant at Amdoshi, Maharashtra, in 2024, Bhansali Engineering Polymers expanded ABS capacity at Abu Road to 137 thousand tonnes per annum with a further phase under implementation, INEOS Styrolution India is debottlenecking ABS and SAN capacity in Gujarat, and Gujarat Fluorochemicals is expanding PVDF and fluoropolymer output at Dahej. Lanxess invested in a specialty polyamide compounding unit for high voltage EV connectors, and SABIC, BASF, Celanese, DuPont, Kingfa, and APPL Industries added compounding lines and colour centres across Gujarat, Maharashtra, Tamil Nadu, and Haryana. These developments are strengthening domestic supply and supporting the India engineering plastics market forecast 2032.
- Automotive, electronics, and appliance momentum has gained strong traction in the India engineering plastics market. In 2025, automotive OEMs including Maruti Suzuki, Tata Motors, Mahindra, Hyundai, Ola Electric, and TVS qualified flame retardant and glass reinforced compounds for new electric and premium models, electronics assemblers including Dixon, Samsung, Foxconn, and Tata Electronics scaled halogen free polycarbonate and PC and ABS alloy usage under PLI, and appliance makers including Voltas, LG, Haier, and Amber Enterprises expanded refrigerator and air conditioner production under the white goods PLI scheme. Strategic partnerships between resin producers, compounders, OEMs, and recyclers are positioning India as one of the most actively scaling engineering plastics markets globally, strengthening long-term competitive positioning in the engineering polymer demand in India forecast 2032.
Key Market Players: India Engineering Plastics Market
- Reliance Industries Ltd.
- INEOS Styrolution India Ltd.
- Bhansali Engineering Polymers Ltd.
- Supreme Petrochem Ltd.
- SABIC India Pvt. Ltd.
- Covestro (India) Pvt. Ltd.
- BASF India Ltd.
- DuPont India Pvt. Ltd.
- Celanese India Pvt. Ltd.
- Lanxess India Pvt. Ltd.
- Gujarat Fluorochemicals Ltd.
- APPL Industries Ltd.
- Kingfa Science & Technology (India) Ltd.
| By Product Type | By Grade | By Processing | By Distribution | By End-User |
| ABS & SAN Polyamides Polycarbonate PBT & PET POM PMMA High Performance & Others | Unfilled Glass Fibre Reinforced Flame Retardant Mineral Filled Alloys & Blends Recycled | Injection Moulding Extrusion Blow Moulding & Others | Direct Sales Distributors & Dealers Traders & Importers Online B2B Platforms Compounders | Automotive Electrical & Electronics Consumer Appliances Industrial & Machinery Medical Construction |
Report Scope
In this report, the India Engineering Plastics Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Product Type
- Acrylonitrile Butadiene Styrene (ABS) & SAN
- Polyamides (PA6, PA66, Specialty PA)
- Polycarbonate (PC)
- PBT & PET Engineering Grades
- Polyoxymethylene (POM)
- Polymethyl Methacrylate (PMMA)
- High Performance Polymers, Fluoropolymers & Others
- By Grade
- Unfilled
- Glass Fibre Reinforced
- Flame Retardant
- Mineral Filled
- Alloys & Blends
- Recycled
- By Processing Technology
- Injection Moulding
- Extrusion
- Blow Moulding & Others
- By Distribution Channel
- Direct Sales
- Distributors & Dealers
- Traders & Importers
- Online B2B Platforms
- Compounders
- By End-User
- Automotive & Transportation
- Electrical & Electronics
- Consumer Appliances
- Industrial & Machinery
- Medical & Healthcare
- Building & Construction
- Others
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Engineering Plastics Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging domestic compounders and recyclers, specialty additive and masterbatch suppliers, regional moulders and distributors, or niche high performance polymer importers.
The India Engineering Plastics Market report is part of our ongoing research coverage. For early access, customised insights, or to confirm the release timeline, please contact our team at sarita@marketresearchoutlook.com
Table of Contents
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Product Type
- By Grade
- By Processing Technology
- By Distribution Channel
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Engineering Plastics Market
- India Engineering Plastics Market Insights
- Market Dynamics
- Growth Drivers
- Rapid growth in automotive production, electric vehicle adoption, and lightweighting driving engineering plastics consumption across India.
- Electronics, appliance, and electrical equipment manufacturing expansion under PLI creating structural demand for flame retardant and high performance polymers.
- Domestic capacity additions, compounding investments, and trade protection strengthening local supply of engineering plastics.
- Restraints
- Dependence on imported polycarbonate, POM, PA66, and specialty polymers exposing converters to price and supply volatility.
- Price competition from low cost imports and thin conversion margins limiting profitability of smaller compounders and moulders.
- Regulatory scrutiny on halogenated flame retardants, BPA, and plastic waste restricting conventional engineering plastic formulations.
- Opportunities
- Recycled and bio-based engineering plastics opening premium circular material opportunities across urban India.
- EV battery housings, high voltage connectors, and lightweight structural parts supporting next generation engineering polymer growth.
- Semiconductor, medical device, and aerospace manufacturing under PLI creating new high performance polymer demand.
- Challenges
- Intense competition from unorganized recyclers and low priced imported compounds and finished components.
- Limited domestic availability of polycarbonate, POM, PA66, PPS, and specialty additive packages.
- Maintaining consistent mechanical properties, colour, and quality at scale across diverse Indian processing conditions.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Raw Materials (styrene, acrylonitrile, butadiene, caprolactam, bisphenol A, adipic acid, terephthalic acid, formaldehyde)
- Engineering Plastics Manufacturers (Reliance, INEOS Styrolution, Bhansali Engineering Polymers, Supreme Petrochem, GFL)
- Additive, Masterbatch & Reinforcement Suppliers (glass fibre, flame retardants, impact modifiers, colourants, stabilisers)
- Compounders & Alloy Makers (Kingfa, APPL Industries, Lanxess, Celanese, SABIC, BASF, DuPont)
- Quality Control, R&D & Testing Laboratories (BIS, ISO, ASTM, UL, REACH compliance testing)
- Distributors, Dealers & Traders (B2B polymer distribution networks)
- Moulders, Extruders & Component Makers (Motherson, Minda, Lumax, Dixon, Amber Enterprises, Supreme Industries)
- Automotive, Electronics & Appliance OEMs (Maruti Suzuki, Tata Motors, Hyundai, Samsung, LG, Voltas, Havells)
- Recyclers & Circular Material Processors (post-industrial and post-consumer engineering plastic recyclers)
- End-Users (automotive, electronics, appliances, industrial machinery, medical, construction, consumer goods)
- India Engineering Plastics Market: Regulatory Framework
- India Engineering Plastics Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (Thousand Tonnes)
- Market Share & Forecast
- By Product Type
- Acrylonitrile Butadiene Styrene (ABS) & SAN
- Polyamides (PA6, PA66, Specialty PA)
- Polycarbonate (PC)
- PBT & PET Engineering Grades
- Polyoxymethylene (POM)
- Polymethyl Methacrylate (PMMA)
- High Performance Polymers, Fluoropolymers & Others
- By Grade
- Unfilled
- Glass Fibre Reinforced
- Flame Retardant
- Mineral Filled
- Alloys & Blends
- Recycled
- By Processing Technology
- Injection Moulding
- Extrusion
- Blow Moulding & Others
- By Distribution Channel
- Direct Sales
- Distributors & Dealers
- Traders & Importers
- Online B2B Platforms
- Compounders
- By End-User
- Automotive & Transportation
- Electrical & Electronics
- Consumer Appliances
- Industrial & Machinery
- Medical & Healthcare
- Building & Construction
- Others
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Engineering Plastics Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Reliance Industries Ltd.
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- INEOS Styrolution India Ltd.
- Bhansali Engineering Polymers Ltd.
- Supreme Petrochem Ltd.
- SABIC India Pvt. Ltd.
- Covestro (India) Pvt. Ltd.
- BASF India Ltd.
- DuPont India Pvt. Ltd.
- Celanese India Pvt. Ltd.
- Lanxess India Pvt. Ltd.
- Gujarat Fluorochemicals Ltd.
- APPL Industries Ltd.
- Kingfa Science & Technology (India) Ltd.
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable
Frequently Asked Questions
1. How large is the India engineering plastics market and what is its growth forecast?
Ans:
Ans: The India engineering plastics market is valued at USD 4,650 million in 2025 and is projected to reach USD 7,920 million by 2032, growing at a CAGR of 7.9%, supported by automotive, electronics, and appliance demand.
2. Which segments are driving demand in the India engineering plastics market?
Ans: Ans: ABS and SAN lead with 31% value share across automotive and appliance applications, while high performance polymers and recycled engineering plastics are the fastest-growing segments, driven by electric vehicle makers, electronics assemblers, and appliance brands.
3. What are the key drivers of growth in the India engineering plastics market?
Ans: Ans: Key drivers include record automotive and electric vehicle production, electronics and appliance manufacturing under PLI, metal-to-plastic substitution, domestic ABS and compounding capacity additions, and BIS quality control orders and trade remedy actions on imports.
4. Which regions are driving growth in the India engineering plastics market?
Ans: Ans: West India and South India lead with 62% of total value, driven by Gujarat, Maharashtra, Tamil Nadu, Karnataka, and Telangana. North India and Delhi NCR also show strong automotive, electronics, and appliance demand.
5. What are the latest trends in the India engineering plastics market?
Ans: Ans: The latest trends include rapid adoption of recycled and halogen free engineering plastics, electric vehicle high voltage and battery applications, bio-based polyamides, compounding localisation by global majors, and anti-dumping led domestic ABS supply growth.
Frequently Asked Questions
1. How large is the India engineering plastics market and what is its growth forecast?
Ans:
Ans: The India engineering plastics market is valued at USD 4,650 million in 2025 and is projected to reach USD 7,920 million by 2032, growing at a CAGR of 7.9%, supported by automotive, electronics, and appliance demand.
2. Which segments are driving demand in the India engineering plastics market?
Ans: Ans: ABS and SAN lead with 31% value share across automotive and appliance applications, while high performance polymers and recycled engineering plastics are the fastest-growing segments, driven by electric vehicle makers, electronics assemblers, and appliance brands.
3. What are the key drivers of growth in the India engineering plastics market?
Ans: Ans: Key drivers include record automotive and electric vehicle production, electronics and appliance manufacturing under PLI, metal-to-plastic substitution, domestic ABS and compounding capacity additions, and BIS quality control orders and trade remedy actions on imports.
4. Which regions are driving growth in the India engineering plastics market?
Ans: Ans: West India and South India lead with 62% of total value, driven by Gujarat, Maharashtra, Tamil Nadu, Karnataka, and Telangana. North India and Delhi NCR also show strong automotive, electronics, and appliance demand.
5. What are the latest trends in the India engineering plastics market?
Ans: Ans: The latest trends include rapid adoption of recycled and halogen free engineering plastics, electric vehicle high voltage and battery applications, bio-based polyamides, compounding localisation by global majors, and anti-dumping led domestic ABS supply growth.