India Fluoropolymers Market: Process Industry Investment, Battery and Solar Manufacturing and Domestic PTFE and PVDF Capacity Power Structural Growth, Forecasts 2032
- Chemicals & Advanced Materials
- Sep 2026
- Pages 140
- Report Format: pdf
- Report Price: $1800 USD
India’s fluoropolymers market is witnessing strong structural growth, driven by record chemical, pharmaceutical, and specialty chemical capacity investment, expanding lithium ion battery, solar, and electric vehicle manufacturing under PLI, accelerating semiconductor, hydrogen, and data centre equipment demand, rising wire and cable, architectural membrane, and medical device localisation, growing demand for PVDF binders, FEP insulation, and ultra high purity PFA, and rising interest from domestic and global chemical majors investing in India-specific PTFE and PVDF capacity, backward integration, and application development.
| Study Duration | 2021-2032 |
| Market Size (2025) | USD 585 Million |
| CAGR (2026-2032) | 8.9% |
| Leading Segment | PTFE (Chemical Processing & Industrial) |
| Fastest Growing Segment | PVDF (Battery & Solar Applications) |
| Market Size (2032) | USD 1,060 Million |
Source: Market Research Outlook
Market Overview: India Fluoropolymers Market
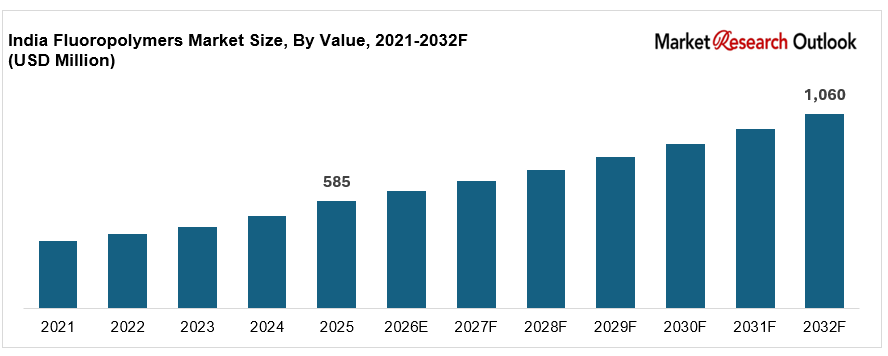
The India fluoropolymers market size is witnessing rapid expansion, driven by record chemical and pharmaceutical capacity investment, growing lithium ion battery and solar manufacturing, rising wire and cable, electronics, and electric vehicle production, expanding semiconductor, hydrogen, and medical device output, increasing demand for corrosion resistant, high temperature, and dielectric materials, and major capacity additions by domestic producers. Valued at USD 585 million in 2025 and projected to reach USD 1,060 million by 2032, growing at a CAGR of 8.9%, the India fluoropolymers market growth is being fuelled by strong demand from chemical process equipment makers, battery cell producers, and cable manufacturers, alongside BIS quality control orders on polymers and PLI incentives that are shifting demand toward domestic supply. PTFE leads consumption across lined equipment, seals, gaskets, and industrial components, while PVDF is emerging as the fastest growing category on battery binder and solar film demand. Shifting processor preferences toward modified and filled grades, growing energy transition and semiconductor needs, and rising PFAS conscious sourcing are reshaping the supply landscape. As domestic producers including Gujarat Fluorochemicals, SRF, and Navin Fluorine expand fluoropolymer and fluorochemical capacity, and global players including Daikin, Chemours, Arkema, Syensqo, AGC, 3M, and DuPont scale distribution and technical service networks, the India fluoropolymers market is evolving into a specification-led, innovation-driven, and increasingly self-reliant advanced materials ecosystem with strong long-term growth potential.
Key Report Takeaways: India Fluoropolymers Market
- The India fluoropolymers market size is projected to grow from USD 585 million in 2025 to USD 1,060 million by 2032, registering a strong CAGR of 8.9%, driven by accelerated chemical and pharmaceutical investment, rising battery, solar, and electronics demand, and the structural shift toward domestically produced and processed fluoropolymers across industrial India.
- PTFE dominates the India fluoropolymers market, accounting for 58% of total value in 2025, driven by its chemical inertness and low friction across lined pipes, valves, gaskets, seals, bearings, filtration fabrics, and non-stick coatings, the domestic manufacturing presence of Gujarat Fluorochemicals and SRF at Dahej, and rising demand across chemical, pharmaceutical, and industrial channels.
- PVDF is emerging as the fastest growing segment in the India fluoropolymers market, expected to grow at 13.2% annually as lithium ion cell makers, solar module producers, and architectural coating formulators reshape sourcing strategies toward battery binder, separator coating, backsheet film, and weatherable coating grades across Gujarat, Tamil Nadu, and Karnataka clusters.
- Rapid scaling of end-use manufacturing, with chemical and pharmaceutical capital expenditure exceeding INR 1.2 lakh crore across 2023 to 2025, solar module capacity crossing 100 GW, and electric vehicle sales exceeding 2 million units in FY25, is structurally expanding the India fluoropolymers market across chemical, energy, and electronics categories.
- Rising investments by domestic and global majors such as Gujarat Fluorochemicals, SRF, Navin Fluorine, Daikin, Arkema, and Syensqo in PTFE and PVDF capacity, hydrofluoric acid and R22 backward integration, and battery, solar, and semiconductor grades, together with BIS quality control orders on polymers and PLI incentives for batteries, solar, and electronics, are strengthening local supply and supporting the India fluoropolymers market forecast 2032.
Key Market Drivers: India Fluoropolymers Market
Rapid Growth in Chemical, Pharmaceutical, and Process Industry Investment Driving PTFE Lining, Seal, and Component Consumption Across India
Growth in the India fluoropolymers market is being driven by record chemical, pharmaceutical, and specialty chemical capacity investment, expanding fertiliser and refinery projects, and rising consumption of PTFE and PFA lined pipes, valves, vessels, gaskets, expansion joints, and filtration components across Gujarat, Maharashtra, Andhra Pradesh, and Telangana. Chemical and pharmaceutical companies including Reliance, Aarti Industries, Deepak Nitrite, Atul, PI Industries, Divi’s Laboratories, and Laurus Labs committed capital expenditure exceeding INR 1.2 lakh crore across 2023 to 2025, and each 1,000 crore of chemical plant investment consumes 18 to 25 tonnes of PTFE in lined equipment and sealing. Chemical processing and industrial applications absorb 34% of fluoropolymer consumption in India, led by lined equipment and component makers such as Mersen, Garlock, Klinger, Hindustan Nylons, and Sigma Roto Lining. PTFE granular and fine powder grades are priced between INR 900 and INR 1,300 per kilogram, while PFA and modified PTFE for lined valves command INR 2,200 to INR 3,500 per kilogram. Per capita fluoropolymer consumption in India remains below 0.06 kilograms per year compared with more than 0.4 kilograms in developed markets, indicating significant long-term headroom. Rising PCPIR chemical park development, pharmaceutical API localisation under PLI, and refinery expansions are creating strong structural pull-through demand across the India fluoropolymers market.
Source: Market Research Outlook
Lithium Ion Battery, Solar, and Electric Vehicle Manufacturing Expansion Creating Structural Demand for PVDF, FEP, and ETFE
The India fluoropolymers market is benefiting from sustained growth in lithium ion battery, solar, and electric vehicle manufacturing, with energy applications accounting for 14% of demand in 2025 and automotive and electric vehicles another 16%. Battery cell projects by Ola Cell Technologies, Reliance New Energy, Exide Energy, and Amara Raja under the advanced chemistry cell PLI scheme with an outlay of INR 18,100 crore consume 12 to 18 tonnes of PVDF binder and separator coating per gigawatt hour, and Indian cell capacity is expected to exceed 50 gigawatt hours by 2028. Solar module manufacturing capacity crossed 100 GW in FY25, with Waaree, Adani Solar, Premier Energies, and Vikram Solar qualifying PVDF and ETFE films for backsheets and front sheets. Electric vehicle sales exceeded 2 million units, and each electric passenger car consumes 2 to 3 kilograms of fluoropolymers across FEP and ETFE high voltage cable insulation, PTFE fuel and coolant hoses, FKM seals, and PVDF binders, with cable makers including Polycab, KEI, Havells, and Finolex scaling FEP and ETFE insulated wire lines. Battery and solar grade PVDF commands realisations of INR 2,000 to INR 3,200 per kilogram, compared with INR 1,100 to INR 1,500 per kilogram for coating grades, supporting mix improvement across the Indian fluoropolymers sector. Data centre cabling, 5G infrastructure, and grid investment of INR 9.15 lakh crore planned through 2032 are adding further demand for FEP and PTFE insulated cables.
Domestic PTFE and PVDF Capacity Additions, Backward Integration, and Import Substitution Strengthening Local Supply of Fluoropolymers
Domestic PTFE and PVDF capacity additions, backward integration, and import substitution are a major catalyst for the India fluoropolymers market, with imports still supplying 35% of fluoropolymers and 100% of PFA, ETFE, and semiconductor grade PVDF consumed in India in 2024. Gujarat Fluorochemicals operates an integrated fluoropolymer complex at Dahej with PTFE capacity of 48 thousand tonnes per annum plus PVDF, FEP, PFA, and FKM lines, backward integrated into fluorspar beneficiation, hydrofluoric acid, R22, and TFE monomer, and is expanding PVDF capacity for battery binder and solar film applications. SRF commissioned a PTFE plant at Dahej as part of its fluorochemicals expansion, and Navin Fluorine supplies R22, hydrofluoric acid, and specialty fluorochemical intermediates from Surat and Dahej. Processors including Hindustan Nylons, Sigma Roto Lining, Mersen, Garlock, and Klinger operate PTFE moulding, sintering, and lining lines in Gujarat, Maharashtra, Tamil Nadu, and Karnataka that supplied 61% of finished components in 2025. BIS quality control orders on polymers and the PLI schemes for advanced chemistry cells, solar modules, electronics, and automotive components are tightening import compliance and structurally expanding India fluoropolymers market growth across all major end-user categories through 2032.
Key Market Challenges: India Fluoropolymers Market
Dependence on Imported Fluorspar, TFE, and VDF Monomer Routes and Specialty Grades Exposing Processors to Price and Supply Volatility
The India fluoropolymers market continues to face challenges around feedstock and specialty grade dependence, with acid grade fluorspar imported largely from China, Mexico, Mongolia, and South Africa, and PFA, ETFE, MFA, FFKM, and semiconductor grade PVDF entirely sourced from Japan, the United States, Belgium, France, and China. India imports its full PFA requirement of 1,800 tonnes and full ETFE requirement of 900 tonnes, while specialty fluoroelastomers depend on Daikin, Chemours, Syensqo, and AGC supply. PVDF prices moved between USD 12 and USD 30 per kilogram during the 2022 battery driven spike before easing in 2024, PTFE ranged between USD 9 and USD 16 per kilogram, and acid grade fluorspar moved between USD 320 and USD 520 per tonne, compressing processor margins by 400 to 800 basis points in weak quarters. Chinese producers including Dongyue, Shanghai 3F, and Juhua have added PTFE and PVDF capacity that pressures Indian export realisations, and container freight disruptions in 2024 and 2025 stretched lead times for specialty grades to 10 to 16 weeks. Rupee depreciation and minimum order quantities from global producers add further cost uncertainty for downstream processors. India’s continued dependence on imported fluorspar and specialty grades limits pricing flexibility across the Indian fluoropolymers sector.
High Material Cost and Thin Conversion Margins Limiting Adoption Among Smaller Machining Shops and Lining Contractors
The India fluoropolymers market faces structural complexity from variations in material cost, processing know-how, and channel margins across different regions. Fluoropolymers cost 6 to 25 times more than commodity polymers such as polypropylene and PVC, and smaller machining shops and lining contractors often lack the sintering ovens, isostatic moulding, paste extrusion, and rotolining equipment required to process PTFE and PFA to specification. Chinese suppliers continue to offer PTFE stock shapes, dispersions, and finished gaskets and seals at prices 10% to 20% below domestic realisations, particularly in chemical process and industrial segments. Average EBITDA margins for standalone Indian PTFE processors and lining contractors range between 8% and 14%, and working capital cycles stretch to 90 to 130 days because imported resin must be paid upfront while chemical and infrastructure customers demand extended credit. Differential availability of testing, FDA and USP certification, and application support across states creates operational complexity for players such as Gujarat Fluorochemicals, SRF, Daikin, Chemours, and Arkema operating pan-India. While BIS quality control orders are improving discipline for imported products, cost barriers remain a near-term challenge for the domestic fluoropolymers industry.
Regulatory Scrutiny on PFAS, Fluorinated Processing Aids, and HFC Phase-Down Restricting Conventional Fluoropolymer Formulations
The India fluoropolymers market faces practical constraints around PFAS regulation, fluorinated processing aid restrictions, HFC phase-down, and reformulation costs across the value chain. The European Chemicals Agency is evaluating a universal PFAS restriction proposal covering fluoropolymers, and Indian exporters of PTFE, PVDF, and FEP components to Europe and the United States must qualify non-fluorinated processing aids and document polymer of low concern status, adding 10% to 18% to production cost. The European Union restricted C9 to C14 PFCAs from 2023 and the United States Environmental Protection Agency has tightened PFAS reporting under the Toxic Substances Control Act, affecting dispersions, non-stick coatings, and membranes. The Kigali Amendment schedule requires India to freeze HFC consumption in 2028 and cut it by 80% by 2047, affecting R22 and HFC based feedstock and by-product economics for integrated producers. BIS quality control orders on polymers and the Plastic Waste Management Rules with extended producer responsibility obligations require importers and brand owners to certify quality and manage end-of-life recovery of fluoropolymer components. Reformulating to PFAS free processing routes or reprocessed grades adds 12% to 25% to raw material cost and requires requalification with OEMs. Smaller processors face additional compliance complexity under REACH registration, FDA, and USP Class VI certification for export and medical grades. Non-fluorinated processing aids, recycled PTFE micropowder, and reprocessed PVDF are emerging as solutions to differentiate, but higher pricing and limited qualification bandwidth remain barriers to widespread adoption across the domestic fluoropolymers industry.
Key Market Trends: India Fluoropolymers Market
Rapid Adoption of PFAS Free Processing, Recycled PTFE Micropowder, and Reprocessed Fluoropolymer Grades in India
The India fluoropolymers market is undergoing a clear technology shift toward PFAS free processing, recycled PTFE micropowder, and reprocessed fluoropolymer grades, with these advanced variants expected to capture 18% of new grades by 2028. Non-fluorinated processing aids for PTFE dispersions and non-stick coatings replace legacy surfactants in export oriented supply chains, while reprocessed PTFE micropowder from machining scrap and sintered waste delivers 20% to 30% cost savings in lubricants, inks, coatings, and thermoplastic additives. Reprocessed PVDF from solar film and battery scrap and recycled FEP from cable waste are also entering coating and moulding applications at 15% to 25% below prime pricing. Leading domestic and global players including Gujarat Fluorochemicals, SRF, Daikin, Chemours, Arkema, Syensqo, and AGC have introduced PFAS free processed, reprocessed, and modified ranges for the Indian market through 2024 and 2025. Mechanical and chemical recycling of PTFE and PVDF scrap is gaining traction, particularly in Gujarat and Maharashtra where chemical, cable, and cookware makers are preparing for extended producer responsibility and export compliance obligations. This product transition is reinforcing the India fluoropolymers market forecast 2032 across both industrial and energy categories.
Growth of Battery, Semiconductor, and Hydrogen Equipment Applications in the India Fluoropolymers Market
A clear shift toward battery, semiconductor, and hydrogen equipment applications is reshaping the India fluoropolymers market, particularly in the energy and electronics segments. Lithium ion cell manufacturing capacity in India is expected to exceed 50 gigawatt hours by 2028 under the advanced chemistry cell PLI scheme, with each gigawatt hour consuming 12 to 18 tonnes of PVDF binder and separator coating alongside PTFE and FEP components in cell holders, busbars, and electrolyte handling. Semiconductor assembly, test, and fab projects by Tata Electronics, Micron, CG Power, and Kaynes are adding demand for ultra high purity PFA, PTFE, and PVDF piping, valves, wafer carriers, and wet bench parts, while the India Semiconductor Mission with an outlay of INR 76,000 crore is drawing global fluoropolymer component suppliers to Gujarat and Assam. The National Green Hydrogen Mission with an outlay of INR 19,744 crore is driving demand for PFA and PTFE lined electrolyser frames, seals, membranes, and storage components, and solar cell and module makers including Waaree, Adani Solar, and Premier Energies are qualifying PVDF and ETFE films. Energy and semiconductor applications accounted for 14% of fluoropolymer demand in 2025 and are expected to reach 21% by 2032, with cell, fab, and electrolyser makers increasingly preferring locally supplied resin to shorten qualification cycles.
Capacity Expansion, Backward Integration, and Import Substitution by Domestic and Global Fluoropolymer Majors
A wave of capacity expansion, backward integration, and import substitution is reshaping the India fluoropolymers market supply landscape. Combined India-focused capital expenditure announcements in fluoropolymer, fluorochemical, and processing capacity exceeded USD 650 million across 2023 to 2025. Gujarat Fluorochemicals is expanding PVDF and battery chemical capacity at Dahej alongside its 48 thousand tonne PTFE complex and FEP, PFA, and FKM lines, SRF commissioned PTFE and expanded fluorochemical intermediates at Dahej, Navin Fluorine added hydrofluoric acid and specialty fluorochemical capacity at Dahej and Surat, and Daikin, Chemours, Arkema, Syensqo, AGC, 3M, and DuPont have strengthened distribution, warehousing, and technical service teams in Gujarat, Maharashtra, Tamil Nadu, and Karnataka. BIS quality control orders on polymers, PLI allocations for advanced chemistry cells, solar modules, electronics, and automotive components, and the National Green Hydrogen Mission have structurally favoured organized domestic supply. Combined with chemical, battery, and semiconductor capacity additions driving specialty grade demand and export orders to Europe, the Middle East, and Southeast Asia, these developments are reinforcing the India fluoropolymers market forecast 2032 across the entire value chain.
Segmental Insights: India Fluoropolymers Market
By End-User: Chemical Processing & Industrial Segment Dominates the India Fluoropolymers Market
The chemical processing and industrial end-user segment dominates the India fluoropolymers market, accounting for 34% of total value in 2025, driven by record chemical and pharmaceutical capacity investment, growing corrosion resistant equipment consumption, and improving lifecycle cost economics. PTFE and PFA lined pipes, valves, vessels, gaskets, expansion joints, bearings, and filtration fabrics are the dominant products within this segment, with lined equipment and sealing capturing 52% of chemical related fluoropolymer purchases. The electrical and electronics segment contributes another 21% of demand, driven by FEP and PTFE insulated wire and cable, PVDF and PTFE films, and semiconductor components across Tamil Nadu, Karnataka, Uttar Pradesh, and Gujarat clusters. The automotive and electric vehicles segment accounts for 16%, led by high voltage cable insulation, FKM seals, PTFE hoses, and PVDF binders, while energy contributes 14% through solar films, battery chemicals, and hydrogen equipment, building and architecture adds 6% through PVDF coatings and ETFE and PTFE membranes, and medical and pharmaceutical adds 5% through implants, tubing, and filtration. In 2025, leading fluoropolymer players including Gujarat Fluorochemicals, SRF, Daikin, Chemours, Arkema, and Syensqo scaled up chemical processing and energy focused resin and compound supply, reinforcing segment dominance in the Indian fluoropolymers sector.
By Product Type: PTFE Leads While PVDF Grows Fastest
PTFE leads the India fluoropolymers market product landscape, accounting for 58% of total value, driven by its chemical inertness, low friction, and thermal stability across lined equipment, seals, gaskets, bearings, filtration fabrics, cable insulation, and non-stick coatings. PVDF contributes another 17%, primarily across battery binders, solar films, architectural coatings, chemical piping, and membranes, while FEP accounts for 8% through wire and cable insulation, lined pipes, and films. PVDF is the fastest growing category within the Indian fluoropolymers sector, expanding at 13.2% annually, driven by lithium ion cell manufacturing under the advanced chemistry cell PLI scheme, solar module capacity crossing 100 GW, and weatherable coating demand for metal roofing and facades. PFA and MFA account for 6% of the market through semiconductor and lined valve applications, fluoroelastomers contribute 6% through seals, O-rings, and hoses for automotive and chemical service, and ETFE, ECTFE, PCTFE, PVF, and other grades add 5%, with the semiconductor, hydrogen, and medical grade segment expected to grow rapidly through 2032. Leading manufacturers including Gujarat Fluorochemicals, SRF, Daikin, Chemours, Arkema, Syensqo, AGC, Kureha, and Dongyue have aligned product portfolios to this mix, driving specialty fluoropolymer adoption across the India fluoropolymers market.
Regional Insights: India Fluoropolymers Market
Regional analysis of the India fluoropolymers market shows that West India and South India collectively account for 68% of total fluoropolymer value, driven by Gujarat (Dahej fluoropolymer complexes of Gujarat Fluorochemicals and SRF, Ankleshwar, Vapi, and Jhagadia chemical processing belt, Sanand semiconductor cluster), Maharashtra (Mumbai, Pune, and Tarapur chemical, cable, and processing belt), Tamil Nadu (Chennai and Hosur electric vehicle, electronics, and cell manufacturing cluster, Cuddalore chemical zone), Karnataka (Bengaluru aerospace, medical device, and semiconductor design), Andhra Pradesh (Visakhapatnam pharmaceutical and chemical cluster), and Telangana (Hyderabad pharmaceutical and medical device parks), supported by resin plants, processors, ports, and strong industrial consumption levels. North India contributes 20% of demand, led by Haryana, Delhi NCR, Uttar Pradesh, Rajasthan, and Punjab, supported by wire and cable manufacturing, automotive clusters, electronics assembly in Noida and Greater Noida, and fertiliser and refinery projects. Central and East India together account for 12% of demand, supported by Madhya Pradesh, West Bengal, Odisha, Jharkhand, and Assam, where fertiliser, steel, power, and semiconductor assembly demand is accelerating. In 2025, capacity and distribution operations by Gujarat Fluorochemicals, SRF, and Navin Fluorine across Gujarat, Hindustan Nylons and Sigma Roto Lining across Maharashtra, Mersen and Garlock across Maharashtra and Tamil Nadu, and Daikin, Chemours, and Arkema distribution across Gujarat, Maharashtra, and Karnataka reinforced regional supply hubs, supporting closer execution of chemical, energy, and electronics projects across the India fluoropolymers market.
Recent Developments: India Fluoropolymers Market
- The India fluoropolymers market witnessed strong momentum in policy support and capacity progress during 2024 and 2025. BIS quality control orders on polymers moved toward implementation, the India Semiconductor Mission approved additional assembly, test, and fab projects with an outlay of INR 76,000 crore, the National Green Hydrogen Mission advanced electrolyser manufacturing under its INR 19,744 crore outlay, and the advanced chemistry cell PLI scheme with an outlay of INR 18,100 crore advanced battery cell projects by Ola Cell Technologies, Reliance New Energy, and Amara Raja. Domestic fluoropolymer consumption is projected to reach 76 thousand tonnes in 2025 and 132 thousand tonnes by 2032, growing at 8.2% annually in volume terms, while solar module capacity crossed 100 GW and electric vehicle sales exceeded 2 million units in FY25.
- Domestic and global fluoropolymer majors have deepened India-focused capacity expansion. Gujarat Fluorochemicals is expanding PVDF and battery chemical capacity at Dahej alongside its 48 thousand tonne per annum PTFE complex and FEP, PFA, and FKM lines, SRF commissioned its PTFE plant at Dahej and expanded fluorochemical intermediates, and Navin Fluorine added hydrofluoric acid and specialty fluorochemical capacity at Dahej and Surat. Daikin, Chemours, Arkema, Syensqo, AGC, 3M, and DuPont strengthened distribution, warehousing, and technical service teams, and processors including Hindustan Nylons, Sigma Roto Lining, Mersen, and Garlock added moulding, sintering, and lining capacity across Gujarat, Maharashtra, Tamil Nadu, and Karnataka. These developments are strengthening domestic supply and supporting the India fluoropolymers market forecast 2032.
- Chemical, energy, and electronics momentum has gained strong traction in the India fluoropolymers market. In 2025, chemical and pharmaceutical majors including Reliance, Aarti Industries, Deepak Nitrite, Divi’s Laboratories, and Laurus Labs commissioned lined equipment intensive capacity, solar and battery makers including Waaree, Adani Solar, Premier Energies, and Exide Energy expanded PVDF film and binder consumption, and cable makers including Polycab, KEI, Havells, and Finolex scaled FEP and ETFE insulated wire production for electric vehicle, data centre, and solar applications. Strategic partnerships between fluoropolymer producers, processors, OEMs, and semiconductor and hydrogen project developers are positioning India as one of the most actively scaling fluoropolymer markets globally, strengthening long-term competitive positioning in the India fluoropolymers market forecast 2032.
Key Market Players: India Fluoropolymers Market
- Gujarat Fluorochemicals Ltd.
- SRF Ltd.
- Navin Fluorine International Ltd.
- Daikin Industries, Ltd.
- The Chemours Company
- Arkema India Pvt. Ltd.
- Syensqo (Solvay) Specialities India Pvt. Ltd.
- AGC Chemicals
- 3M India Ltd.
- Dongyue Group Ltd.
- Kureha Corporation
- DuPont India Pvt. Ltd.
- Shanghai 3F New Materials Co., Ltd.
| By Product Type | By Form | By Processing | By Distribution | By End-User |
| PTFE PVDF FEP PFA & MFA ETFE & ECTFE Fluoroelastomers PCTFE, PVF & Others | Granules & Pellets Fine Powder & Micropowder Dispersions & Coatings Films & Sheets Fibres & Membranes Compounds & Filled Grades | Compression Moulding & Sintering Extrusion & Injection Moulding Coating & Dispersion Casting | Direct Sales Distributors & Dealers Traders & Importers Online B2B Platforms Compounders & Processors | Chemical & Industrial Electrical & Electronics Automotive & EV Energy Building & Architecture Medical |
Report Scope
In this report, the India Fluoropolymers Market has been segmented into the following categories, in addition to detailed analysis of key industry trends, market dynamics, competitive landscape, and growth opportunities across the forecast period:
- By Product Type
- Polytetrafluoroethylene (PTFE)
- Polyvinylidene Fluoride (PVDF)
- Fluorinated Ethylene Propylene (FEP)
- Perfluoroalkoxy (PFA) & MFA
- ETFE & ECTFE
- Fluoroelastomers (FKM, FFKM)
- PCTFE, PVF & Others
- By Form
- Granules & Pellets
- Fine Powder & Micropowder
- Dispersions & Coatings
- Films & Sheets
- Fibres & Membranes
- Compounds & Filled Grades
- By Processing Technology
- Compression Moulding & Sintering
- Extrusion & Injection Moulding
- Coating & Dispersion Casting
- By Distribution Channel
- Direct Sales
- Distributors & Dealers
- Traders & Importers
- Online B2B Platforms
- Compounders & Processors
- By End-User
- Chemical Processing & Industrial
- Electrical & Electronics
- Automotive & Electric Vehicles
- Energy (Solar, Battery, Hydrogen)
- Building & Architecture
- Medical & Pharmaceutical
- Others
- By Geography
- North India
- South India
- West India
- East India
- Central India
Competitive Landscape
Company Profiles:
Detailed analysis of the leading companies operating in the India Fluoropolymers Market, including business overview, product portfolio, strategic initiatives, competitive positioning, and recent developments.
Company Information
Detailed profiling and strategic analysis of additional market players (up to five companies), including emerging domestic PTFE processors and lining contractors, dispersion and coating formulators, regional distributors, or niche semiconductor and medical grade fluoropolymer importers.
The India Fluoropolymers Market report is part of our ongoing research coverage. For early access, customised insights, or to confirm the release timeline, please contact our team at sarita@marketresearchoutlook.com
Table of Contents
- Research Framework
- Market Segmentation
- Research Objective
- Research Methodology
- Qualitative Research
- Primary Research
- Secondary Research
- Quantitative Research
- Market Breakdown & Data Triangulation
- Demand Side
- Supply Side
- Primary Research Respondents
- Assumption & Limitation
- Executive Summary
- Market Overview, 2021-2032
- By Product Type
- By Form
- By Processing Technology
- By Distribution Channel
- By End-User
- By Region
- Analyst Recommendations
- Geopolitical Impact on India Fluoropolymers Market
- India Fluoropolymers Market Insights
- Market Dynamics
- Growth Drivers
- Rapid growth in chemical, pharmaceutical, and process industry investment driving PTFE lining, seal, and component consumption across India.
- Lithium ion battery, solar, and electric vehicle manufacturing expansion creating structural demand for PVDF, FEP, and ETFE.
- Domestic PTFE and PVDF capacity additions, backward integration, and import substitution strengthening local supply of fluoropolymers.
- Restraints
- Dependence on imported fluorspar, TFE, and VDF monomer routes and specialty grades exposing processors to price and supply volatility.
- High material cost and thin conversion margins limiting adoption among smaller machining shops and lining contractors.
- Regulatory scrutiny on PFAS, fluorinated processing aids, and HFC phase-down restricting conventional fluoropolymer formulations.
- Opportunities
- PFAS free processing, recycled PTFE micropowder, and reprocessed grades opening premium circular material opportunities across urban India.
- PVDF battery binders, solar films, and high voltage cable insulation supporting next generation fluoropolymer growth.
- Semiconductor, hydrogen electrolyser, and medical device manufacturing under PLI creating new ultra high purity fluoropolymer demand.
- Challenges
- Intense competition from low priced imported stock shapes, dispersions, and finished PTFE components.
- Limited domestic availability of PFA, ETFE, semiconductor grade PVDF, and specialty fluoroelastomers.
- Maintaining consistent purity, sintering quality, and performance at scale across diverse Indian processing conditions.
- Technological Advancements
- Recent Technological Advancements
- Prior to 2020
- Porter’s Five Forces Analysis
- PESTLE Analysis
- Industry Value Chain & Entry Points
- Upstream Raw Materials (fluorspar, sulphuric acid, hydrofluoric acid, R22, chloroform, TFE, VDF, HFP monomers)
- Fluoropolymer Manufacturers (Gujarat Fluorochemicals, SRF, Daikin, Chemours, Arkema, Syensqo, AGC, Dongyue)
- Additive, Filler & Reinforcement Suppliers (glass fibre, carbon, graphite, bronze, PEEK, pigments, stabilisers)
- Compounders & Processors (filled PTFE compounders, dispersion formulators, film and membrane makers)
- Quality Control, R&D & Testing Laboratories (BIS, ISO, ASTM, FDA, USP, REACH compliance testing)
- Distributors, Dealers & Traders (B2B specialty polymer distribution networks)
- Moulders, Extruders & Stock Shape Machiners (rods, sheets, tubes, gaskets, seals, lined pipes, cables)
- Chemical, Energy & Electronics OEMs (Reliance, Aarti Industries, Waaree, Exide Energy, Polycab, Dixon)
- Lining, Coating & Installation Contractors (PTFE and PFA lining, non-stick coating, membrane roofing applicators)
- End-Users (chemical processing, electronics, automotive, energy, construction, medical, cookware, textiles)
- India Fluoropolymers Market: Regulatory Framework
- India Fluoropolymers Market Overview
- Market Size & Forecast, 2021-2032
- By Value (USD Million)
- By Volume (Thousand Tonnes)
- Market Share & Forecast
- By Product Type
- Polytetrafluoroethylene (PTFE)
- Polyvinylidene Fluoride (PVDF)
- Fluorinated Ethylene Propylene (FEP)
- Perfluoroalkoxy (PFA) & MFA
- ETFE & ECTFE
- Fluoroelastomers (FKM, FFKM)
- PCTFE, PVF & Others
- By Form
- Granules & Pellets
- Fine Powder & Micropowder
- Dispersions & Coatings
- Films & Sheets
- Fibres & Membranes
- Compounds & Filled Grades
- By Processing Technology
- Compression Moulding & Sintering
- Extrusion & Injection Moulding
- Coating & Dispersion Casting
- By Distribution Channel
- Direct Sales
- Distributors & Dealers
- Traders & Importers
- Online B2B Platforms
- Compounders & Processors
- By End-User
- Chemical Processing & Industrial
- Electrical & Electronics
- Automotive & Electric Vehicles
- Energy (Solar, Battery, Hydrogen)
- Building & Architecture
- Medical & Pharmaceutical
- Others
- By Geography
- North India
- South India
- West India
- East India
- Central India
- Competitive Landscape
- India Fluoropolymers Market Company Market Share Analysis, 2025
- Competitive Benchmarking, By Operating Parameters
- Key Strategic Development (Mergers, Acquisitions, Partnerships, Etc.)
- List of Emerging Players
- Company Profile
- Gujarat Fluorochemicals Ltd.
- Introduction & Company Profile
- Product Benchmarking
- Strategic Outlook
- Key Competitors
- Financial Analysis
- SWOT Analysis
(Same Data Pointers Will Be Provided for The Below Companies)
- SRF Ltd.
- Navin Fluorine International Ltd.
- Daikin Industries, Ltd.
- The Chemours Company
- Arkema India Pvt. Ltd.
- Syensqo (Solvay) Specialities India Pvt. Ltd.
- AGC Chemicals
- 3M India Ltd.
- Dongyue Group Ltd.
- Kureha Corporation
- DuPont India Pvt. Ltd.
- Shanghai 3F New Materials Co., Ltd.
- Other Prominent Players
* Financial information in case of non-listed companies will be provided as per availability
** The segmentation and the companies are subjected to modifications based on in-depth secondary for the final deliverable.
Frequently Asked Questions
1. How large is the India fluoropolymers market and what is its growth forecast?
Ans: The India fluoropolymers market is valued at USD 585 million in 2025 and is projected to reach USD 1,060 million by 2032, growing at a CAGR of 8.9%, supported by chemical processing, battery, solar, and electronics demand
2. Which segments are driving demand in the India fluoropolymers market?
Ans: PTFE leads with 58% value share across lined equipment, seals, and industrial components, while PVDF is the fastest-growing segment, driven by lithium ion battery binders, solar films, and architectural coatings.
3. What are the key drivers of growth in the India fluoropolymers market?
Ans: Key drivers include record chemical and pharmaceutical capacity investment, battery, solar, and electric vehicle manufacturing under PLI, semiconductor and hydrogen equipment demand, domestic PTFE and PVDF capacity additions, and BIS quality control orders.
4. Which regions are driving growth in the India fluoropolymers market?
Ans: West India and South India lead with 68% of total value, driven by Gujarat, Maharashtra, Tamil Nadu, Karnataka, Andhra Pradesh, and Telangana. North India and Delhi NCR also show strong cable, automotive, and electronics demand.
5. What are the latest trends in the India fluoropolymers market?
Ans: The latest trends include rapid adoption of PVDF battery binders and solar films, PFAS free processing and recycled PTFE micropowder, semiconductor and hydrogen grade PFA and PTFE, FEP high voltage cables, and backward integration by domestic producers.
Frequently Asked Questions
1. How large is the India fluoropolymers market and what is its growth forecast?
Ans: The India fluoropolymers market is valued at USD 585 million in 2025 and is projected to reach USD 1,060 million by 2032, growing at a CAGR of 8.9%, supported by chemical processing, battery, solar, and electronics demand
2. Which segments are driving demand in the India fluoropolymers market?
Ans: PTFE leads with 58% value share across lined equipment, seals, and industrial components, while PVDF is the fastest-growing segment, driven by lithium ion battery binders, solar films, and architectural coatings.
3. What are the key drivers of growth in the India fluoropolymers market?
Ans: Key drivers include record chemical and pharmaceutical capacity investment, battery, solar, and electric vehicle manufacturing under PLI, semiconductor and hydrogen equipment demand, domestic PTFE and PVDF capacity additions, and BIS quality control orders.
4. Which regions are driving growth in the India fluoropolymers market?
Ans: West India and South India lead with 68% of total value, driven by Gujarat, Maharashtra, Tamil Nadu, Karnataka, Andhra Pradesh, and Telangana. North India and Delhi NCR also show strong cable, automotive, and electronics demand.
5. What are the latest trends in the India fluoropolymers market?
Ans: The latest trends include rapid adoption of PVDF battery binders and solar films, PFAS free processing and recycled PTFE micropowder, semiconductor and hydrogen grade PFA and PTFE, FEP high voltage cables, and backward integration by domestic producers.